
Can First Merchants (FRME) Justify Its Valuation Ahead Of Earnings?
First Merchants (FRME) is back in focus as traders weigh an upcoming earnings release and a fresh preferred dividend declaration that clarifies cash returns to a specific slice of the bank’s capital structure.
At a share price of US$39.38, First Merchants has seen short term momentum cool, with the 30 day share price return down 3.65% and the 90 day share price return down 10.56%. Even so, the year to date share price return is 5.01% and the 3 year total shareholder return is 65.13%. This suggests that investors are reassessing near term risk around the upcoming earnings release rather than abandoning the longer term story.
Compare how First Merchants stacks up against other banks preparing for key catalysts by scanning our hand picked 32 resilient stocks with low risk scores that aim to balance resilience with potential upside.
Short term weakness, steady earnings expectations and a clear preferred dividend track record put First Merchants at an interesting crossroads. Does that mix still offer a better deal for new buyers than for sellers here?
Most Popular Narrative: 16% Undervalued
First Merchants is priced at US$39.38 while the most followed narrative pegs fair value closer to US$47. The current setup leans toward a valuation gap that depends on how credit costs, loan mix and capital returns actually develop.
Ongoing capital strength, tangible book value per share of US$29.80, and management's continued use of share repurchases and dividends, including a new US$100m buyback authorization and a common dividend yield above 3.5%, provide room for higher earnings per share and total shareholder return as capital is deployed.
See why 3 investors see First Merchants as 16% undervalued.
Result: Fair Value of $47 (UNDERVALUED)
Still, the First Merchants narrative can be knocked off course if recent US$33m credit provisions signal broader asset quality issues, or if higher cost subordinated debt compresses future returns.
Find out about the key risks to this First Merchants narrative.
Another View on First Merchants' Valuation
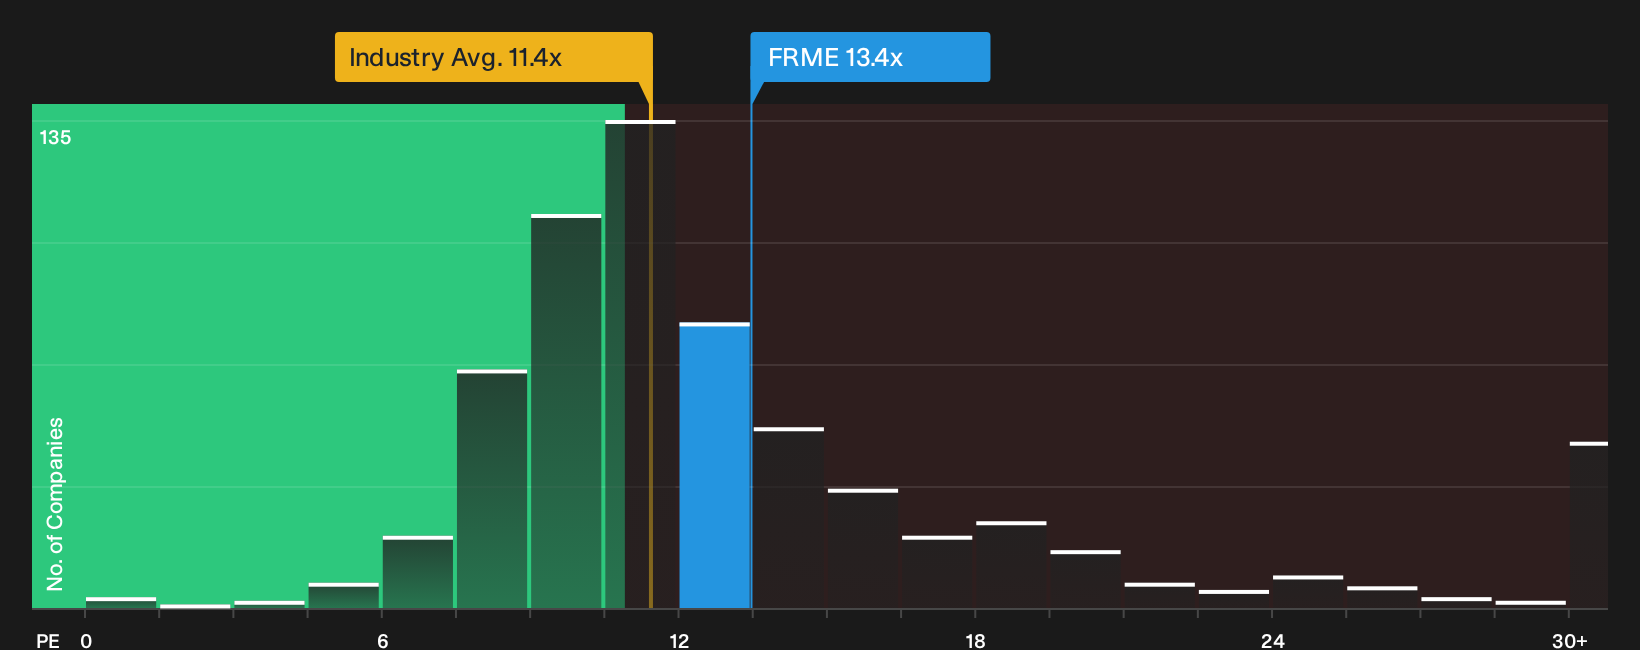
On simple P/E terms, First Merchants looks less clear cut. The stock trades at 13.4x earnings, which is higher than the US Banks industry at 11.5x and a touch above similar peers at 13x, yet still below an estimated fair ratio of 14.3x. Is that a margin of safety or a warning label for you?
For a fuller picture of how this valuation gap could close in either direction, and what the numbers imply for future upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around First Merchants may look tilted one way today, yet the numbers leave room for very different conclusions depending on your priorities and risk tolerance. Act before the next set of headlines arrives by weighing both the current pricing debate and the potential rewards investors are watching through the 3 key rewards.
Looking for more investment ideas beyond First Merchants?
If you stop with First Merchants, you only see one angle. Broaden your watchlist with fresh ideas that match how you actually like to invest.
- Target stronger protection on the downside by scanning a 32 resilient stocks with low risk scores that filters for resilience before potential upside.
- Hunt for better value by checking a 35 high quality undervalued stocks that highlights companies with quality fundamentals priced below what the numbers suggest.
- Build a sturdier income stream by reviewing a 8 dividend fortresses that focuses on higher yielding payouts backed by solid financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com