
Is Selective Insurance Group (SIGI) Cheap On Its New Chief Investment Officer Appointment?
Selective Insurance Group (SIGI) just confirmed Vaibhav Kalia as Executive Vice President and Chief Investment Officer, formalizing his interim role and putting long term portfolio decisions more squarely in focus for shareholders.
Recent price action reflects that backdrop. The share price is at US$88.87 after a 4.65% 7 day share price return. However, the 90 day share price performance is down 10.01%, and the 1 year total shareholder return of 8.44% contrasts with a weaker 3 year total shareholder return of an 8.71% decline. This suggests momentum has picked up only in the short term as investors absorb leadership changes and reassess how Selective Insurance Group’s investment decisions could alter the risk profile over time.
Scan how Selective Insurance Group compares with other insurers wrestling with investment risk and return by checking our hand picked 32 resilient stocks with low risk scores.
Selective Insurance Group shares have bounced in the very near term, while longer term returns still look mixed. Does that balance of setback and recent strength leave more upside potential than downside risk at today’s price?
Most Popular Narrative: 12.8% Undervalued
Selective Insurance Group is trading at $88.87 against a widely followed fair value estimate of about $101.86, so the market is pricing in a clear discount while analysts focus on execution in underwriting and investment income.
The company's ongoing focus and investments in operational efficiency, including data analytics, digital claims management, and underwriting tools, are now supported by more than double the discretionary IT project spend since 2023 and early AI deployment in claims and contractual risk-transfer reviews. These initiatives could continue to influence the expense ratio and operating margins.
See why 11 investors see Selective Insurance Group as 13% undervalued.
Result: Fair Value of $101.86 (UNDERVALUED)
Still, the story around Selective Insurance Group can change quickly if casualty claim severities continue to surprise on the high side or if stricter pricing slows commercial premium growth.
Find out about the key risks to this Selective Insurance Group narrative.
Another View: What P/E Says About Selective Insurance Group
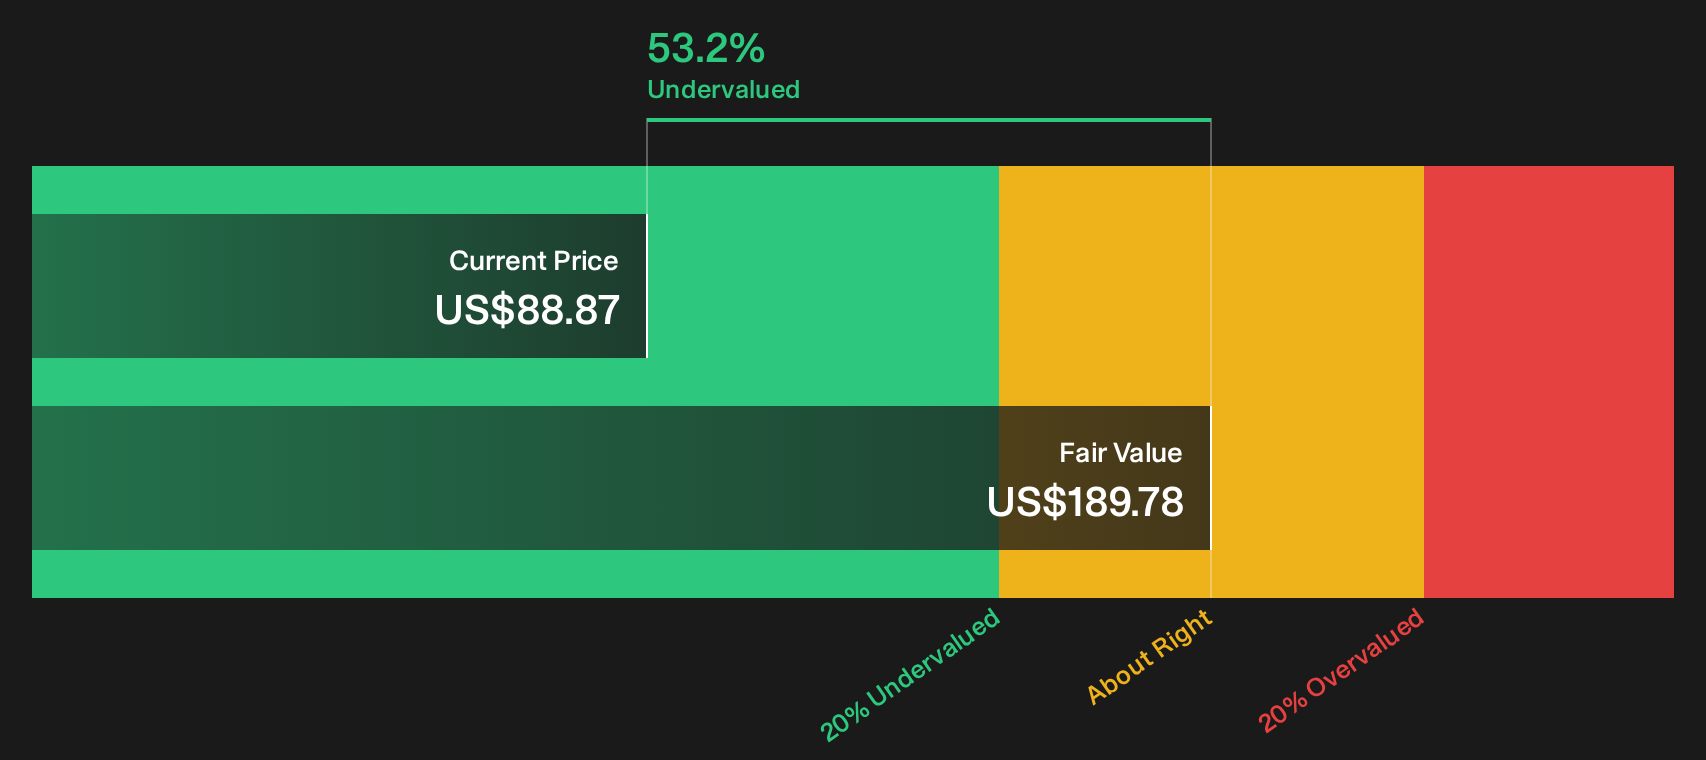
The SWS DCF workup presents Selective Insurance Group as materially undervalued, with an estimated future cash flow value of $189.78 against a share price of $88.87. The P/E perspective is less generous. SIGI trades on 10.8x earnings, slightly above its 10.6x fair ratio and well above the 8.1x peer average, while being roughly in line with the broader US Insurance group at 11x. That combination of a wide DCF gap and a richer peer P/E leads to a straightforward question for you: Is the larger risk that the cash flow model is too optimistic, or that the market eventually moves the peer group valuation closer to SIGI's current multiple?
Look into how the SWS DCF model arrives at its fair value. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Selective Insurance Group is clearly split, with both concerns and bright spots in play. Move quickly and check the underlying data yourself. To see that balance set out in one place, take a look at the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Selective Insurance Group?
Do not stop with one opportunity. Broaden your watchlist now with fresh ideas filtered by quality, price, and resilience using the Simply Wall Street Screener.
- Target dependable income by focusing on companies built around steady payouts with the 8 dividend fortresses.
- Hunt for mispriced quality by zeroing in on stocks that screen as high quality yet potentially cheap through the 35 high quality undervalued stocks.
- Prioritize financial strength by filtering for companies with robust balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com