
Western Union (WU) Stock May Sit Below Fair Value On Earnings Pressure
Western Union has seen its share price decline sharply over recent years, which puts fresh focus on whether the current market value lines up with what the business is earning. For anyone considering the stock today, the key issue is how those earnings stack up against the price now being paid.
- Over the past 5 years the share price has fallen 51.7%, which puts pressure on the case that the present valuation is adequately supported by the company’s earnings power.
- The core money transfer model still depends heavily on how efficiently Western Union converts revenue into profit and free cash flow, which can shape what investors are prepared to pay for each dollar of earnings.
- The analysts covering Western Union have run their own numbers. See what analysts think Western Union's shares could be worth.
The issue now is whether Western Union's current share price is justified by the earnings it is generating today and what investors expect those earnings to look like over time.
If you want context for Western Union's earnings driven story, compare it with other value ideas using the 35 high quality undervalued stocks.
Is Western Union a Bargain on Earnings?
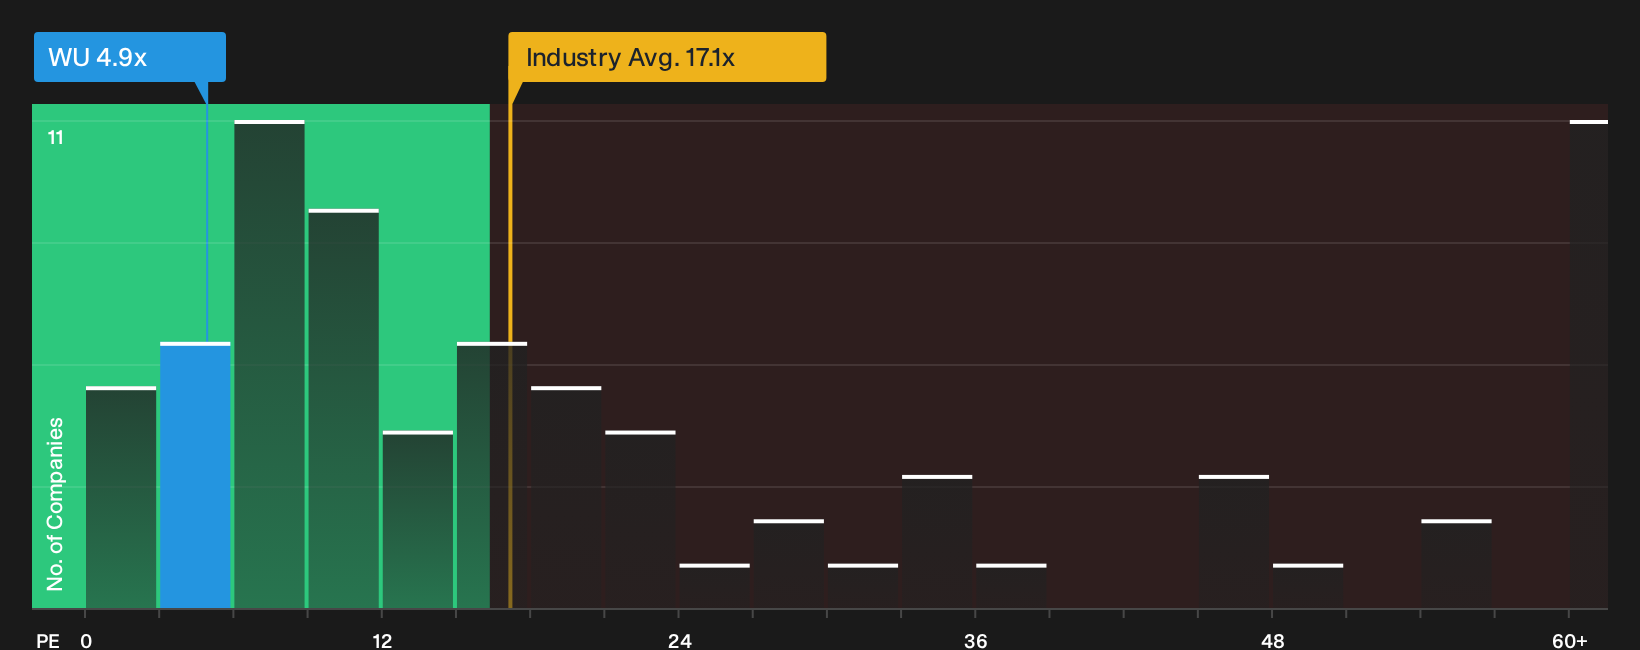
The P/E ratio fits Western Union because earnings remain the main anchor for how this stock is usually judged. Right now the shares trade on a P/E of 4.9x, compared with a Diversified Financial industry average around 17.1x and a peer group average near 55.3x. That is a steep gap for a mature, profit-making business, so the question for you is whether the earnings stream is weaker or riskier than those benchmarks imply.
The internal fair P/E estimate, which adjusts for Western Union's own growth profile, margins, size and risk, still points to a higher level than where the stock trades today. That suggests the current multiple sits below what this model would flag as a more typical pricing and that sentiment around the shares is more cautious than the earnings line alone would indicate. If you want to see how that model-derived P/E compares in detail and how much headroom it implies, check the fuller valuation breakdown in. Explore the numbers behind Western Union's P/E valuation.
The Western Union Narrative: What Would Justify Today's Price?
Narratives for Western Union pick up where the P/E puzzle leaves off, outlining which paths for growth, profitability and earnings would need to occur for the stock to be worth materially more or less than today's price. These narratives are available on Simply Wall St's Community page. Instead of a single output from a ratio or valuation model, these scenarios describe the future assumptions behind that figure so you can later check whether the story is still on track.
One of the top community narratives on Western Union: 10% undervalued
"The ongoing digital transformation, including expanded digital wallet offerings, card-based retail transactions, and value-added services, remains in progress..."
Discover why this Narrative puts Western Union at 10% undervalued.
Before you act on Western Union's valuation, there is one more lever to check
Price and earnings only tell part of the story, because the people steering Western Union, how they are rewarded, and whether those incentives align with your goals can heavily influence what happens next. See who runs Western Union and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com