
Upcoming Earnings Could Be A Big Test For Trustmark (TRMK)
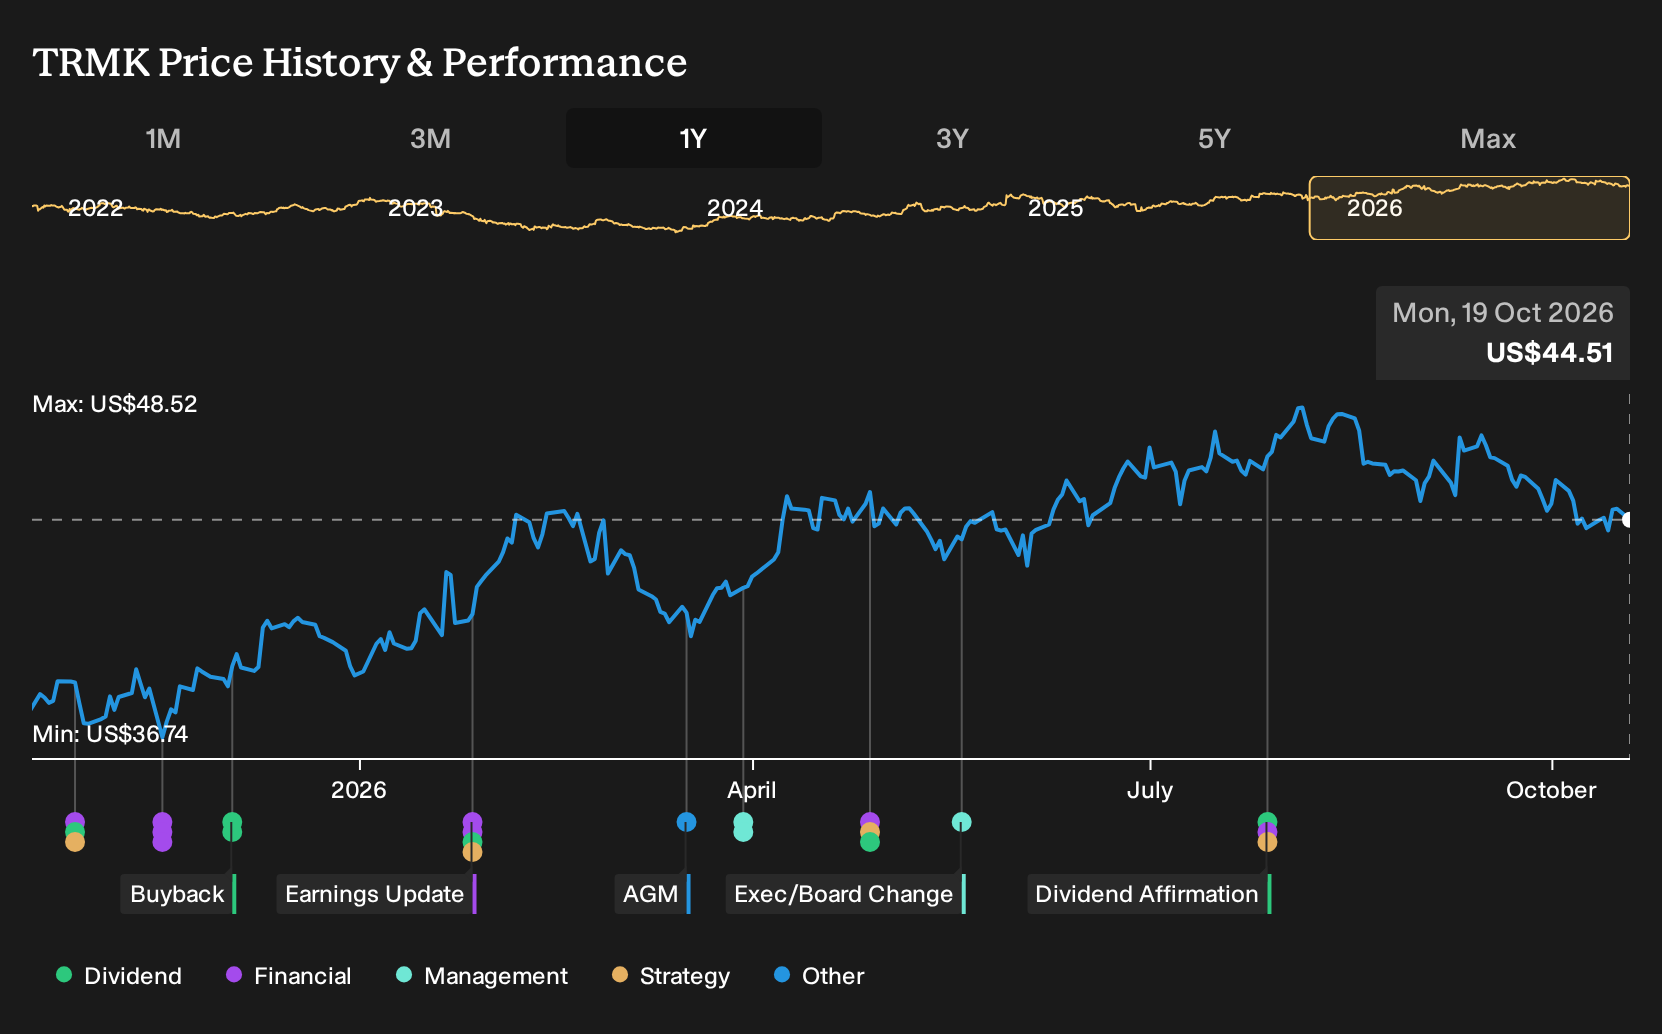
- Trustmark is scheduled to release its quarterly results for the period ended September 2026 on October 27, with Wall Street consensus pointing to higher revenue and earnings compared with the prior year.
- The bank currently offers a 2.25% dividend yield with a 26% payout ratio, which leaves room for management to support dividends using future earnings if conditions allow.
- Next, the focus shifts to how Trustmark’s upcoming earnings release, including its dividend profile, could reshape the existing investment narrative.
Compare Trustmark’s setup ahead of earnings with a curated 35 high quality undervalued stocks that also combine income potential with room for the underlying business to support payouts through future profits.
Trustmark Investment Narrative Recap
To own Trustmark, you need to believe the Gulf South franchise can keep turning steady C&I utilization, core deposits and credit quality into resilient earnings, even if sentiment swings around quarterly headlines. The upcoming September quarter update is important for fresh proof on margins, deposit costs and loan demand, but it does not rewrite the long term thesis on its own.
The more immediate swing factor is whether funding costs and credit losses stay in check while the FIS system conversion and expense work show through in efficiency. The biggest near term risk remains regional concentration. If project activity in Trustmark’s markets cools, loan growth and fee income could soften and slow progress.
The earnings preview around the October 27 release is the clearest near term marker. Wall Street expects higher revenue and profit versus a year ago, yet the Most Accurate Estimate sitting below the broader consensus hints at some recent caution on Trustmark’s near term earnings power.
For you, that setup makes this report less about hitting a single EPS figure and more about the quality of the run rate. Signs that net interest margin, deposit growth and credit metrics are holding near prior ranges would support the existing dividend profile. Softer trends in loan utilization or fee businesses would keep the operational risks in sharper focus.
Trustmark's current analyst story points to revenue of US$1.0b and earnings of US$252.1m by 2029, based on forecast annual top line growth of 7.4% and profit projections that move from US$234.3m of earnings today to the 2029 consensus, which is an increase of about US$17.8m.
Uncover why Trustmark's fair value indicates a 13% potential upside to its current price before the discount narrows.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Trustmark research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trustmark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trustmark's overall financial health at a glance.
Looking for more investment ideas beyond Trustmark?
If Trustmark is just one piece of your watchlist, it can help to scan a wider field of companies that share some of the qualities you care about, whether that is value, stability or future income potential.
- For investors who want quality at a reasonable entry point, review a curated set of companies trading at attractive valuations through the 35 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you, focus on businesses with stronger balance sheets and resilient fundamentals by using the list of solid balance sheet and fundamentals (25 results).
- Those hunting for opportunities that the market may not be focusing on yet can scan a carefully filtered pool of less-followed contenders via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com