
What Ultra Clean Holdings Stock Sector Rally Means For Shareholders
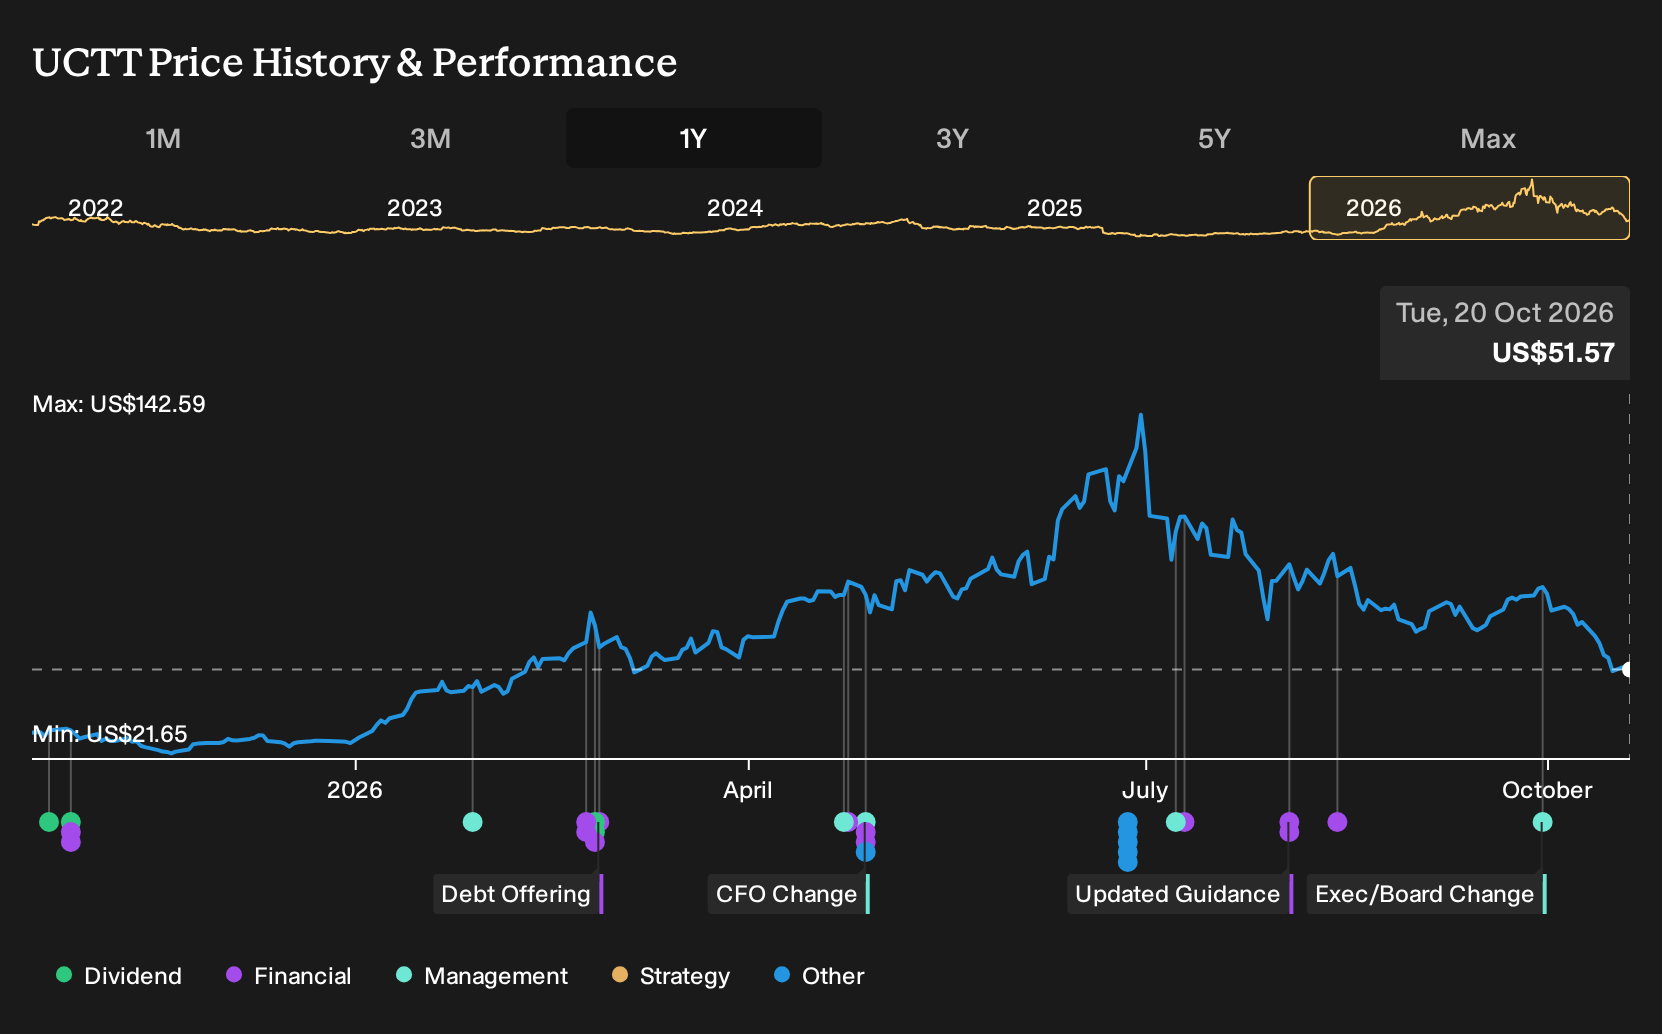
- Ultra Clean Holdings has recently moved in line with a broad upswing in semiconductor equipment stocks, reflecting sector wide buying interest rather than company specific headlines.
- The reaction highlights how Ultra Clean Holdings, with its focus on subsystems and services for chipmakers, remains tightly linked to industry wide capital expenditure expectations.
- We will now look at how this sector driven momentum in Ultra Clean Holdings could influence the existing investment narrative around demand.
Ultra Clean Holdings Investment Narrative Recap
To own Ultra Clean Holdings, you need to believe that wafer fab capital spending and AI related chip investment support steady demand for subsystems, while the firm’s cost cuts and vertical integration gradually lift profitability. The recent sector driven rally does not materially change that fundamental setup. The near term swing factor remains how quickly orders ramp toward the previously targeted capacity.
The biggest operational risk is that industry demand stays soft, leaving Ultra Clean Holdings running well below its earlier scale assumptions and limiting operating leverage. Customer concentration and tariff related friction sit close behind, especially with interest costs currently not well covered by earnings.
With no fresh company specific announcements tied to this move, the most relevant context is management’s effort to align the operation for future volume. New product qualifications and business wins at the Czech facility are flagged as incremental revenue drivers from Q4. This connects directly to the sector optimism that just lifted the stock.
If those wins translate into sustained orders from major equipment and fab customers, they could help fill underused capacity and support the cost reduction program already underway. Execution risk is real, especially given prior goodwill impairment and ongoing supply chain and tariff headwinds. The key watchpoint is whether that Czech ramp and broader Services and Fluid Solutions integration show up consistently in reported sales and margins.
Ultra Clean Holdings Forecast Setup And Analyst Expectations
Ultra Clean Holdings' narrative projects US$4.5b revenue and US$297.8m earnings by 2029. This aligns with analysts assuming 26.9% yearly revenue growth and an earnings swing of roughly US$321m, from a loss of US$23.4m today to that 2029 consensus figure.
Uncover why Ultra Clean Holdings' fair value indicates a 166% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Ultra Clean Holdings, the key alternate angle is margin risk. The most cautious analysts were only penciling in US$4.1b revenue and US$207.1m earnings by 2029, well below the consensus path. That more pessimistic story may or may not survive this sector wide surge in interest. Treat it instead as a prompt to compare several competing views before deciding how the latest move might shift your own expectations.
Explore 3 other Ultra Clean Holdings fair value estimates, including one that suggests as much as 76% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ultra Clean Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ultra Clean Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ultra Clean Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ultra Clean Holdings?
If the recent move in Ultra Clean Holdings has sharpened your interest in where capital might flow next, it can help to scan a broader set of opportunities with similar or contrasting traits.
- If you care most about resilience and capital protection, start with a set of 32 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering equity upside.
- If value is your priority, compare Ultra Clean Holdings with a focused pool of 35 high quality undervalued stocks that pair solid fundamentals with what our models see as discounted prices.
- If strong finances matter most to you, broaden your watchlist with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying heavily on new capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com