
McDonald's (MCD) Refranchising Push Leaves Valuation Questions Ahead Of Q3
McDonald's (MCD) is back in focus after management reiterated a plan to push the restaurant base toward roughly 98% franchised by 2028 while trimming general and administrative costs.
The share price has started to bounce in the very short term, with a 1-day share price return of 1.59% and a 7-day share price return of 4.54%, even though the 90-day share price return is down 6.47% and the year to date share price return is down 18.71%. Over a longer stretch, total shareholder return has been modest, with a 3-year total shareholder return of 3.02% and a 5-year total shareholder return of 17.15%. This signals that recent selling pressure has been concentrated in 2026 rather than across the whole period.
Compare McDonald's refranchising story with other businesses where earnings quality matters most by scanning our hand picked 35 high quality undervalued stocks that pair solid cash flows with balance sheet strength.
McDonald's has dropped sharply this year even as management leans harder into a higher franchise mix and cost cuts. Is this rebound a reset toward business fundamentals, or just sentiment flickering ahead of Q3, and what does the current price imply?
Most Popular Narrative: 5.5% Overvalued
Compared with the last close at $246.52, the most followed narrative on McDonald's pegs fair value lower at $233.67. This frames today’s rebound as a move inside a valuation band rather than a clean bargain.
So, in resume, I forecast that McDonald's will expand its margins through an increase in efficiency of its operations (probably with the aid of AI) but will also see its revenue growth slow down, probably below the economy growth rate given the maturity of the business and the decrease of consumer spending.
See why 54 investors see McDonald's as 5% overvalued.
Result: Fair Value of $233.67 (OVERVALUED)
Still, the McDonald's thesis could be knocked off course if consumer health trends drag traffic harder than expected, or if franchised operators push back on higher tech and reinvestment demands.
Find out about the key risks to this McDonald's narrative.
Another View: McDonald's Through The P/E Lens
That community valuation points to McDonald's trading about 5.5% above a fair value of $233.67. The market is sending a different signal when you look at the P/E ratio.
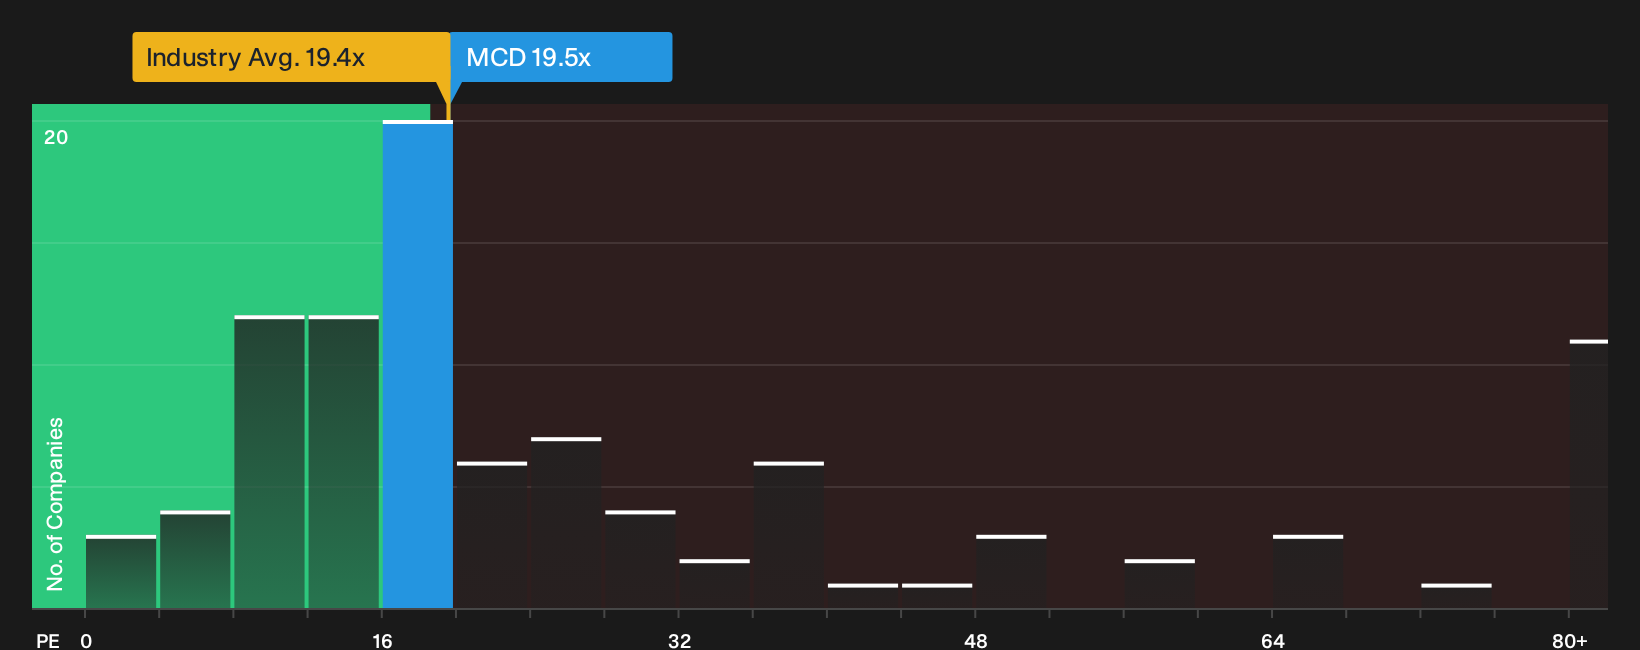
The stock changes hands at 19.5x earnings. The wider peer group averages 50.3x, while the fair ratio for McDonald's sits at 24.4x.
That gap cuts both ways. A lower multiple than peers can reduce downside if sentiment weakens. At the same time, a discount to the fair ratio hints the market may be pricing in slower growth or higher risk. Which story do you think is closer to reality for this restaurant giant?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around McDonald's feels familiar, treat it as your cue to move fast. Test the data yourself so you are not just following the crowd, then weigh up its 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond McDonald's?
Do not stop your research with McDonald's. Broaden your watchlist now with targeted stock ideas so you are not relying on a single story.
- Target resilient income by hunting for companies that combine higher yields with financial strength through our 8 dividend fortresses.
- Spot potential value early by scanning a curated 20 high quality undiscovered gems that many investors may be overlooking today.
- Dial down portfolio risk by filtering for a 32 resilient stocks with low risk scores that can help anchor your returns when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com