
Learn Why The Bull Case For Terumo Stock Could Change Following Supply Deal Termination
- Terumo Corporation disclosed that it mutually terminated a source plasma collection supply agreement with CSL Plasma, reassessed related Blood and Cell Technologies projections, and revised fiscal 2027 guidance to revenue of ¥1,229,500 million, operating profit of ¥160,000 million, and profit attributable to owners of parent of ¥120,000 million.
- The roughly US$610 million, or about ¥97.5 billion, projected financial impact from impairments, transition losses, and restructuring costs highlights how concentrated exposure to a single plasma collection partner had become a pressure point for Terumo's Blood and Cell Technologies operations.
- This raises questions about how Terumo's investment narrative is affected when earnings guidance is reset after terminating the CSL Plasma supply agreement.
Terumo Investment Narrative Recap
To own Terumo, you need to be comfortable with a broad medical devices group where cardiovascular and medical care solutions carry the investment story, while Blood and Cell Technologies is now a repair job. The reset to fiscal 2027 guidance concentrates attention on how quickly the plasma related hit stabilises and how resilient the remaining segments look.
The near term swing factor is execution on tariffs, China pricing, and mix into higher margin consumables while restructuring costs run through the P&L. The biggest risk right now is that pressure from procurement and volume based procurement in China combines with restructuring noise to squeeze margins more than expected.
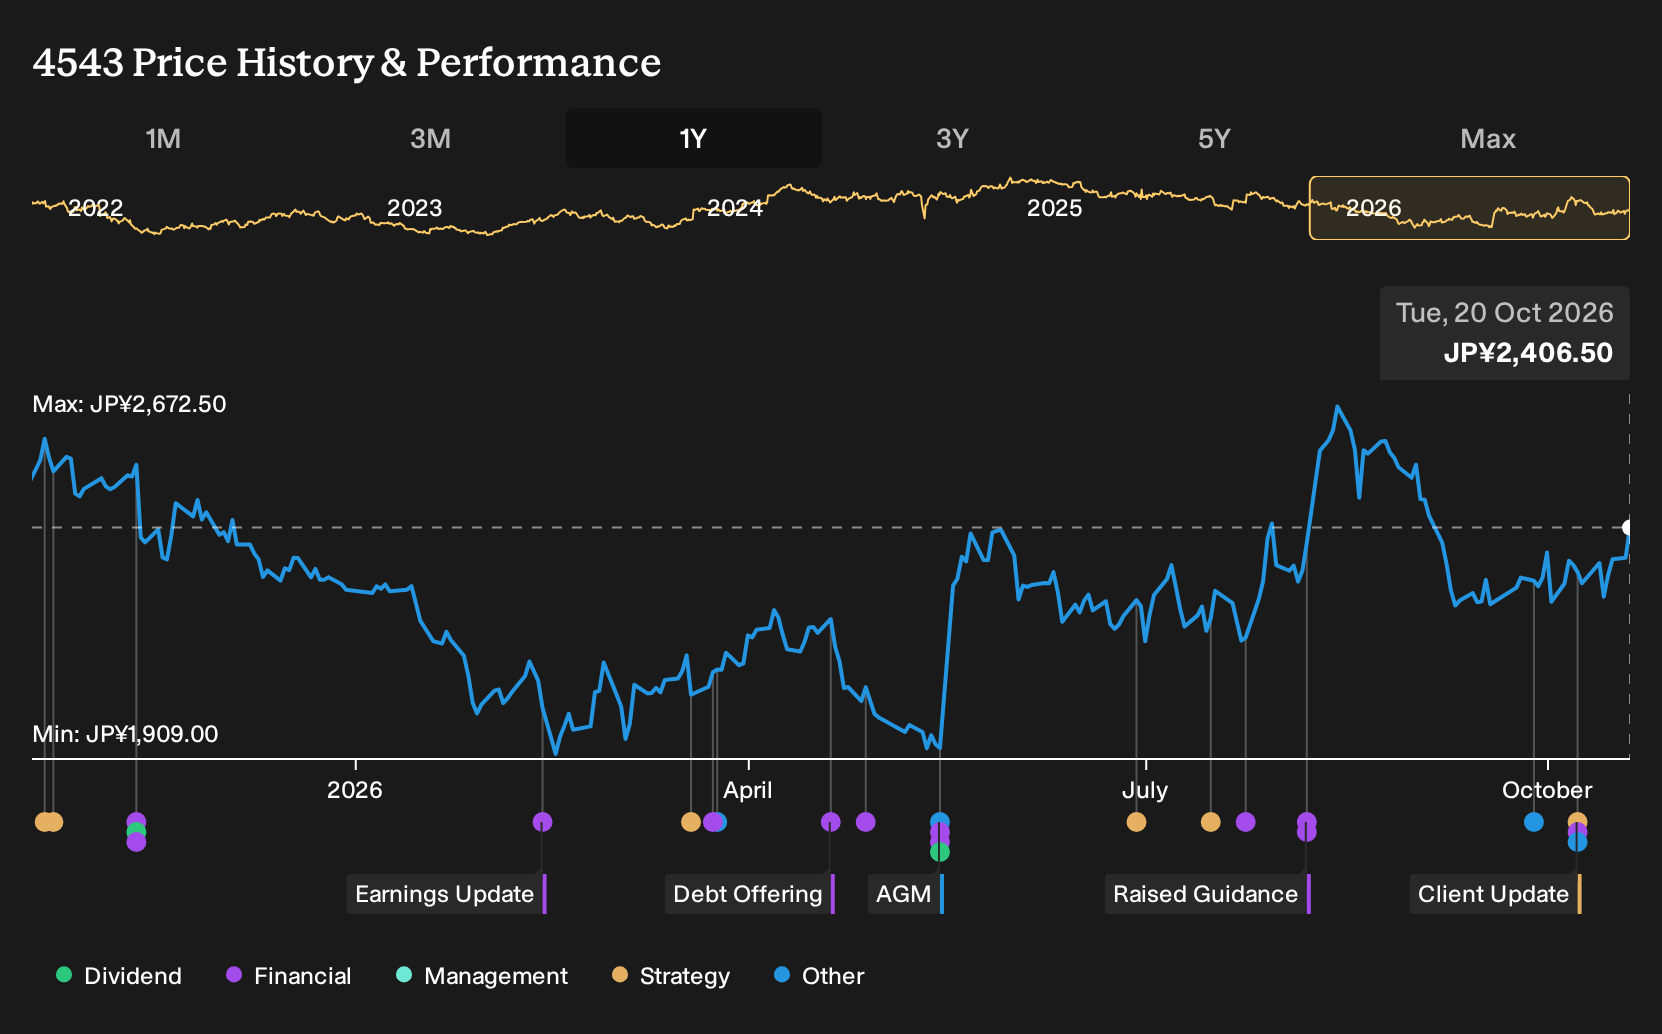
The most relevant update is Terumo’s decision on 8 October 2026 to mutually terminate the CSL Plasma supply agreement and cut fiscal 2027 guidance. Management now projects revenue of ¥1,229,500 million, operating profit of ¥160,000 million, and profit attributable to owners of parent of ¥120,000 million, versus much higher earlier guidance.
That move goes together with an estimated US$610 million, or about ¥97.5 billion, financial impact from asset impairments, transition losses, and restructuring. For you as a shareholder, the key watchpoints are how fast Terumo BCT capacity is retooled or repurposed, how well cash costs are contained, and whether core cardiovascular and China driven catalysts stay intact through the clean up period.
Terumo's current analyst narrative ties together a forecast revenue level of ¥1,443.8 billion and earnings of ¥218.9 billion by 2029, indicating 6.8% yearly revenue growth and an earnings increase of about ¥54.4 billion from the current ¥164.5 billion base.
Uncover why Terumo's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might focus on tariffs and China pricing, yet the lowest Terumo analysts were far more worried about blood and plasma profitability. They were only pencilling in revenue of ¥1,384.3 billion and earnings of ¥194.8 billion by 2029. That is a leaner path, and today’s CSL Plasma news could push those views even lower or trigger fresh revisions.
Explore another Terumo fair value estimate, including one that suggests it could be worth just ¥3,075!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Terumo research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Terumo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terumo's overall financial health at a glance.
Looking For More Ideas Beyond Terumo?
If Terumo's reset guidance has you reassessing your portfolio, broadening your watchlist with other financially solid businesses can give you better context for risk and return.
- For investors who want quality and value in the same place, scan a curated pool of 13 high quality undervalued stocks that pair fundamentals with discounted pricing.
- If capital preservation is a priority, focus on resilience first by filtering for 21 resilient stocks with low risk scores that show stronger risk profiles on key financial checks.
- For a more balanced core holding list, anchor your research around companies with sturdier finances using our list of solid balance sheet and fundamentals (22 results) to see which ones pass tougher balance sheet filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com