
3 Stocks Retail Investors Are Watching For Tariff Refund And Trade Compliance Exposure
Trade rules are suddenly in flux, and that puts a spotlight on the quiet specialists that help importers handle tariffs, refunds and compliance when policies change overnight. With U.S. and Canadian duties now tied up in court and potential refund money on the line, investors face a rare mix of risk and optionality. This article examines three stocks exposed to that news and explains why their business models matter in the current environment.
The stocks covered below are just a starting sample, and the full screen surfaced 21 more U.S. and Canadian trade-compliance and tariff-refund service providers with equally compelling narratives that are not included in this article. To go straight to the source, analyze, compare, and identify your highest conviction ideas directly in the Trade-Compliance and Tariff-Refund Service Providers screener.
RXO (RXO)
Overview: RXO runs an asset-light truck brokerage and managed transportation network, coordinating cross-border freight, customs-linked documentation and last-mile logistics across multiple regions.
Operations: RXO generates about $6.1b from transportation trucking services, with roughly $5.7b in the U.S. and $0.4b from international markets.
Market Cap: US$4.7b
RXO matters for this trade-compliance themed screen because its freight brokerage network sits where tariffs, documentation and cross-border trucking all meet for shippers that need clean paperwork when rules keep shifting.
"RXO's investment in AI-powered, proprietary digital freight-matching technology is reported to be boosting employee productivity (up 45% in two years) and contributing to operating leverage. As digital tools see wider use in logistics, this technology focus is a key factor for the company, while current valuation levels are a notable feature of the stock."
The real swing factor is how one evolving layer of tariff and cross-border policy risk filters into pricing and long-term freight demand.
That pricing risk is exactly what makes the full narrative for RXO so useful for judging whether RXO's tariff exposure is masking resilience or capping its next leg of momentum.

TrueBlue (TBI)
Overview: TrueBlue provides technology enabled staffing, on site workforce management, and recruitment process outsourcing that helps employers handle surging logistics and compliance workloads.
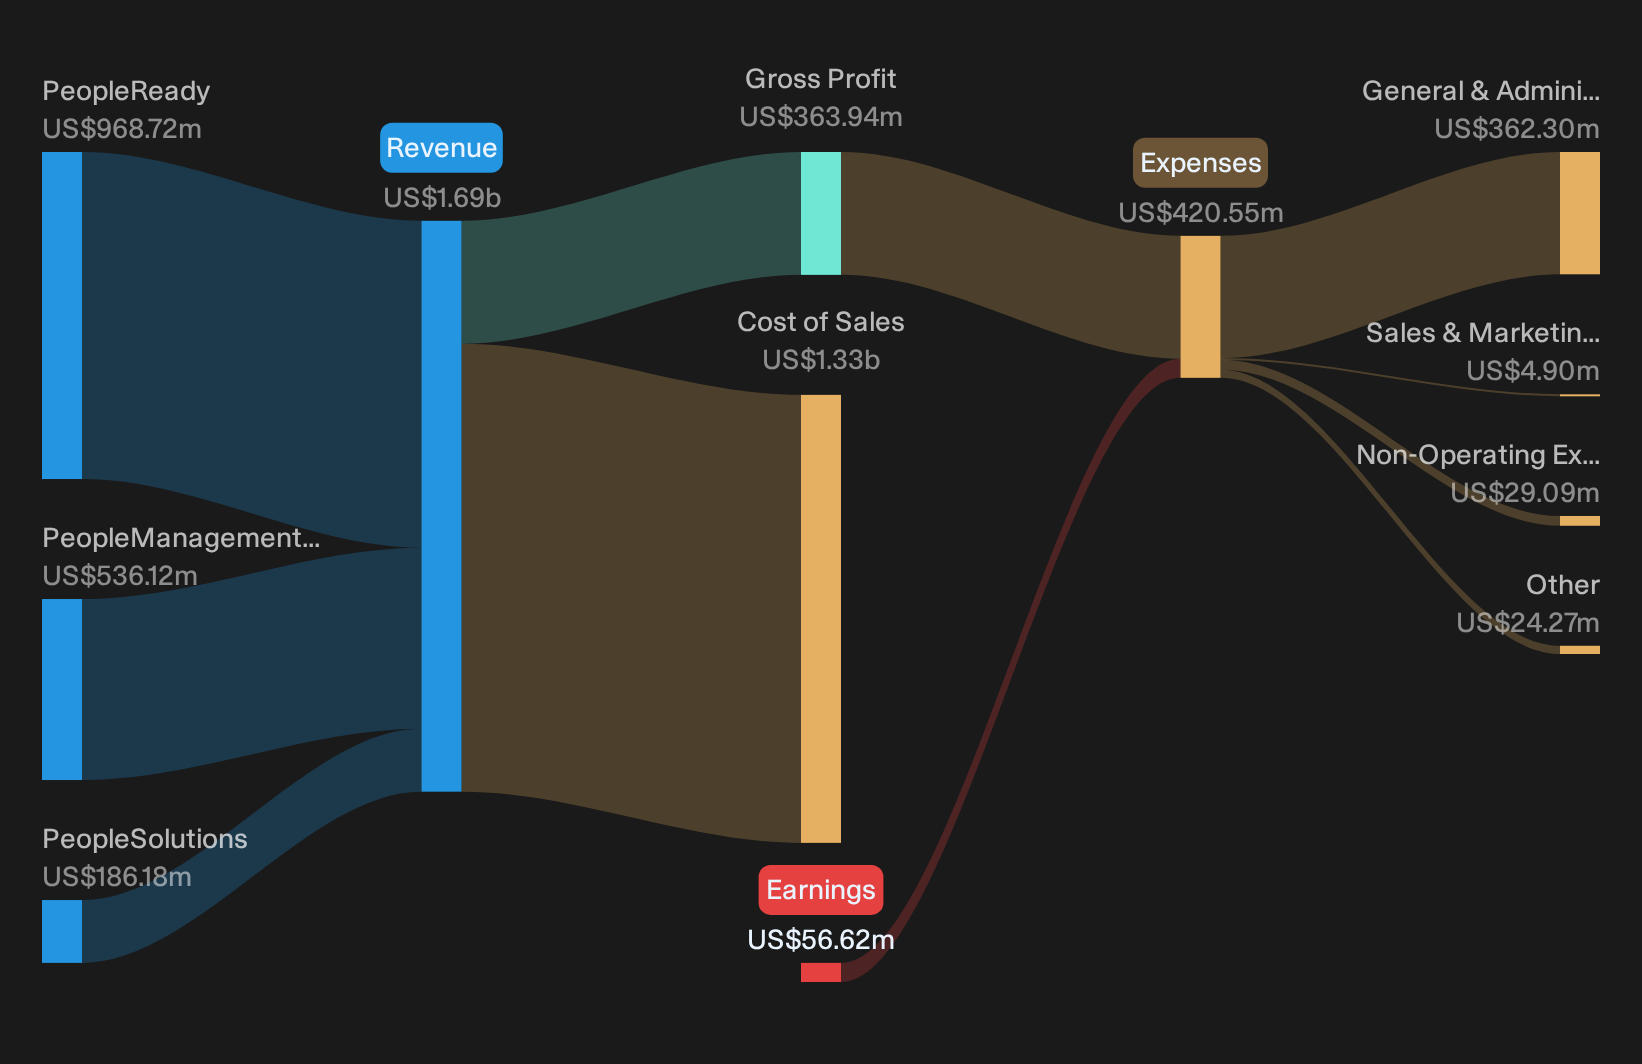
Operations: TrueBlue generates about $969 million from PeopleReady, $536 million from PeopleManagement, and $186 million from PeopleSolutions.
Market Cap: US$248 million
TrueBlue matters in this tariff focused screen because its contingent staffing and driver solutions can flex with spikes in customs, warehousing, and compliance heavy work when trade rules change quickly.
"Persistent structural labor shortages in skilled trades and commercial drivers, combined with TrueBlue’s reported fifth consecutive quarter of double digit driver growth, may position the company to gain share and potentially lift consolidated revenue and operating margins if transportation volumes recover."
What happens to TrueBlue’s earnings power will depend heavily on how one quiet shift in client hiring behavior plays out.
That quiet shift is exactly where the full narrative for TrueBlue shows whether TrueBlue’s labor engine is accelerating, stalling, or masking a far bigger rehiring cycle.
Hackett Group (HCKT)
Overview: Hackett Group provides GenAI enabled consulting, benchmarking and platforms that help large enterprises redesign finance, supply chain and compliance heavy operations.
Operations: Hackett Group generates about US$153 million from Global S&BT, US$69 million from SAP Solutions and US$61 million from Oracle Solutions.
Market Cap: US$281 million
Hackett Group earns a place in this trade compliance focused screen because its process redesign and GenAI platforms touch the supply chain, where tariff driven rule changes often force companies to rethink how they manage documentation, controls and cross border workflows.
"Although the SAP Solutions segment is currently benefiting from S/4HANA cloud migration activity and software related sales, any moderation in migration intensity or increased competition from larger integrators could reduce project volume and pricing power. This would have a direct impact on total company revenue and gross margin."
What ultimately matters for Hackett Group is how one slow building shift in client priorities shapes demand for its AI centric transformation work.
That slow shift in priorities is exactly what the full narrative for Hackett Group unpacks. It separates stalled consulting demand from an accelerating, tariff linked AI opportunity that the headline numbers do not show.

Curious About High Conviction Alternatives
Fresh opportunities often move from quiet to crowded quickly. Spot potential breakout stories with real momentum while they are still under the radar for now, then act now.
- Chase early upside by scanning curated 11 elite penny stocks with strong financials that pair smaller size with stronger balance sheets before the crowd increases demand.
- Target growth with substance by reviewing 38 profitable AI stocks that aren't just burning cash that already produce real earnings instead of just burning cash on promises and hype.
- Lock in potential income streams by assessing a hand picked group of 8 dividend fortresses before yields change as more investors pursue the same ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com