
PTC (PTC) Stock Looks Cheap Relative To Current Earnings
PTC Inc. has seen its share price move around in recent years, and with the stock last closing at US$193.35 the question now is whether that level can be explained by the earnings the business generates. For anyone weighing a position in PTC, the key issue is how much of the current price is tied to what the company already earns versus what the market expects it to earn down the line.
- PTC has delivered a 51.5% total return over the past 5 years, which puts real pressure on the current earnings multiple to carry that track record forward.
- The renewed Servigistics relationship with the U.S. Air Force under the ESCAPE program may support assumptions about future software demand and the durability of earnings tied to defense supply chain projects.
- The analysts covering PTC have run their own numbers. See what analysts think PTC's shares could be worth.
The issue now is whether the earnings that PTC produces today, and what analysts expect those profits to look like over time, are enough to justify the stock sitting near US$193.35.
If you are considering whether PTC's US$193.35 share price aligns with its earnings profile, it can be useful to compare this question across 35 high quality undervalued stocks.
Is PTC a Bargain on Earnings?
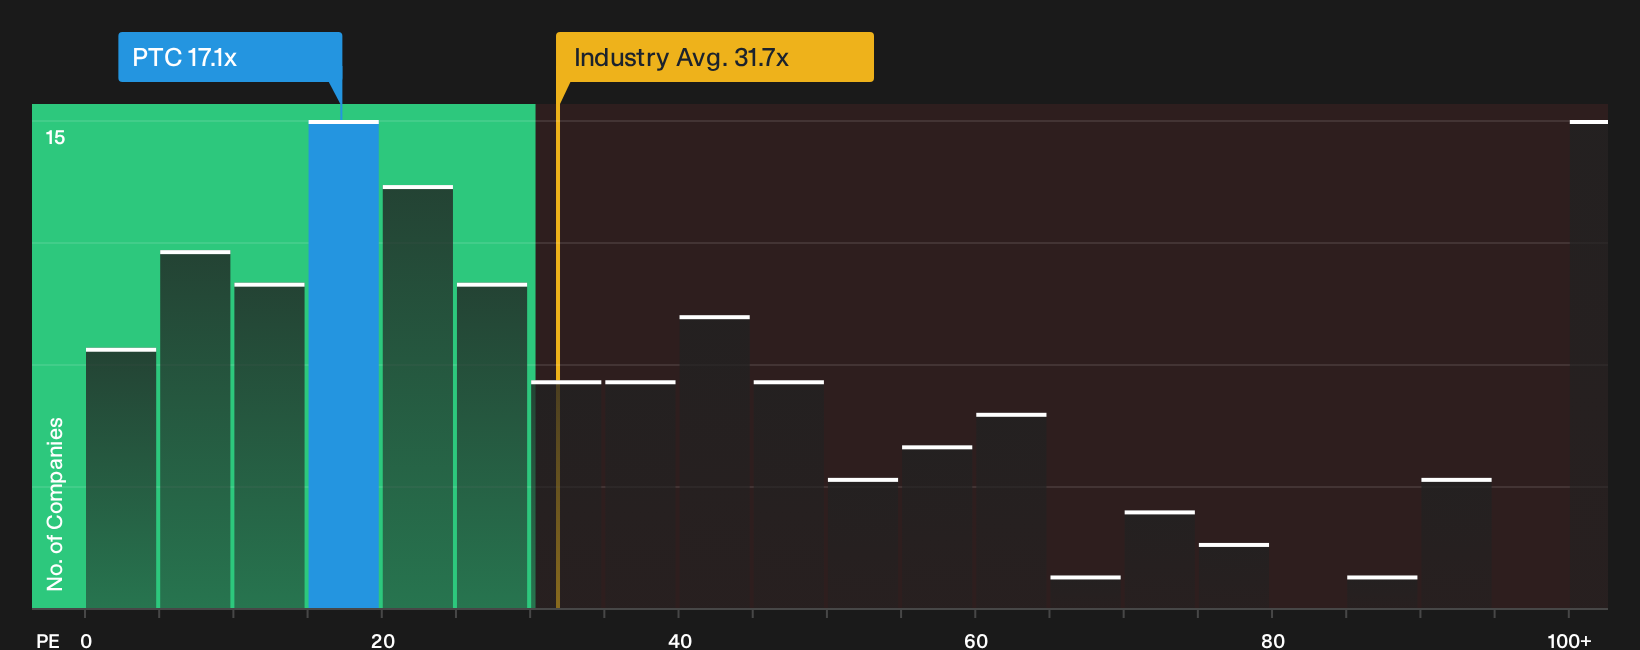
The P/E multiple suits PTC because earnings remain the cleanest link between what the business produces and what shareholders pay for each dollar of profit. On that score, PTC trades on a P/E of 17.1x, which sits below the broader software sector on 31.7x and well under the peer average near 50.9x. For a reader, that means the stock is priced at a lower earnings tag than many listed software operators, even though it competes in the same industry group.
Because the fair P/E that blends PTC's growth profile, margins, size and risk comes out above the current 17.1x level, the shares screen as undervalued on this metric. Despite the agreed US$205 per share sale to Schneider Electric and the legal scrutiny around that deal, the existing P/E still lines up below what this framework suggests for a business with PTC's characteristics. Explore the numbers behind PTC's P/E valuation.
The PTC Narrative: What Would Justify Today's Price?
PTC's valuation puzzle only really comes into focus once you spell out the future that would need to unfold for today’s price to look either conservative or stretched. This is exactly what Simply Wall St Narratives on the Community page attempt to do by linking the current multiple to explicit paths for growth, margins and earnings. Where a ratio or model gives a single outcome, those storylines unpack the assumptions behind it so you can watch, over time, whether reality keeps matching the script.
One of the top community narratives on PTC: 20% overvalued
"Pervasive adoption of open-source software and community-driven development is putting greater pressure on proprietary vendors like PTC, eroding pricing power…"
Discover why this Narrative puts PTC at 20% overvalued.
One more PTC question before you move on
Current multiples only tell you what the market pays today. The forward picture that professional analysts map out for PTC over the next few years can either reinforce or challenge that view. Explore where analysts expect PTC to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com