
How Investors Are Reacting To CIBC (TSX:CM) $1 Billion Capital Notes Sale
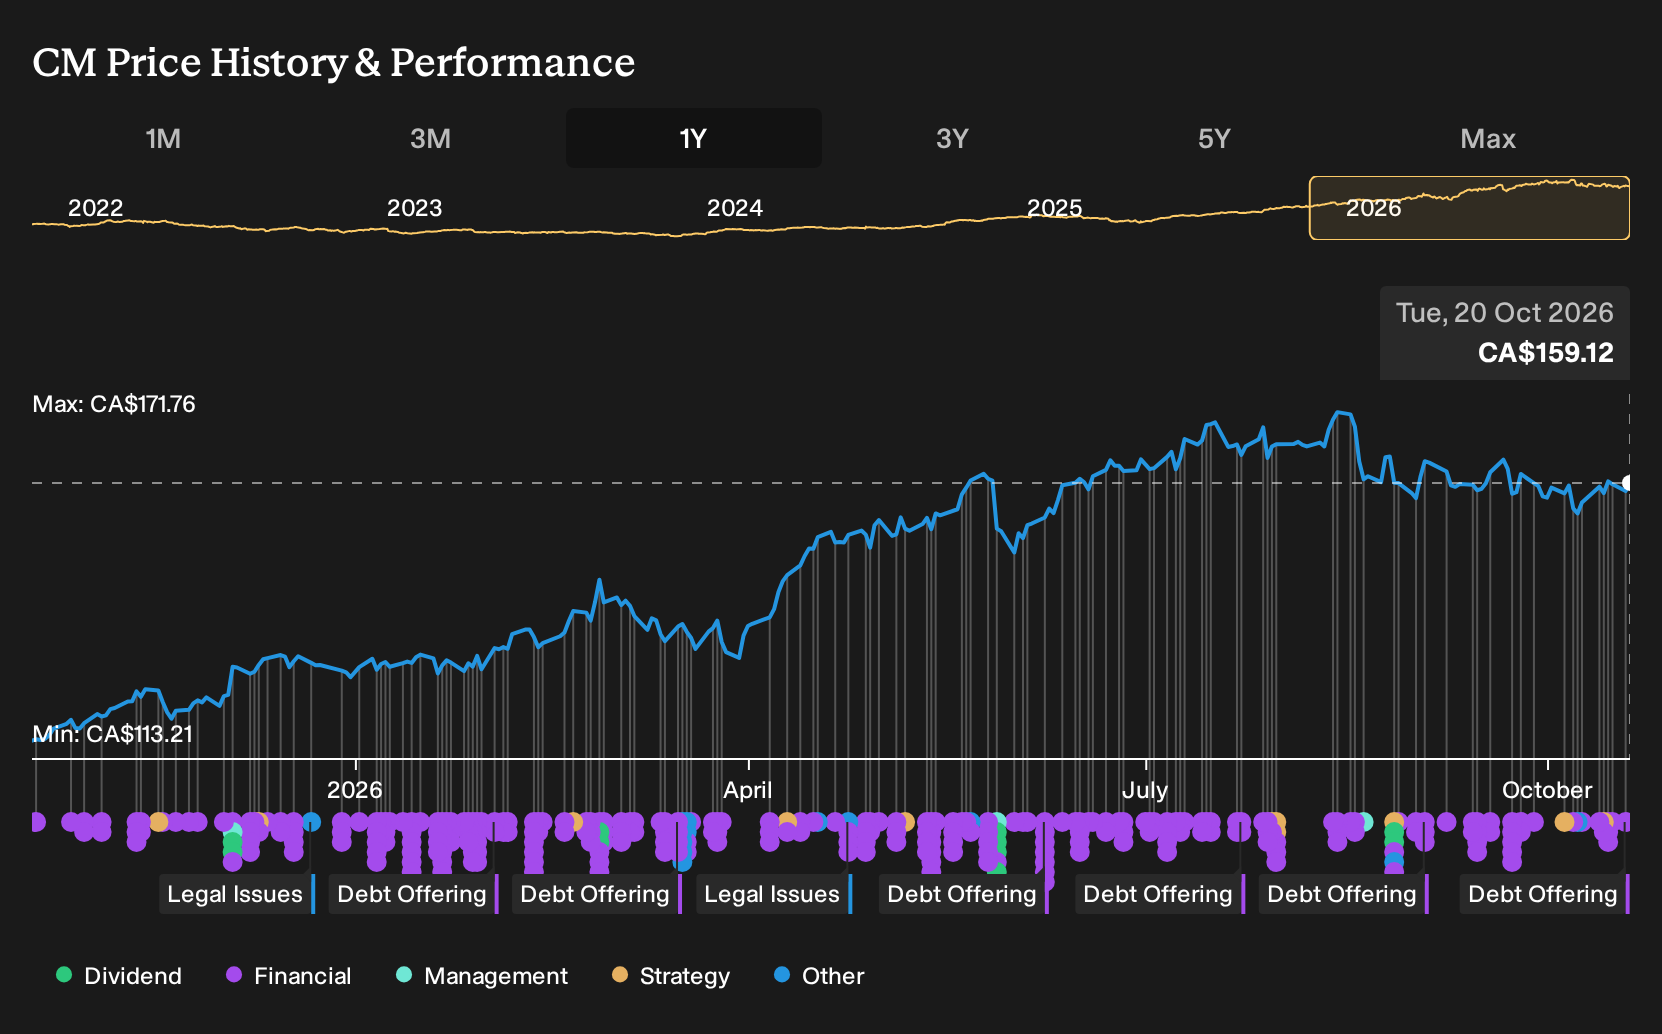
- Canadian Imperial Bank of Commerce recently completed and announced several fixed income offerings, including CAD 1b fixed to floating subordinated notes due 2086 and a domestic public issue of 6.631% Limited Recourse Capital Notes Series 11 in the amount of CAD 1b.
- This wave of long dated and senior fixed income issuance, spanning callable senior notes through to Limited Recourse Capital Notes, highlights how CIBC is actively reshaping its funding mix and capital structure using both traditional bonds and newer regulatory capital instruments.
- We will look at how CIBC's investment narrative intersects with this CAD 1b Limited Recourse Capital Notes issue and broader funding shift.
Canadian Imperial Bank of Commerce Investment Narrative Recap
To own Canadian Imperial Bank of Commerce, you need to believe that a traditional, diversified bank can keep growing fee based wealth, higher margin everyday banking and cards, and capital markets while keeping Canadian credit issues contained. The near term swing factor still sits in credit quality in Canadian mortgages and consumer lending, where any broad weakening in borrower health would pressure net interest income and earnings.
The recent wave of senior and subordinated bond issues, including the very long dated fixed to floating notes, mainly affects funding and capital rather than day to day operations. It looks incremental to the near term earnings story. The bigger operational risk remains a softer or prolonged slowdown in Canadian housing that lifts delinquencies and write offs.
The Limited Recourse Capital Notes Series 11 at 6.631% are the clearest link between this funding activity and CIBC’s equity story. These instruments sit in the regulatory capital stack and give the bank another tool to manage its common equity tier 1 ratio while still supporting lending, wealth and capital markets ambitions.
For you as a shareholder, these capital moves touch the same catalysts analysts focus on, such as capital strength, share count flexibility and capacity to absorb credit losses without forcing abrupt balance sheet adjustments. The key watchpoint is execution. CIBC is layering on multiple maturities and structures, so the real test will be how efficiently it uses this mix while credit conditions and funding costs evolve.
Canadian Imperial Bank of Commerce's current earnings sit at CA$9.7b, with analysts forecasting CA$12.4b of earnings and CA$36.9b of revenue by 2029. That outlook implies 7.2% yearly revenue growth and an earnings increase of CA$2.7b from current levels.
Uncover why Canadian Imperial Bank of Commerce's fair value indicates a 7% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Fair value views on Canadian Imperial Bank of Commerce from 2 Simply Wall St Community members already span a tight but meaningful band from CA$170.50 to CA$228.63 per share, which points to different expectations around risk, reward and timing. Set that against mortgage credit concerns and bond funded balance sheet flexibility, and you can see why opinions will vary. Use this spread as a prompt to compare several alternative viewpoints before deciding how CIBC fits your own thesis.
Explore another Canadian Imperial Bank of Commerce fair value estimate, including one that suggests up to 44% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Imperial Bank of Commerce research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Canadian Imperial Bank of Commerce. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Imperial Bank of Commerce's overall financial health at a glance.
Looking for more investment ideas beyond Canadian Imperial Bank of Commerce?
Once you have a handle on Canadian Imperial Bank of Commerce, it can help to widen the lens and compare it with other businesses that share similar qualities or offer very different risk and income profiles.
- For investors who put capital preservation first and want steadier balance sheets, consider starting with our 8 resilient stocks with low risk scores to see which companies line up with your risk tolerance.
- If value is your priority and you focus on quality at a reasonable price, review the 4 high quality undervalued stocks to spot candidates that may trade below what their fundamentals suggest.
- Those who care most about portfolio income can scan the 3 dividend fortresses and compare yields, payout patterns and business profiles side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com