
Bank of Nova Scotia (TSX:BNS) Raises CA$3.0b, Is The Stock Still A Bargain?
Bank of Nova Scotia (TSX:BNS) just raised about CA$3.0b through a series of fixed income offerings, giving investors a fresh view on its credit profile and funding options for international growth.
At a share price of CA$129.78, Bank of Nova Scotia has carried solid momentum, with a 90 day share price return of 5.2% and a year to date share price gain of 26.74%. Total shareholder return over 3 years of 171.05% and 5 years of 106.07% points to a long run story that recent debt issuance and Pacific Alliance expansion are feeding rather than reversing.
Spot similar dividend heavyweights and international lenders showing strong momentum by scanning our curated list of 3 dividend fortressesBank of Nova Scotia now has fresh capital in hand, strong international earnings power, and a long dividend track record. The real tension is whether the current share price fairly reflects that mix.
Most Popular Narrative: 2% Undervalued
On the most followed view, Bank of Nova Scotia trades a little below an estimated fair value of about CA$132.86, compared with the current CA$129.78 price. This puts the focus squarely on whether its international and digital engines can keep doing the heavy lifting that valuation assumes.
Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver. International Banking revenue and loan growth in these regions and ROE above 16% point to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships.
See why 193 investors see Bank of Nova Scotia as 2% undervalued.
Result: Fair Value of CA$132.86 (UNDERVALUED)
Still, the Bank of Nova Scotia story can change quickly if Latin American credit conditions worsen, or if Canadian consumer strain keeps loan losses higher for longer.
Find out about the key risks to this Bank of Nova Scotia narrative.
Another View: Bank of Nova Scotia Through P/E Lenses
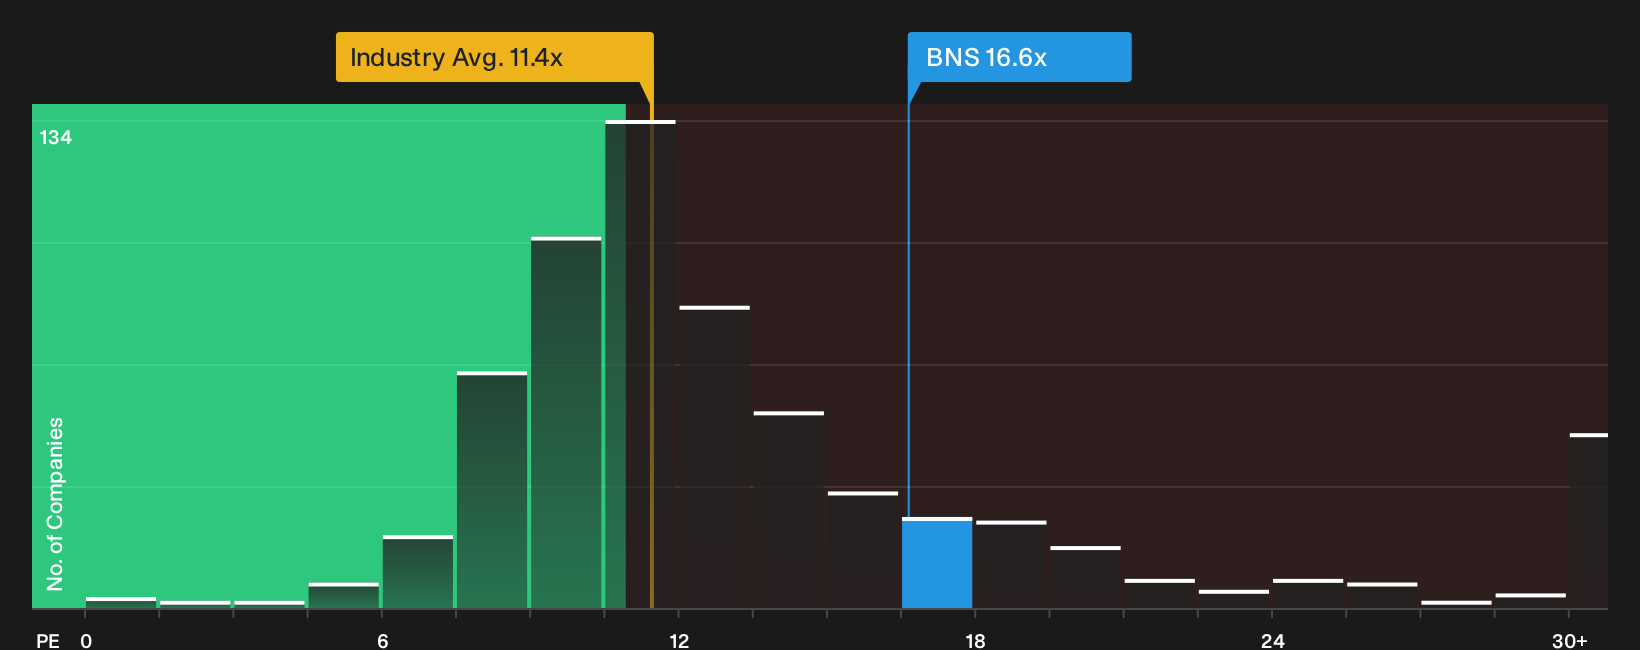
There is a different read on Bank of Nova Scotia once the focus shifts from fair value estimates to the P/E ratio. At 16.6x earnings, the stock trades richer than the North American banks group at 11.4x, yet slightly below a 17.6x fair ratio and under the 17.1x peer average. That mix points to some valuation risk, but also suggests the market could move closer to the fair ratio if confidence builds. This leaves the question of how much of the international and digital story is already priced in.
See what the numbers say about this price in our valuation breakdown, then compare it with other banks using the same yardstick to test how comfortable you are with that P/E gap See what the numbers say about this price — find out in our valuation breakdown.
Use the relative valuation chart to see how Bank of Nova Scotia stacks up against its sector on this single metric
Next Steps
Plenty of investors see upside in Bank of Nova Scotia, while others focus on the risk list and tread carefully. Use the full risk and reward breakdown to stress test your own thesis before sentiment moves on without you with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of Nova Scotia?
Bank of Nova Scotia might fit your thesis today, but your future returns will likely depend on the breadth of opportunities you keep on your radar.
- Target potential bargains early by scanning a focused set of 10 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Strengthen capital preservation by filtering for 8 resilient stocks with low risk scores that keep financial risk scores in check while still offering meaningful upside.
- Anchor your portfolio with quality by using a list of solid balance sheet and fundamentals (7 results) that highlights resilient businesses built on robust cash flows and debt profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com