
Southern First Bancshares (SFST) Stock Climbs On Strong Q3 Earnings Execution
Southern First Bancshares just put Q3 2026 on the tape with a clean story that clashes with the trading screen. The stock closed up about 3% on the day, yet the real driver was not hype. It was another quarter of solid earnings power, with basic EPS at about $1.30 and net income a little above $12 million.
The emotional charge in the move looks tied to one thing: investors are rewarding a bank that keeps expanding revenue while maintaining profitability, even though the valuation already carries a higher P/E than many peers.
Impressed by Southern First Bancshares earning power but uneasy about paying up for a richer P/E than many regional peers? Check out our shortlist of banks and financials with stronger balance sheets and reasonable valuations in the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$36.13m vs. US$30.28m (up about 19%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$12.23m vs. US$8.66m (up about 41%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.30 vs. US$1.08 (up about 20%)
- Cost to Income Ratio (Q3 2026 vs. Q3 2025): 56.8% vs. 66.2% (improved efficiency; lower cost share of revenue)
Prefer clean charts instead of squinting at raw tables and footnotes? See Southern First Bancshares’ full visual financial picture, including valuation context around its recent earnings, in our company report for Southern First Bancshares.
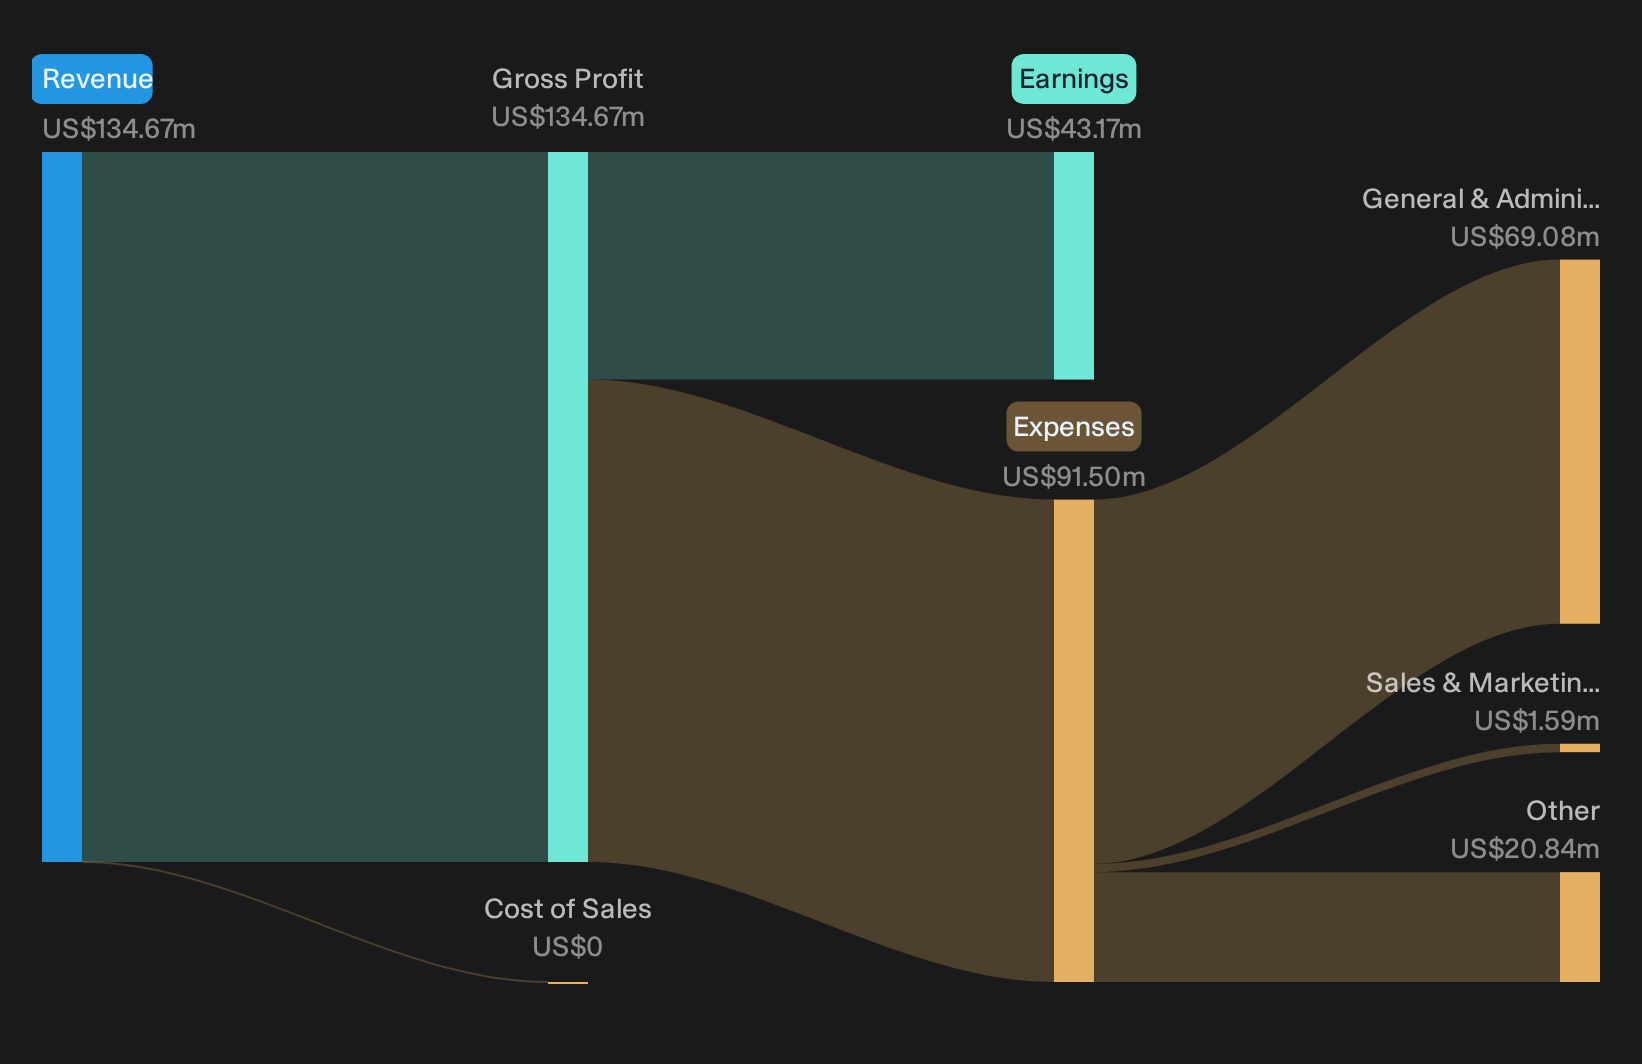
Southern First bullish signals meet the numbers
For anyone leaning optimistic on Southern First Bancshares, the latest quarter gives some backing. Revenue, net income and EPS all move in the same positive direction, and the cost to income ratio improves into the mid 50s. That lines up with the idea of a relationship bank turning growth in its Southeast footprint into stronger earnings power. Loan growth at 14% annualized and retail deposit growth at 18% annualized reinforce a story of healthy client demand rather than one off noise.
Southern First risks under a harsher light
Bears worry most about a concentrated regional lender leaning into commercial and construction credit. The quarter does not erase that exposure, yet asset quality indicators help frame those fears. Nonperforming assets sit at 0.30% of total assets and net charge offs are low, which points to contained credit stress for now. Funding concerns look less acute with solid retail deposit growth and better profitability metrics. The risk narrative still matters, but immediate cracks in the business model are not evident in these results.
After concentrated lending and recent insider selling, you might ask whether that is just surface noise. Review our risk analysis for Southern First Bancshares which shows 2 important warning signsHunt For Mispriced Earnings Power
Southern First Bancshares highlights how reported results and share price reactions can diverge. The real opportunity is in tracking stocks that could be undervalued before sentiment and pricing adjust.
- Company 1 - 26% below our estimate - targets high complexity circuit boards tied to AI hardware and defense programs.
- Company 2 - 49% below our estimate - leans on rapid app led store rollout to convert frequent low ticket orders into dense urban traffic.
- Company 3 - 42% below our estimate - scales a premium tea chain as health focused consumers trade up and deepen spending through a large membership base.
Those are three of them. See every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com