
Bloom Energy (BE) Could Be 42% Undervalued As AI Data Center Demand Builds
Bloom Energy (BE) is heading into earnings week with attention fixed on its role powering AI and cloud data centers, as large Oracle and Google projects highlight demand for its solid oxide fuel cell platforms.
Bloom Energy’s share price has pulled back sharply over the last month, with a 30-day share price return of down 16.18% and a 7-day move of down 15.49%, even though the year-to-date share price return of 125.61% and a very large 3-year total shareholder return suggest long-term momentum is still intact as investors reassess execution risk around large AI power projects and a premium P/E multiple ahead of earnings.
Scan how other AI infrastructure plays are reacting to the same earnings pressure by reviewing our hand-picked list of 55 AI infrastructure stocks alongside Bloom Energy.
Bloom Energy now looks like a powerful AI infrastructure story wrapped in a stock that just dropped hard. The real work is figuring out whether that combination is a bargain or still priced for perfection.
Most Popular Narrative: 42% Undervalued
Bloom Energy’s most widely followed narrative pegs fair value at $386.10 versus the last close of $222.65. This is a big gap that frames the current pullback as a valuation stress test rather than the end of the AI power story.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, international, other market segments, even personal or community power (where they started) are largely untapped.
Their proven, no supply chain risk, nearly flawless all hands execution (engineering, sales, services, customer sat) are described as good enough to see a long growth future.
See why 41 investors see Bloom Energy as 42% undervalued.
Result: Fair Value of $386.10 (UNDERVALUED)
Still, the solid AI power story around Bloom Energy can break if large data center projects stall or if profitability fails to keep pace with revenue expansion.
Find out about the key risks to this Bloom Energy narrative.
Another View: Bloom Energy Looks Expensive On Sales
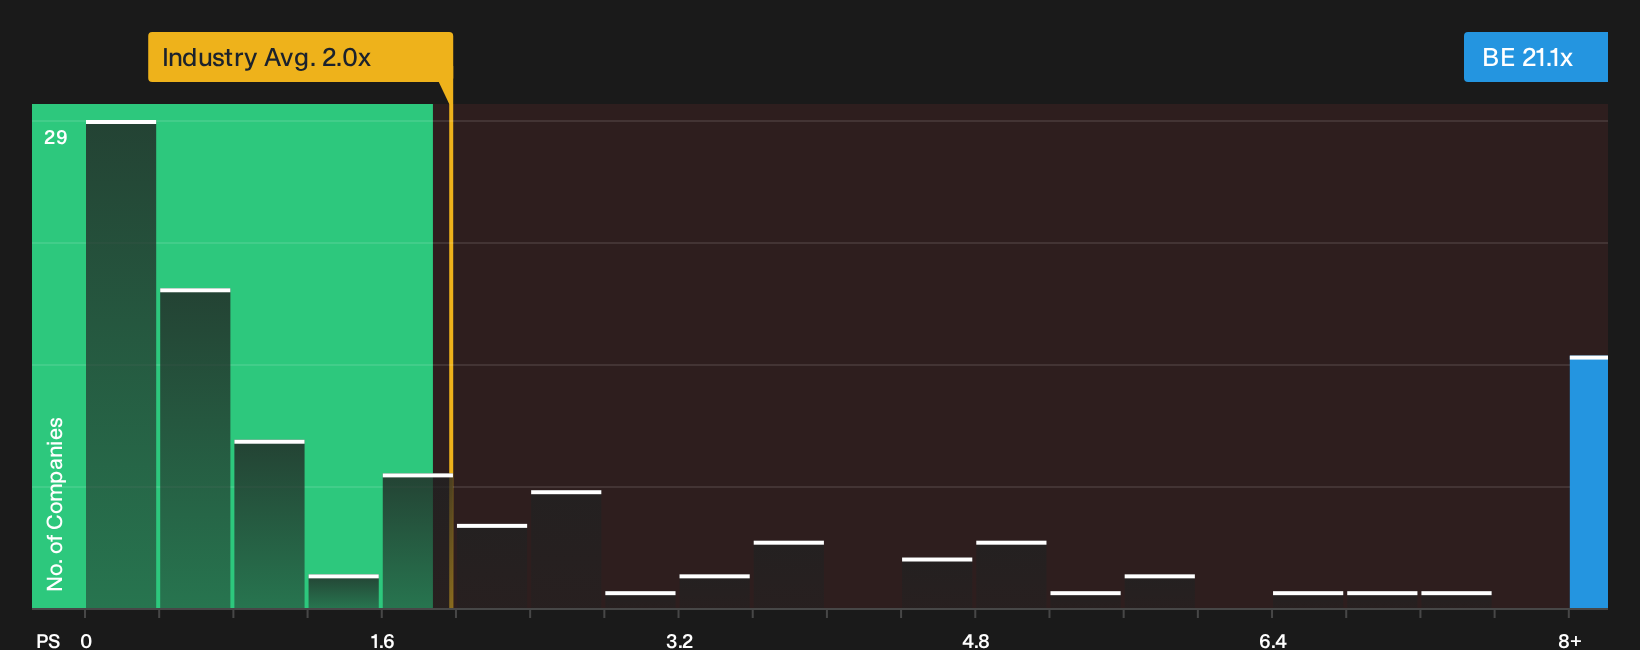
While one narrative sees Bloom Energy as 42% undervalued, the market is already paying a steep P/S of 21.1x. That is far above the US Electrical industry at 2x, the peer average at 5x, and even the fair ratio of 14.8x that the market could move toward, which raises valuation risk if growth expectations slip.
Investors weighing that gap against the AI data center story may want to stress test their own assumptions before treating the recent pullback as a clear opportunity. The valuation breakdown helps frame that debate further, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Bloom Energy story make sense given the recent swing in sentiment, so move quickly, review the underlying data, and decide where you stand by weighing the 3 key rewards and 4 important warning signs.
Looking for more Bloom Energy investment ideas?
Bloom Energy will not be the only story moving on AI, power, or earnings this season, so widen your scope now and avoid chasing the same crowded trades everyone else is already watching.
- Spot potential mispricings early by scanning a curated set of 34 high quality undervalued stocks that pair stronger fundamentals with more reasonable expectations.
- Prioritise resilience by filtering for 31 resilient stocks with low risk scores that may better match a portfolio focused on steadier balance sheets and lower volatility.
- Get ahead of the herd by reviewing 21 high quality undiscovered gems that the broader market may not be watching closely yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com