
Is Non Dilutive Debt Funding Altering The Investment Case For MedinCell (ENXTPA:MEDCL)?
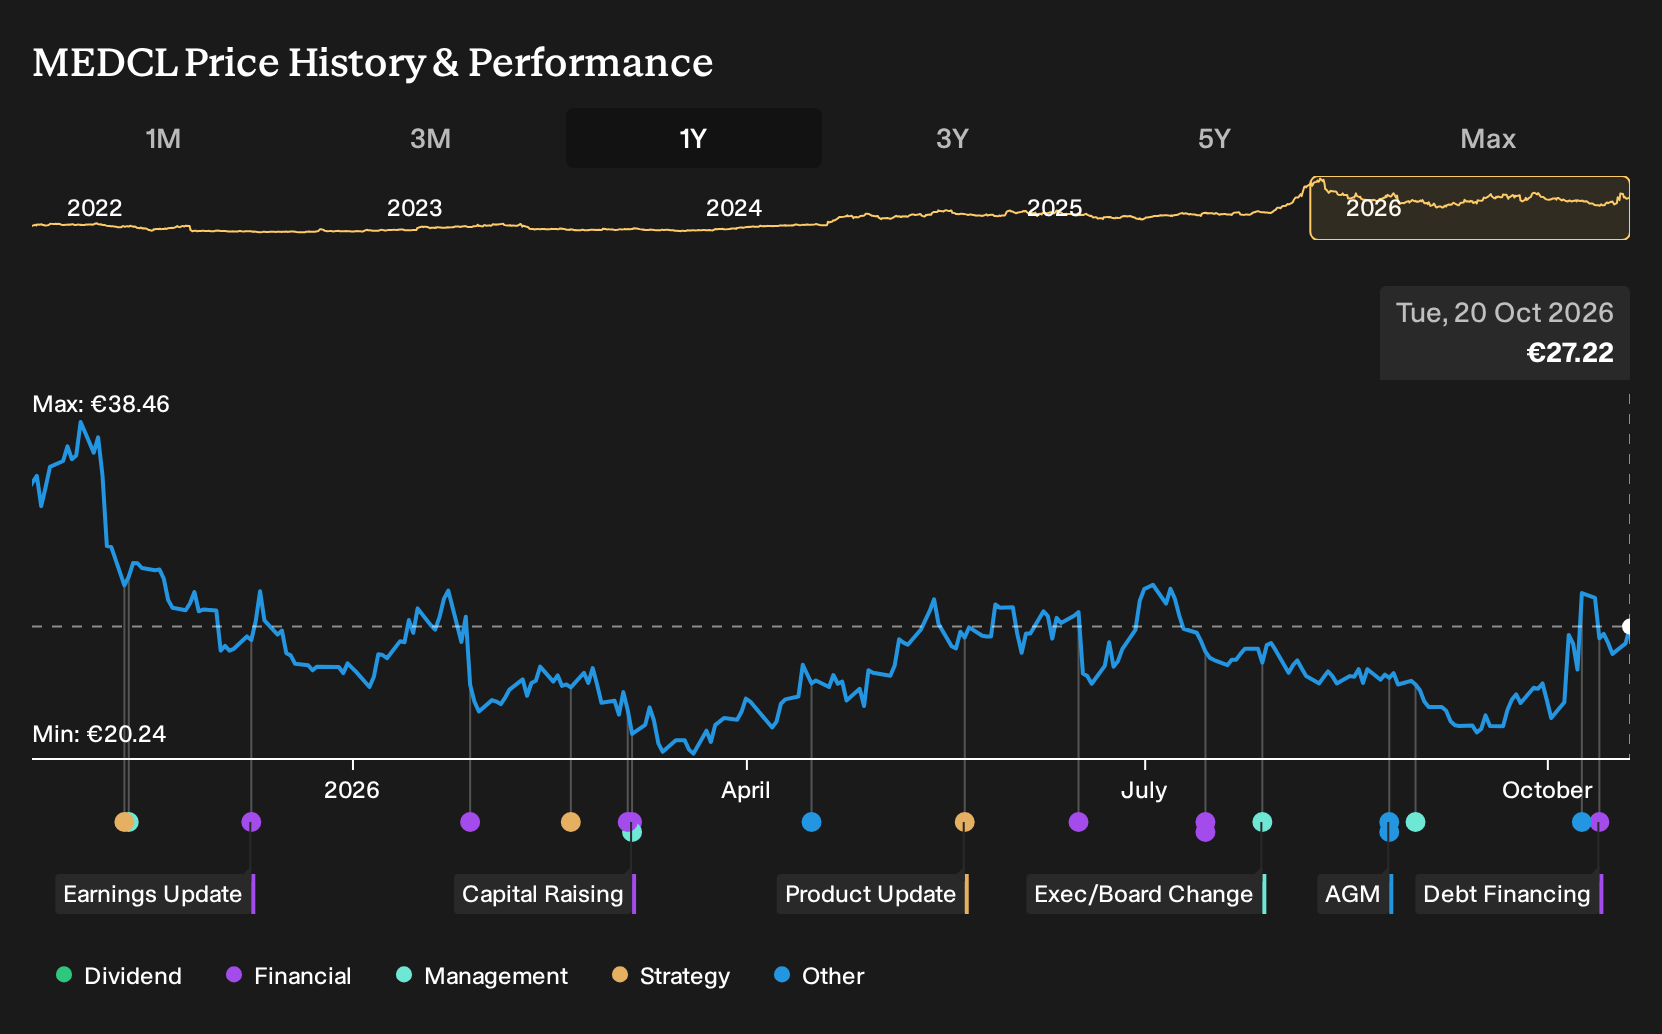
- MedinCell has secured €41.8 million in non-dilutive bank financing since July 2026, extended its debt maturity to September 2031, and repaid 50% of its European Investment Bank facility while holding €84.8 million in cash and cash equivalents as of March 31, 2026.
- This mix of fresh non-dilutive funding and early debt repayment reduces refinancing pressure for MedinCell and may give management more room to fund BEPO based programs and partnerships without issuing new shares.
- The next area of attention is how MedinCell's extended debt maturity profile could reshape its investment narrative for long term holders.
Scan beyond MedinCell and stress test your thesis against other companies that have prioritized balance sheet strength using our hand picked list of solid balance sheet and fundamentals (202 results).
MedinCell Investment Narrative Recap
To own MedinCell, you need to believe its long acting injectable platform can turn products like UZEDY and olanzapine LAI into a durable royalty and milestone stream while the broader BEPO pipeline matures. The fresh €41.8 million in non dilutive financing and long dated debt gives operations more time, but it does not change execution needs on the commercial side.
The key near term catalyst is how uptake and label progress for UZEDY and olanzapine LAI translate into revenue against a current net loss of €31.3 million. The biggest risk remains concentration on these two treatments, where any clinical, regulatory, or competitive issue could weigh heavily, regardless of the now more comfortable cash and debt runway.
The most relevant recent announcement is the non dilutive financing package and partial repayment of the European Investment Bank facility. MedinCell added €13.8 million on top of the earlier €28 million, while also paying back €23.2 million to the EIB and pushing debt maturity out to 2031, with €84.8 million in cash and equivalents reported at March 31, 2026.
That shift matters for how you think about catalysts. With less near term refinancing pressure, management can focus more squarely on commercial roll out, regulatory timelines for olanzapine LAI and new indications for UZEDY, plus progressing BEPO projects toward clinical stages. The trade off is higher reliance on execution and partnership milestones rather than fresh equity to fund missteps.
MedinCell's current analyst narrative points to €85.7 million in revenue and €39.7 million in earnings by 2029, built on an assumed 38.2% yearly top line expansion and a swing in profitability from a loss of €19.9 million today to positive earnings, which means an earnings improvement of about €59.6 million over that period.
Uncover why MedinCell's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on MedinCell’s balance sheet and more on how fast royalties could scale. Before this financing, they were already pencilling in about €140.6 million of revenue and €135.4 million of earnings by 2029. Those projections might shift after the new non dilutive funding, so it may be helpful to explore multiple viewpoints before deciding what seems reasonable.
Explore another MedinCell fair value estimate, including one that suggests as much as 667% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MedinCell research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MedinCell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MedinCell's overall financial health at a glance.
Looking for more investment ideas beyond MedinCell?
Once you understand where MedinCell fits in your portfolio, it can help to line it up against other opportunities that match different goals, risk levels, and income needs using the Simply Wall St Screener.
- For investors hunting for potential mispricings, compare MedinCell with a 188 high quality undervalued stocks that currently screen well on both quality and valuation metrics.
- If capital preservation is high on your list, weigh MedinCell against a 228 resilient stocks with low risk scores that score well on stability and balance sheet resilience.
- For those chasing less crowded stories, set MedinCell alongside a 616 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com