
Should CFO Appointment Require Action From Dauch (DCH) Investors?
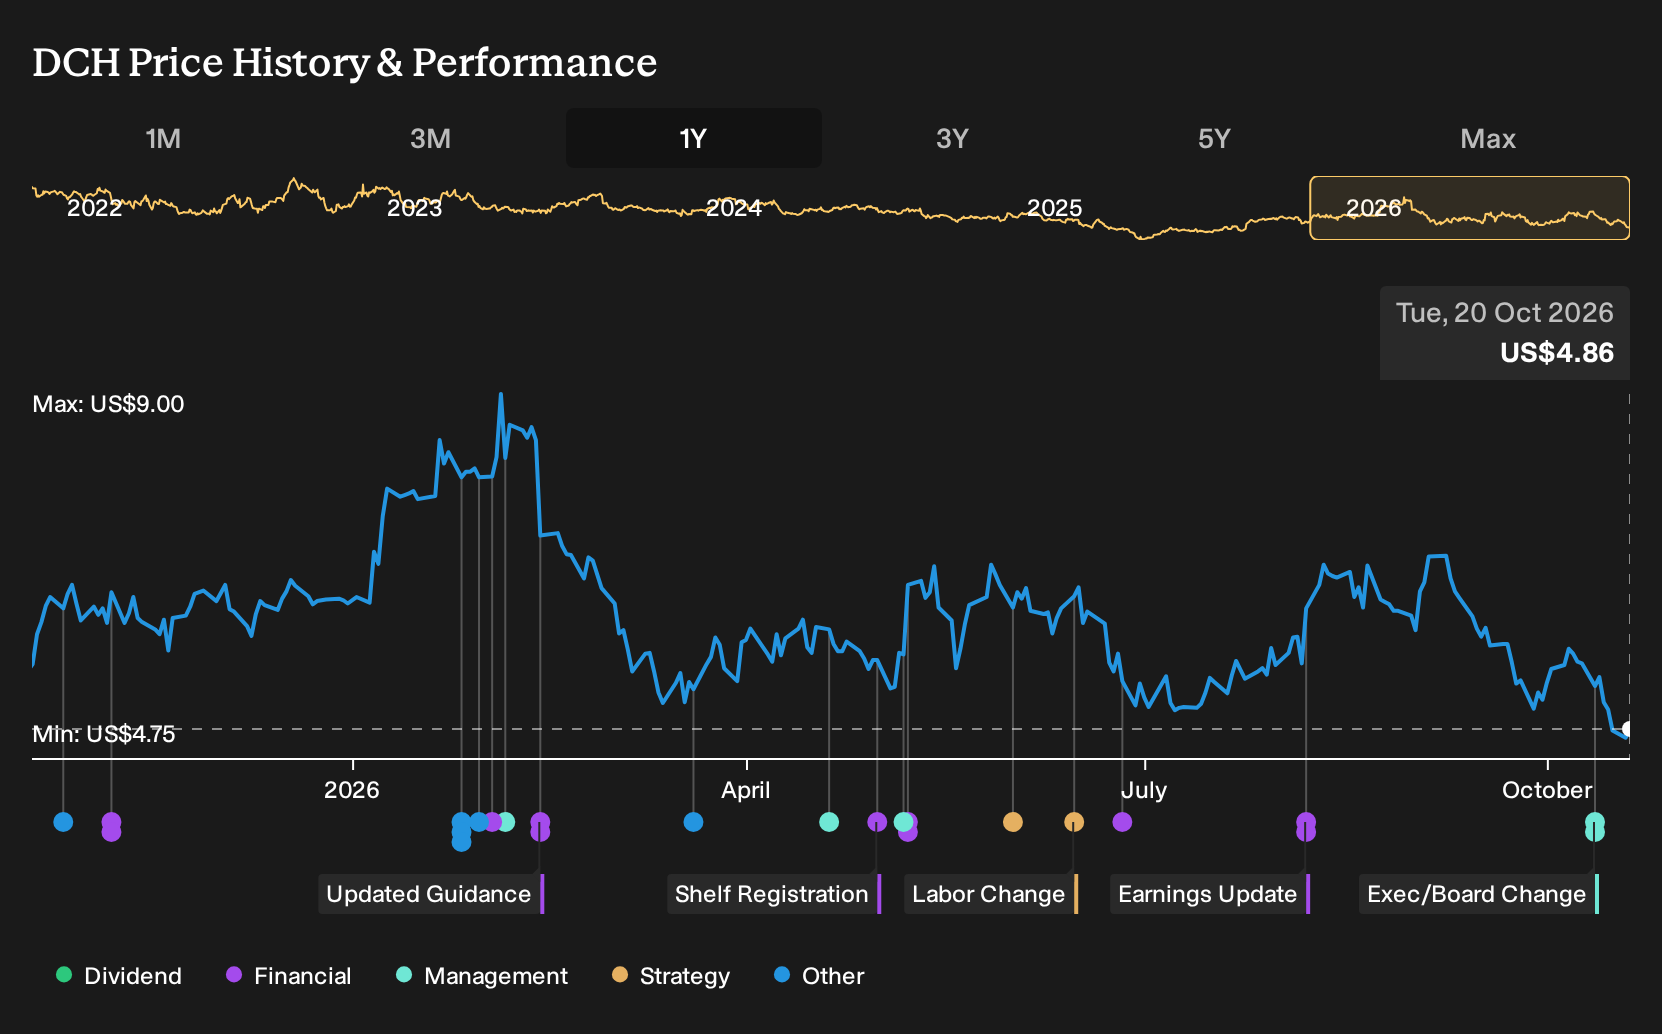
- Dauch Corporation recently announced that Nathan R. Iles, a veteran finance leader with over 25 years of experience at Standard Motor Products, UCI International Holdings and Ernst & Young, will succeed Christopher May as Chief Financial Officer on December 1, 2026, following his appointment as Senior Vice President of Finance effective November 2, 2026.
- The concurrent reshuffle, with May moving into an Executive Vice President & Chief Administrative Officer role and Terri Kemp focusing on corporate initiatives until her retirement, reflects a closer alignment between Dauch's finance, IT and HR functions. This may influence how the business manages costs, execution and long term planning.
- Attention now turns to Dauch's broader investment narrative, as observers evaluate how installing an experienced industry CFO could affect investor expectations.
See how Dauch's leadership reshuffle compares with other industrials by reviewing a hand picked group of companies in the list of solid balance sheet and fundamentals (25 results).
What Is Dauch's Investment Narrative?
To be a shareholder in Dauch, you need to buy into a fairly simple story. This is a heavy industrial supplier with US$8.2b in annual revenue, split across Driveline and Metal Forming, that is still loss making and capital intensive. Execution around cost control, pricing with automakers, and cash discipline matters more than any single quarter. The CFO transition fits directly into that reality. Investors are effectively betting that a seasoned finance head from Standard Motor Products and UCI can help tighten forecasting, capital allocation and balance sheet decisions around an unprofitable, globally exposed footprint.
In the short term, the key swing factors are not changing. Demand from light and commercial vehicle programs, the mix of electric and internal combustion content, and the ability to keep large global plants running efficiently still drive the story. The new finance structure, with Christopher May overseeing IT and HR and Nathan Iles stepping into the CFO role, could influence how quickly Dauch responds on restructuring, capex timing and working capital. However, the immediate operational risks around losses, leverage and shareholder dilution history do not vanish because one executive chair moves.
That said, before treating Dauch as a simple value play on forecasts and P/S multiples, there is an underappreciated pressure point that...
There's only one way to know the right time to buy, sell or hold Dauch. Head to Simply Wall St's company report for the latest analysis of Dauch's Fair Value.
Exploring Other Perspectives
High conviction bulls on Dauch focus on one catalyst. They expect the enlarged post Dowlais footprint and US$11–12b revenue base to support rising margins and earnings that reach about US$289.2 million, with revenue growing 14.5% a year. Those forecasts came before this CFO shuffle, so the most optimistic storyline may still evolve.
Explore another Dauch fair value estimate, including one that suggests there could be as much as 200% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dauch research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dauch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dauch's overall financial health at a glance.
Looking For More Ideas Beyond Dauch?
If the Dauch story has sharpened your thinking, it can help to compare it with other companies filtered by clear, data driven criteria using the Simply Wall St Screener.
- For readers hunting for mispriced quality, start with companies that screen as potentially undervalued on fundamentals through the 34 high quality undervalued stocks.
- If resilience matters more to you than excitement, focus on businesses that pass strict balance sheet and fundamentals filters by reviewing the list of solid balance sheet and fundamentals (25 results).
- For those who prefer steady income streams, zero in on higher yielding payers that still clear quality hurdles using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com