
How Investors May Respond To Semtech (SMTC) Expanded Capacity Deal
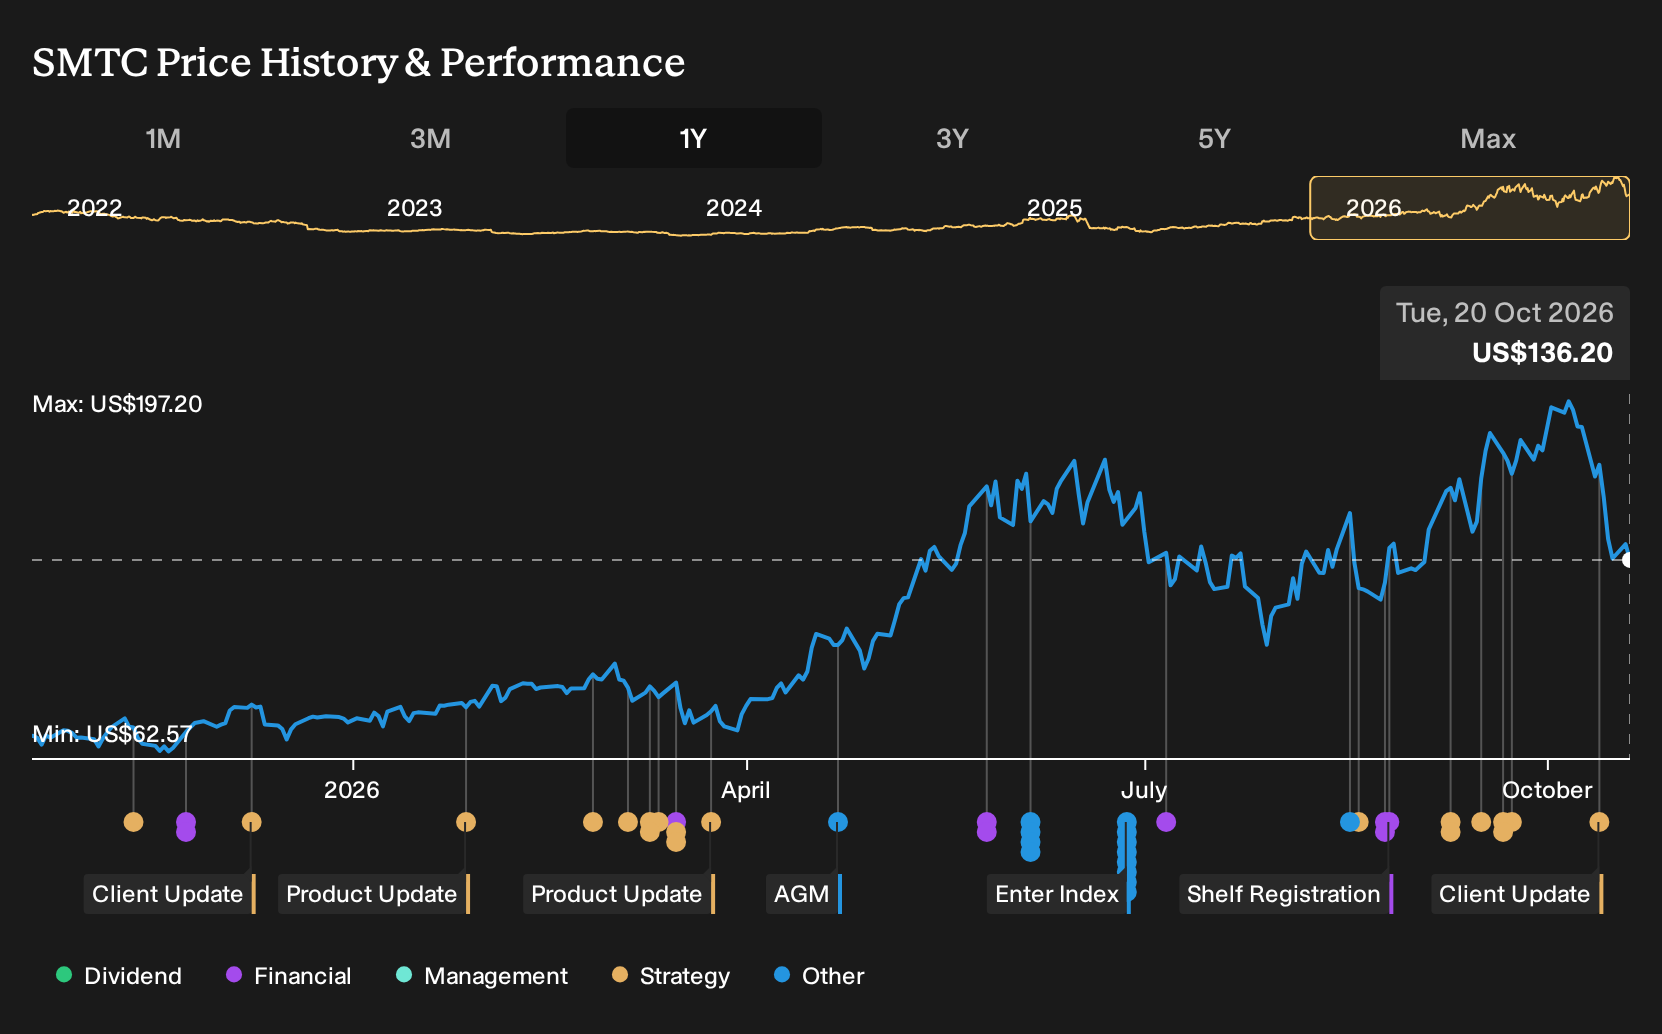
- On 13 October 2026, Semtech announced an expanded multi-year agreement with Tower Semiconductor to secure dedicated silicon germanium capacity across Tower’s fabs in the United States, Israel, and Japan for AI data center optical interconnect components.
- The deal deepens a 20-year collaboration and includes a joint technology roadmap, giving Semtech clearer supply visibility and manufacturing diversity as customer programs for SiGe based interconnects broaden across AI and data center uses.
- The next area of focus is how Semtech’s investment narrative could be reshaped by this expanded silicon germanium capacity commitment with Tower.
Semtech Investment Narrative Recap
To own Semtech, you need to believe its focus on high speed connectivity for AI data centers and IoT can offset lumpier segments and one off items in recent results. The expanded silicon germanium capacity with Tower reinforces that story by giving the Signal Integrity business clearer line of sight on supply, which supports execution on existing design wins.
The short term swing factor is still whether high margin data center demand actually converts to sustained orders while mix pressure from lower margin IoT and consumer products lingers. Key risks remain acquisition integration, margin dilution from product mix, and volatile orders in regions like China that can disrupt quarterly earnings.
The Tower agreement ties directly into Semtech’s earlier push to concentrate on core high growth areas such as data center optical products, LoRa and PerSe. That prior focus on portfolio rationalization and heavier R&D in connectivity now lines up with a committed SiGe manufacturing base, which makes it easier for the firm to align product roadmaps with available capacity.
For you as a shareholder, the interest is how this capacity access interacts with existing catalysts such as earnings expectations and design wins in AI data center interconnects. The operational question shifts to execution quality, yield and product mix within this SiGe footprint, and whether that helps counter pressures from lower margin segments and one off charges.
Semtech's current revenue forecasts point to 34.8% yearly growth, with analyst models calling for about US$2.9b in revenue and US$870.8m in earnings by 2029. That implies a move from US$154.0m in earnings today to US$870.8m, which is roughly a 5.7x increase and is framed as consensus expectations rather than a guarantee.
Discover why Semtech's fair value indicates a 62% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view zooms in on Semtech’s heavy reliance on hyperscaler AI data center spending. The most cautious analysts were only penciling in about US$2.5b of revenue and US$791.8m of earnings by 2029, before this Tower deal surfaced. That is a far more restrained story. Use it as a reminder that opinions differ and are likely to shift as fresh information like this capacity agreement filters through.
Explore 2 other Semtech fair value estimates, including one that suggests it could be worth just $208.61!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Semtech research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Semtech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Semtech's overall financial health at a glance.
Looking for more ideas beyond Semtech?
If Semtech has sharpened your focus on where AI and connectivity meet real-world cash flows, you can use that momentum to broaden your watchlist with other opportunities that fit different goals and risk levels.
- For potential value opportunities with strong fundamentals, you can scan a curated set of 34 high quality undervalued stocks that might suit a long term watchlist.
- If capital preservation and steadier profiles matter more to you, filter for 31 resilient stocks with low risk scores and see which companies align better with that mindset.
- When you want quality businesses that may not yet be widely followed, search through our 21 high quality undiscovered gems and build a pipeline of ideas before they are widely noticed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com