
Meridian Energy (NZSE:MEL) September Volumes Leave Its Undervalued Narrative In Focus
Meridian Energy volumes signal mixed operational trends
Meridian Energy (NZSE:MEL) just reported fresh operating data for September 2026, showing that retail contracted sales volumes were lower year on year, while total generation volumes increased over the same period.
Meridian Energy’s share price has inched higher in the short term, with a 1-day move of 1.99% and a 7-day share price return of 2.55%. However, the momentum looks softer when set against a 90-day share price decline of 2.43% and a slightly negative 1-year total shareholder return of 1.27%, despite total shareholder returns of 31.92% over three years and 37.68% over five years suggesting long-run investors have still seen meaningful gains.
Scan 42 power grid technology and infrastructure stocks to see which other grid and generation players could be setting up for the next move along with Meridian Energy.
Mixed volume trends and a share price that has firmed only slightly over the past month put Meridian Energy at an interesting crossroads. The key question is whether the current valuation still skews the balance of risk and reward toward buyers.
Most Popular Narrative: 10% Undervalued
Meridian Energy’s most followed thesis pegs fair value at about NZ$6.23 per share, compared with the latest close at NZ$5.63. That gap keeps the focus firmly on whether its long term build program and storage upgrades can earn the higher price implied by that narrative.
Rapid acceleration of renewable generation build-out is moving from plan to execution, with Meridian Energy progressing a pipeline that exceeds 6 TWh of new wind and solar generation by 2035 and planning about NZ$3b of growth capex between FY24 and FY30. This is expected to lift future revenue and EBITDAF as additional capacity enters the market.
See why 28 investors see Meridian Energy as 10% undervalued.
Result: Fair Value of NZ$6.23 (UNDERVALUED)
Still, rising operating expenses and a lift in net debt toward around NZ$1.7b could squeeze Meridian Energy’s margins and test the NZ$3b capital expenditure plan.
Find out about the key risks to this Meridian Energy narrative.
Another View: What Multiples Say About Meridian Energy
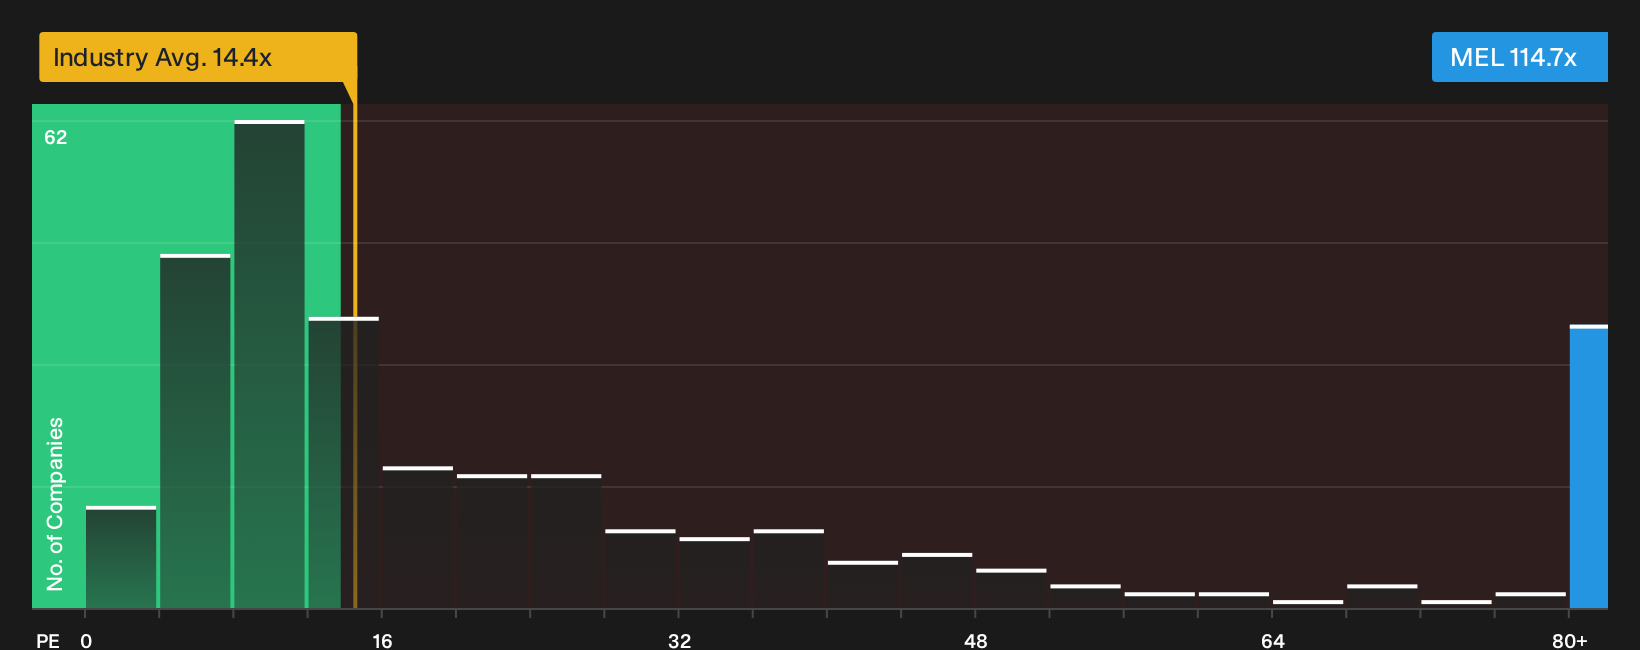
On one hand, the analyst narrative and fair value of NZ$6.23 point to Meridian Energy looking undervalued. On the other, the current P/E of 114.7x is far above the estimated fair ratio of 34.5x and well above both global renewable peers at 14.4x and a 26.6x peer average. That kind of gap can limit upside if sentiment shifts.
To see how this richer earnings multiple compares with the underlying fundamentals, take a closer look at our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed opinions like these do not settle themselves. Consider Meridian Energy's potential upside drivers alongside the pressure points and stress test the case using our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Meridian Energy?
Do not stop with a single thesis. Diversifying ideas now can help you spot opportunities earlier and avoid chasing whatever everyone else is already crowding into.
- Target potential mispricings by scanning companies that combine solid fundamentals with attractive valuations using our 190 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature resilient, higher yielding payouts through the 218 dividend fortresses.
- Reduce portfolio stress by focusing on companies with sturdier finances through our 229 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com