
Peloton (PTON) Stock May Be Pricey Despite a 94% Slump
Peloton Interactive has seen its share price move around sharply over the past few years, which leaves a clear question for investors who focus on valuation. Are today’s earnings enough to support where the stock now trades?
- The share price has fallen 94.1% over 5 years, which puts the spotlight firmly on whether the business now earns enough to justify any recovery hopes built into the valuation.
- The company’s model depends on turning connected fitness hardware sales into a recurring stream of subscription earnings, which can affect how durable its profits and cash generation look against the current share price.
- Your read on Peloton Interactive is one view; the desks covering it have another. See what analysts think Peloton Interactive's shares could be worth.
For investors, the debate is whether Peloton Interactive’s recent earnings profile is strong and reliable enough to support the current market price.
If you want to test the same earnings question you are asking of Peloton Interactive against a broader set of stocks, take a look at 33 high quality undervalued stocks.
Has Peloton Interactive Run Too Far on Earnings?
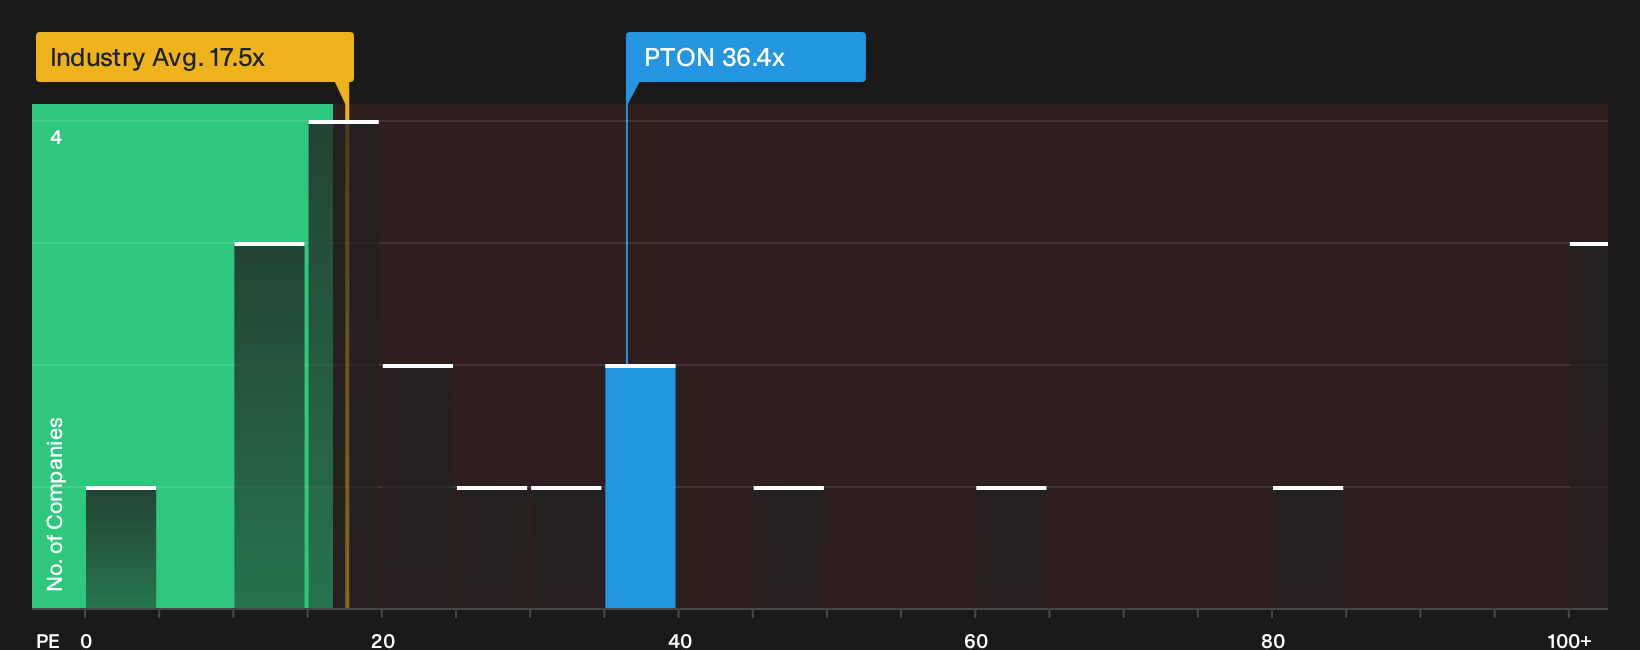
P/E fits Peloton Interactive because investors are mainly weighing the value of its earnings stream against the current share price. The stock trades on a P/E of 36.4x, which is much higher than the Leisure industry average of 17.5x and also above the peer group at about 20.3x. That gap indicates the market is applying a richer price tag to each dollar of Peloton Interactive’s earnings than to many comparable businesses in the sector.
The Fair Ratio, which adjusts the benchmark P/E for Peloton Interactive’s specific margins, scale and risk profile, also sits below the current multiple. On this basis, the shares appear overvalued because the present P/E is higher than the level implied by that tailored yardstick. Anyone considering the stock needs to decide whether the earnings quality and business model justify paying such a premium multiple. Explore the numbers behind Peloton Interactive's P/E valuation.
The Peloton Interactive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Peloton Interactive's valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today on the market. Each scenario lays out the underlying assumptions behind its view of fair value so you can compare those expectations with the company’s reported results over time on the Community page.
Peloton Interactive draws sharply different readings from the community, with one group seeing meaningful upside potential and the other flagging clear downside risk.
Bull case: 66% undervalued
"Planned expansion of Peloton Interactive’s compact “micro store” concept from 10 to around 20 locations, after these smaller footprints proved more capital efficient…"
Discover why this Narrative puts Peloton Interactive at 66% undervalued.
Bear case: 31% overvalued
"Although new products such as the Cross Training Series, lower priced treadmills, connected Pilates offerings and AI driven Peloton IQ features are intended to refresh demand, gross subscriber additions are reported to be down about 78% from peak levels…"
Explore why this Narrative puts Peloton Interactive at 31% overvalued.
Peloton Interactive’s valuation leaves one crucial issue unresolved
Price tags and earnings only tell part of the story for Peloton Interactive, because separate checks are already flagging specific areas of concern that investors may want to weigh carefully before making a call. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com