
AT&T (T) Stock Falls After Q3 Earnings Revive Debt Fears
AT&T came into this Q3 2026 report wearing the usual label: a high-yield telecom giant trading on low expectations. The stock had already slipped over the past month and then dropped another 6.5% today to about US$21.90.
The numbers tell a different story from that one day move. Management highlighted adjusted earnings per share of US$0.65 and adjusted earnings before interest, tax, depreciation and amortization of a 38.7% margin, the strongest Q3 margin since the refocus on advanced connectivity. The real flashpoint now is not demand; it is the balance between that margin story and a heavier debt load after the recent spectrum deal.
Like the high Q3 margin story at AT&T but uneasy about the heavier debt load after the spectrum deal and the pressure that puts on future flexibility? Screen for telecoms and infrastructure stocks that pair strong profitability with sturdier balance sheets using the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$32,322 million vs. US$30,709 million (up about 5%).
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$892 million vs. US$9,278 million (sharply lower year on year).
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.13 per share vs. US$1.30 per share (significant decline for the quarter).
- Adjusted EBITDA Margin (Q3 2026): 38.7% adjusted EBITDA margin in Q3 2026, described as the strongest Q3 margin since AT&T refocused on advanced connectivity.
Prefer clean charts over another wall of telecom earnings tables and footnotes? See AT&T's full financial picture with a clear view of its balance sheet strength and debt profile in the interactive company report for AT&T.
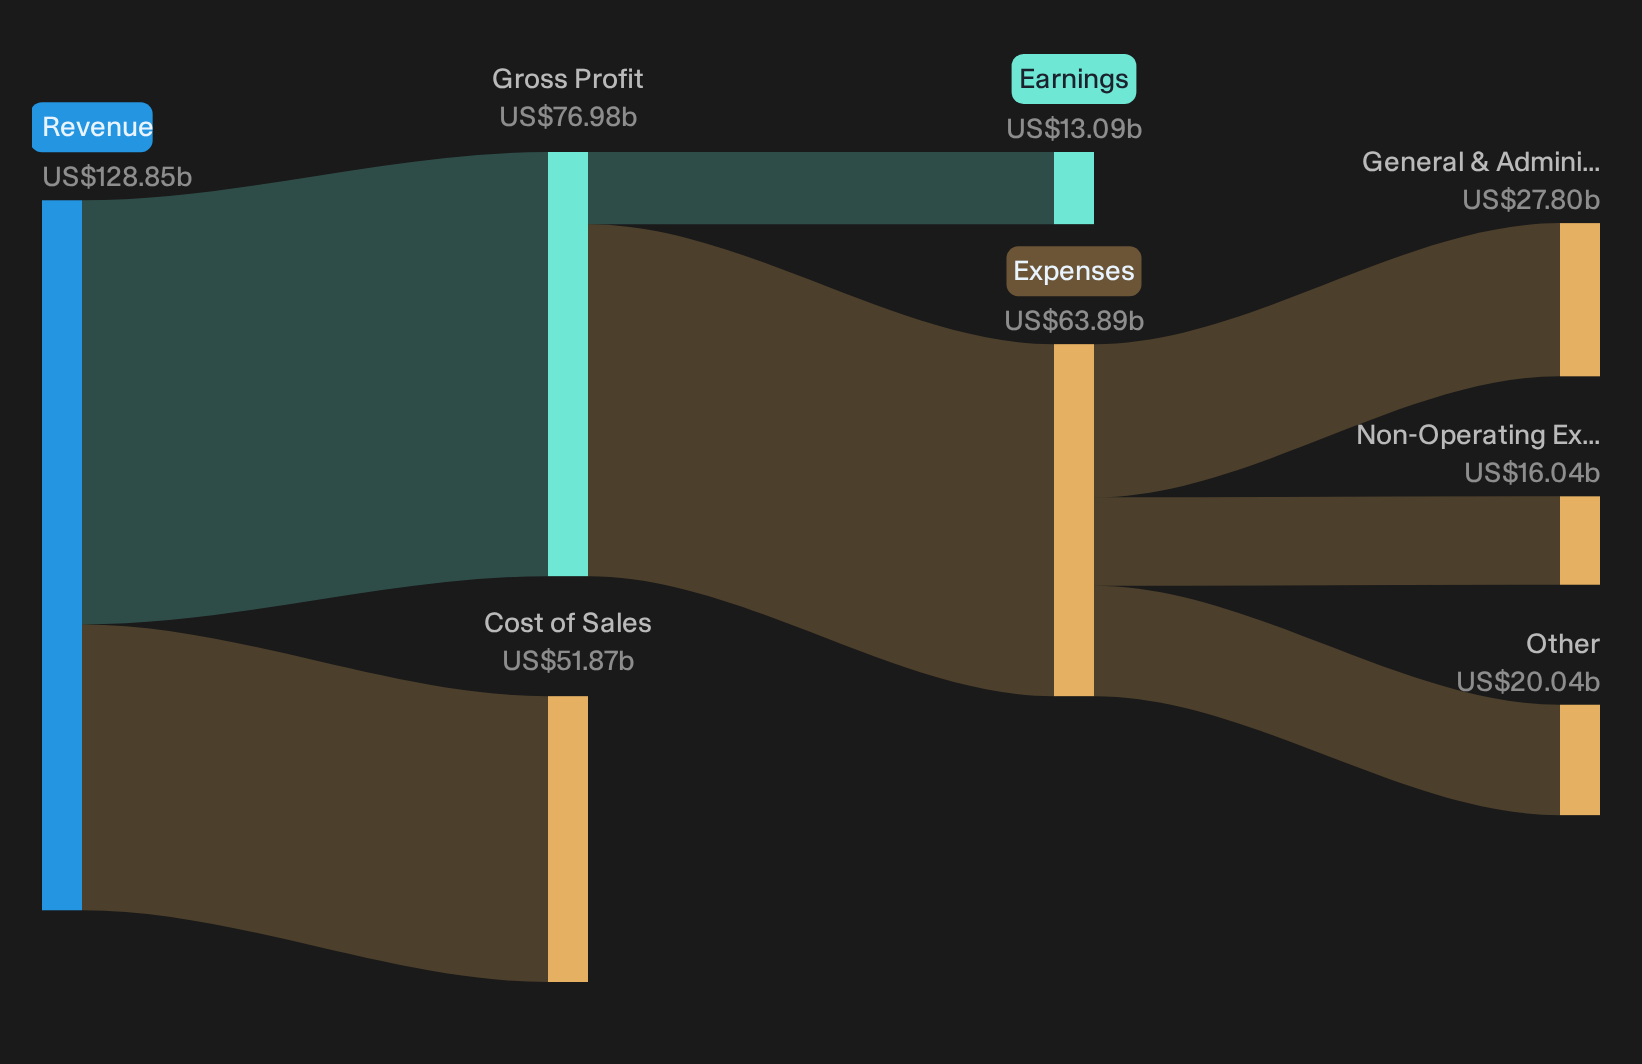
AT&T fiber thesis gets real-world proof
The bullish story hinges on AT&T turning its fiber build and convergence pitch into real customer and cash flow progress.
"The main thing that has to go right is that AT&T converts its fiber-led convergence and copper retirement plans into higher value converged accounts and lower legacy costs, without Lumen-related integration issues or device subsidy constraints dragging on results for too long."
Q3 shows tangible movement toward that goal. Converged accounts increased by about 350,000, nearly 43% of Advanced Home Internet users now also take postpaid wireless, and Advanced Connectivity service revenue and EBITDA both rose. Legacy copper revenue fell sharply, which supports the expense reduction side of the equation.
Capital strain keeps AT&T upside on a leash
The more cautious view argues that AT&T’s heavy network build and subsidy discipline could leave returns under pressure.
"Bearish analysts expect AT&T's heavy 5G and fiber build, paired with reliance on tax incentives, to leave revenue growth struggling to keep pace with the effort required to support it."
Q3 top line expanded in the low to mid single digits while capex remained high at US$5.6b for the quarter and in the range of US$23 to US$24b for the year. Net leverage moved above 3x after the EchoStar spectrum deal, and the stock fell about 6.5% on the print, which signals ongoing concern that investment intensity is still stretching the balance sheet.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Hunt For Mispriced Cash Engines
AT&T’s Q3 mix of stronger margins and a heavier balance sheet shows how quickly sentiment can swing. The real opportunity sits in stocks that could be undervalued before expectations reset.
- Company 1 - 40% below our estimate - turns a record solar equipment backlog into higher margin storage and inverter rollouts for utility scale projects.
- Company 2 - 41% below our estimate - builds protective film and window solutions that ride new manufacturing plants and deeper automaker and dealer partnerships.
- Company 3 - 47% below our estimate - supplies concrete reinforcement products that ride infrastructure funding into higher demand from highways, streets and data center projects.
That is three of the list. See every one of the 33 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com