
Kodiak Gas Services (KGS) Could Be 41% Below Fair Value As Weak Results Raise Questions
Kodiak Gas Services (KGS) is back under scrutiny after weaker quarterly results, with a shrinking EBITDA margin, low free cash flow and heavy investment spending raising fresh questions about earnings sustainability and valuation.
Recent price action tells that story in numbers. Kodiak Gas Services has a 1-day share price return of 3.35% to US$49.02, yet the 30-day share price return is down 12.84% and the 90-day share price return is down 24.91%. This suggests momentum has cooled, even though the year-to-date share price return of 30.23% and 3-year total shareholder return of about 3.3x still indicate a strong longer run for investors who held through the swings.
Compare Kodiak Gas Services with a curated group of contract infrastructure peers by scanning the list of solid balance sheet and fundamentals (25 results) that may better balance cash generation and capital intensity.
Kodiak Gas Services now trades at a steep discount to both intrinsic estimates and analyst targets after that sharp pullback. Is the market prudently discounting fragile cash generation, or is it mispricing a solid contract infrastructure franchise?
Most Popular Narrative: 41% Undervalued
Kodiak Gas Services is priced at $49.02 against a widely followed fair value estimate of about $82.73. This frames the recent pullback as a valuation gap rather than just a sentiment swing.
The build out of a 2 GW behind the meter power fleet, supported by roughly 1.8 GW of ordered or secured generation capacity and a multi year turbine supply agreement, is expected to add a new stream of long term contracted power revenue and support margin contribution as the segment scales.
See why 4 investors see Kodiak Gas Services as 41% undervalued.
Result: Fair Value of $82.73 (UNDERVALUED)
Still, that fair value gap only holds if Kodiak Gas Services can keep a tight grip on rising costs and avoid repeat earnings misses that strain its heavy reinvestment plans.
Find out about the key risks to this Kodiak Gas Services narrative.
Another View: Kodiak Gas Services Looks Expensive On Earnings
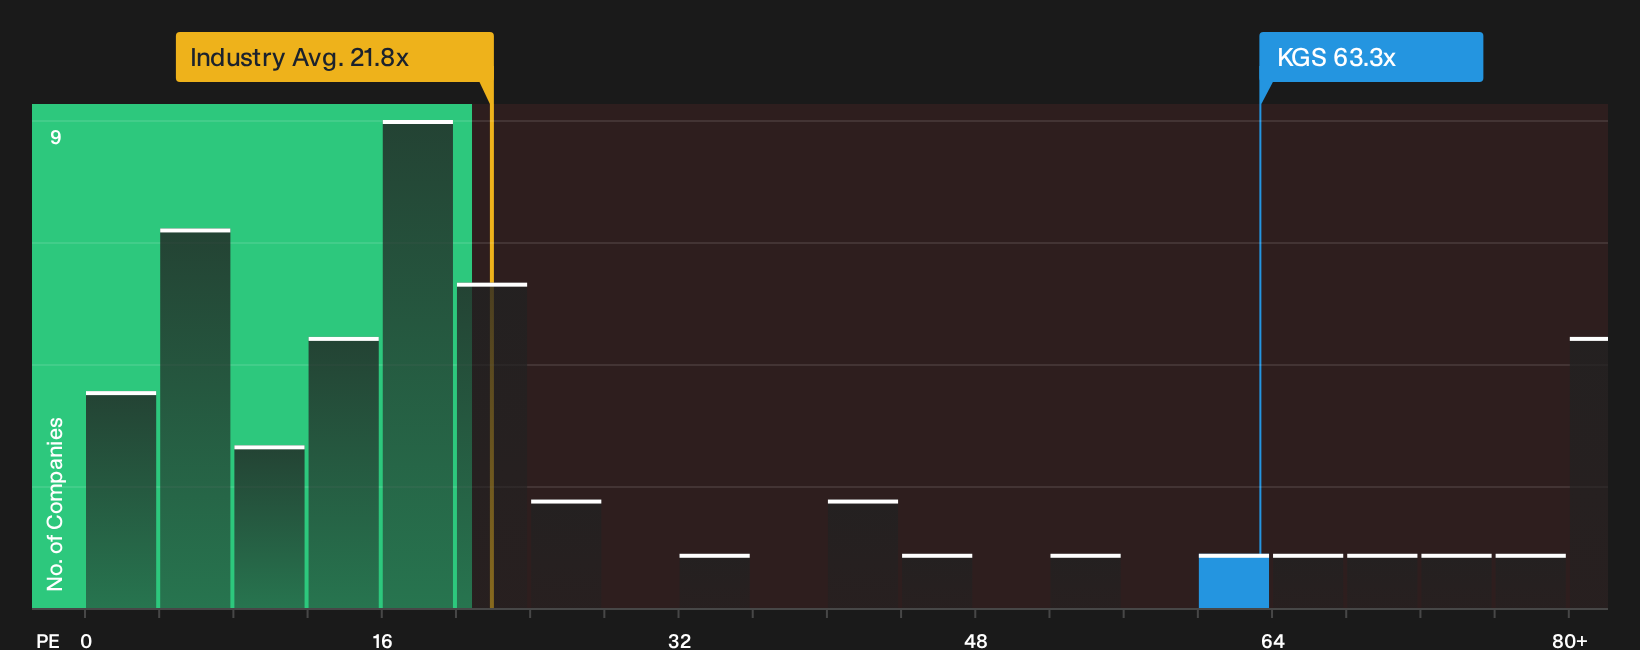
The big fair value gap for Kodiak Gas Services clashes with what its earnings multiple is saying. At about 63.3x P/E versus a fair ratio of 27.1x, the stock trades at more than double the level the model suggests the market could move toward, which lifts valuation risk rather than reducing it.
The premium is also steep next to both the US Energy Services industry on 21.7x P/E and peers at 24.9x. If earnings growth or margins fall short of forecasts, sentiment could move quickly back toward those lower reference points.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kodiak Gas Services can cut both ways, so move quickly, review the numbers yourself, and weigh the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond Kodiak Gas Services?
If Kodiak Gas Services feels too finely balanced on risk and reward, broaden your watchlist and let data driven filters surface fresh opportunities for you.
- Target potential mispricings by scanning a focused set of under followed stocks through the 21 high quality undiscovered gems.
- Prioritise resilience by reviewing companies that clear strict balance sheet and fundamentals checks with the list of solid balance sheet and fundamentals (25 results).
- Lock in cash focused ideas by checking out income candidates that feature in the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com