
KeyCorp (KEY) Stock Q3 Earnings Strength Deepens Its Capital Return Story
KeyCorp stock barely flinched after earnings, up about 1% to US$21.03, yet the Q3 2026 report landed with far more force than that move suggests. The bank posted Basic EPS of roughly US$0.55 on revenue of US$1.98b, with net income of US$579m, keeping its recent earnings rebound intact.
Short term traders see a quiet session. Long term holders see a regional lender leaning harder into higher return commercial lending and stricter credit. Current valuation metrics and multi year profitability targets are setting up a very different conversation than today’s modest price reaction.
If you are interested in the earnings recovery at KeyCorp and want balance sheet strength to be the main focus, consider the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,983m vs. US$1,779m (+11.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$579m vs. US$454m (+27.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.55 vs. US$0.41 (+33.1%)
- Net Interest Margin (Q3 2026 vs. Q3 2025): 2.89% vs. 2.75% (higher spread on interest earning assets)
Earnings tell one story, but investors who care about valuation usually follow the cash coming in and out of the business. Cash flows can paint a different picture of how KeyCorp converts reported profit into real capital that supports dividends and future lending capacity.
Based on those cash movements alone, some readers may look at KeyCorp's recent results and conclude the stock could be a hefty 46% undervalued.
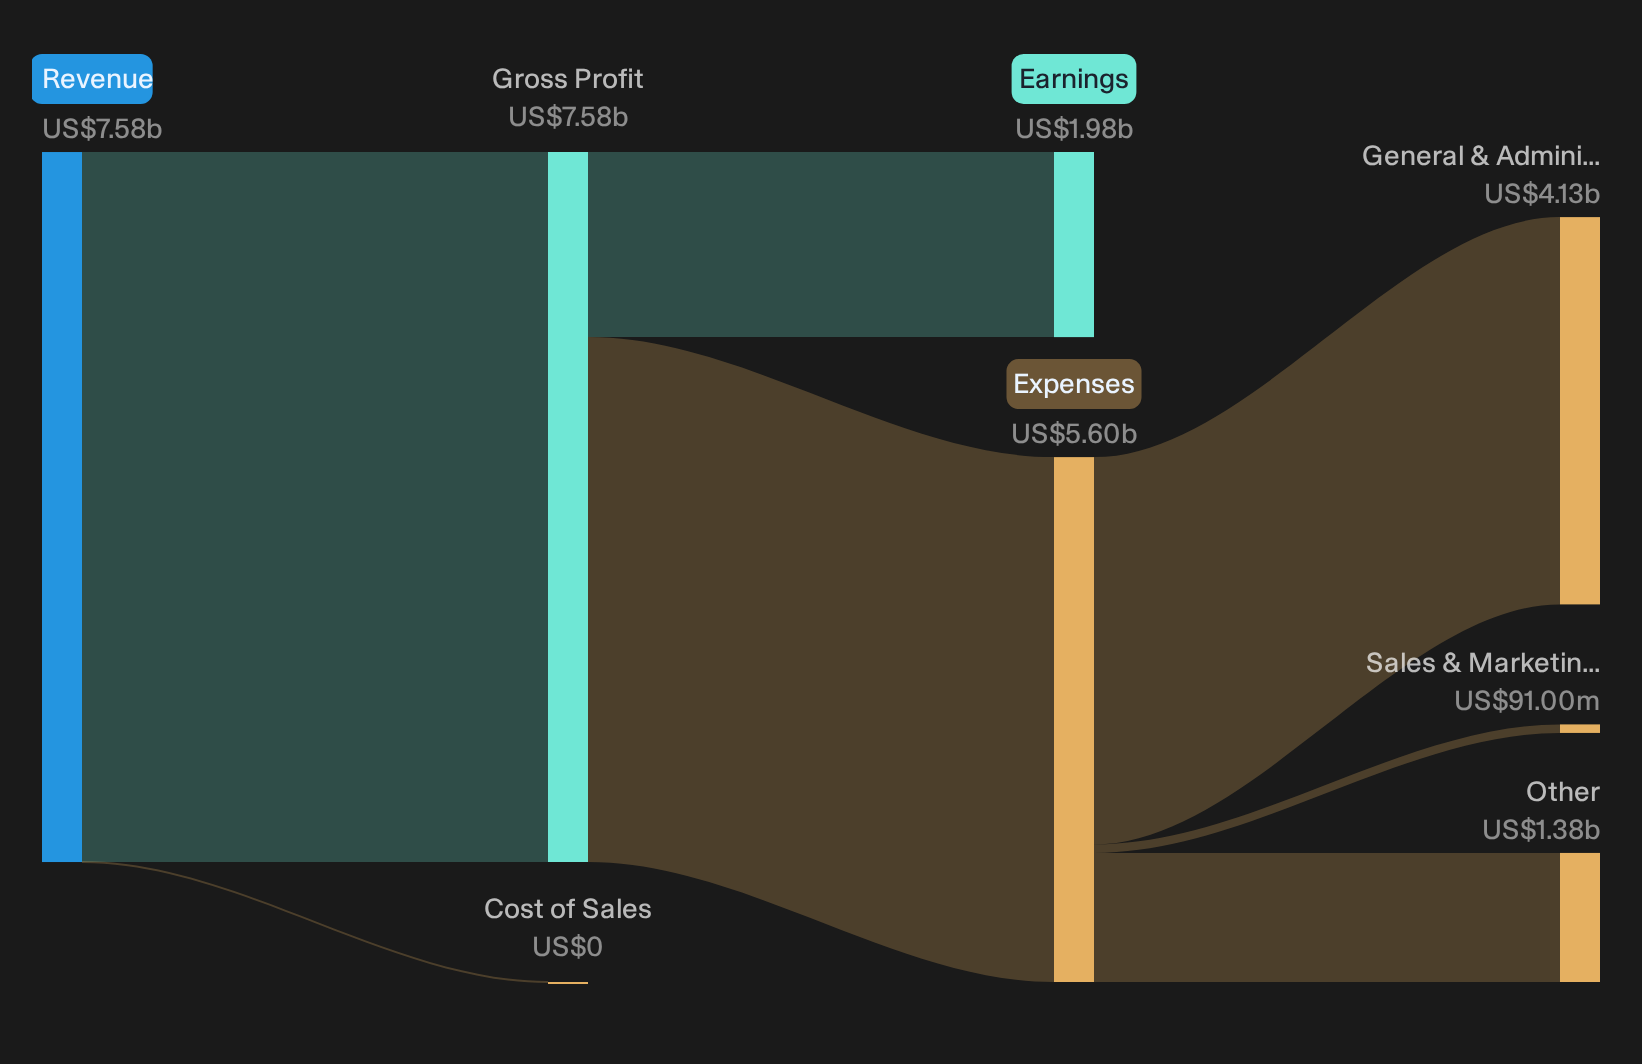
Evaluating KeyCorp’s Growth And Capital Flex Story
The bullish view hinges on KeyCorp turning balance sheet remix and capital firepower into higher earnings quality and returns.
"Peer leading capital ratios with CET1 approaching 12% and marked CET1 of 10.3%, combined with planned and potential incremental share repurchases and balance sheet restructurings, create flexibility to optimize the capital base."
Q3 puts hard numbers against that ambition. CET1 sits at 11.1% with marked CET1 at 9%. Management has already retired US$525m of preferreds and repurchased over US$1b of common year to date, with US$250m still targeted for 2026, while delivering 15.1% ROTCE and record pre provision profit.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
KeyCorp Bear Case: Costs, Cyclic Fees Still On Trial
Bearish investors worry that KeyCorp is building a cost base and fee mix that will not hold up if activity cools.
"Ongoing hiring of frontline producers and sustained technology spend, even after the initial ramp, risk entrenching a structurally higher cost base if fee growth from capital markets, commercial payments and wealth slows, compressing operating leverage and net margins."
Q3 shows this concern is only partially addressed. Noninterest expense rose to US$1.2b, while fee lines such as investment banking and priority fee businesses grew at double digit rates. Operating leverage looks healthy for now, yet the quarter does not prove what happens if deal volumes or payments activity soften.
Hunt For Mispriced Cash Flows
KeyCorp shows how earnings momentum can coincide with limited share price movement. The real opportunity is spotting stocks that could be undervalued before the market reassesses them.
- Company 1 - 46% below our estimate - targets long duration infrastructure and military projects reliant on disciplined bidding and execution.
- Company 2 - 33% below our estimate - converts large AI infrastructure and multicloud database commitments into recurring subscription revenue as clients expand workloads.
- Company 3 - 24% below our estimate - builds coconut based beverage brands and private label offerings as retailers increase shelf space for these products.
Those are three of them. See all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com