
Invitation Homes (INVH) Slides As Undervalued Narrative Faces A Tougher Market Test
Invitation Homes (INVH) has drawn fresh attention after recent share performance, with the stock down about 1% over the past month and roughly 9% over the past 3 months. Investors are reassessing what that move implies for the single family rental REIT’s valuation.
At a share price of US$26.81, Invitation Homes shows a modest 7 day share price gain, alongside a 1 month decline of about 1% and a 3 month slide of roughly 9%, while the 1 year total shareholder return is also slightly negative. This points to fading momentum and suggests recent moves reflect a cooler view on risk and growth potential than in prior years.
Compare Invitation Homes with a curated group of residential and income-focused opportunities by scanning our 7 dividend fortresses that might offer steadier returns than a single REIT under pressure.
Invitation Homes now trades at a clear discount to both analyst targets and some intrinsic value estimates. Are investors correctly pricing in risk, or has caution pushed the shares too far below fair value?
Most Popular Narrative: 18% Undervalued
Invitation Homes is priced at $26.81 while the most followed narrative anchors fair value at $32.83. This frames the recent share pullback against a higher long term assessment of the underlying real estate and cash flow profile.
The wide rent versus own affordability gap, combined with resident tenure above 40 months and projected net in migration into most Invitation Homes markets, points to sustained demand for single family rentals. This can underpin occupancy, rent growth and long term revenue and cash flow.
See why 15 investors see Invitation Homes as 18% undervalued.
Result: Fair Value of $32.83 (UNDERVALUED)
Still, the narrative around Invitation Homes can break if new rental supply pressures occupancy or if property taxes and insurance costs rise faster than expected.
Find out about the key risks to this Invitation Homes narrative.
Another View: Invitation Homes On Earnings Multiples
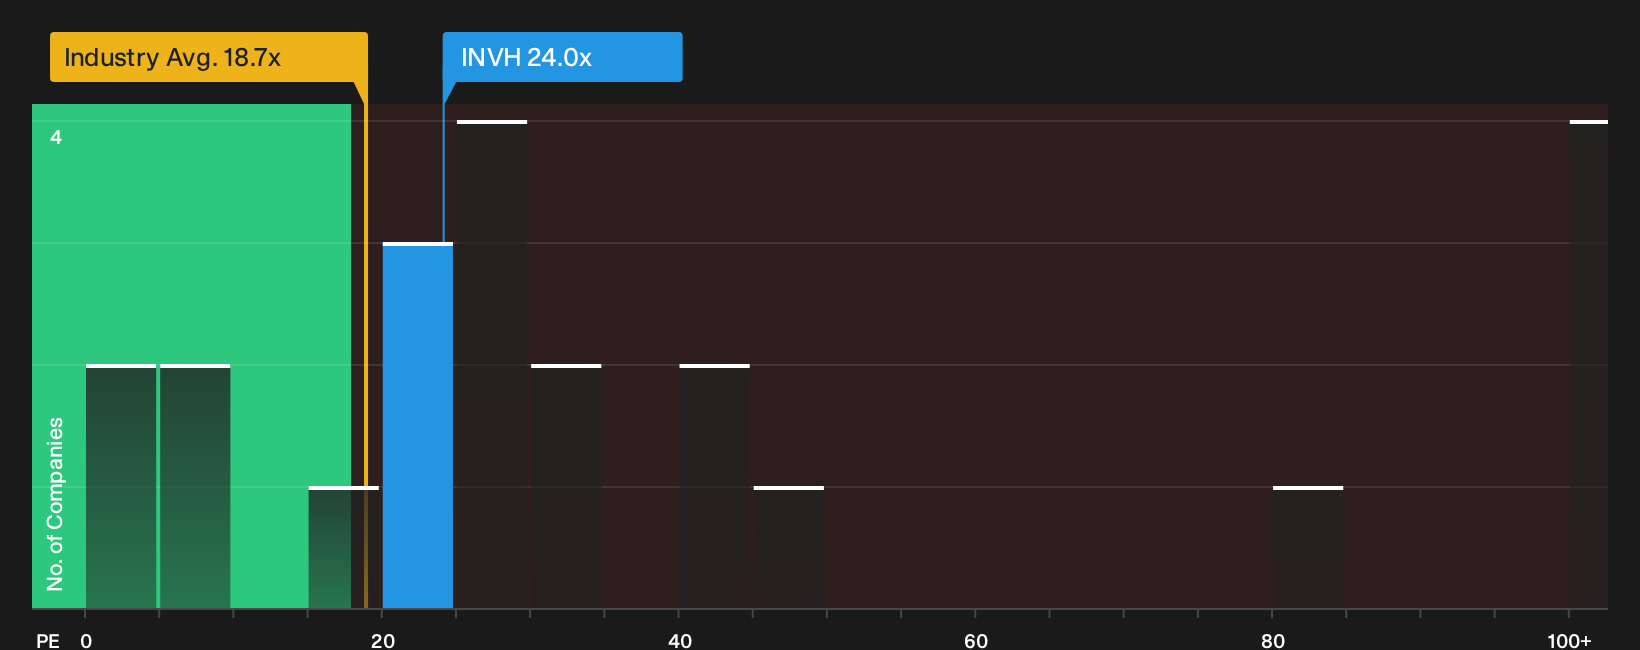
The story looks different when you drop the narratives and just compare Invitation Homes on P/E. The stock trades around 24x earnings, a clear premium to the Global Residential REITs average of 18.7x and slightly above its own fair ratio of 23.9x. That suggests there may be less margin for error than a simple discount to fair value might imply. The question is whether this is a genuine mispricing or simply a higher price for access to the same rental cash flows.
To see how the current P/E stack up against peers and the fair ratio, and what that means for potential upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the caution and optimism around Invitation Homes feel balanced to you or skewed one way? Act quickly and pressure test that view against our 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Invitation Homes?
Do not stop at Invitation Homes when there are other opportunities that might fit your goals just as well, or even better, based on hard numbers.
- Target resilient balance sheets and steady fundamentals by building a shortlist from our list of solid balance sheet and fundamentals (25 results) tailored to investors who value financial strength first.
- Zero in on quality at a discount by scanning the 33 high quality undervalued stocks that filters for strong businesses trading below their assessed worth.
- Prioritise stability and capital preservation with the 31 resilient stocks with low risk scores to focus on companies that score well on downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com