
United Therapeutics (UTHR) Stock Still Looks Undervalued On Its 203% Run
United Therapeutics has delivered a powerful run over the past few years, and with the stock last closing at US$563.49 the key issue is whether that price still lines up with what the business earns today. With fresh clinical and legal developments reshaping expectations, the central question is how much of that story is already embedded in the current valuation based on earnings.
- Over the past 5 years, United Therapeutics has returned 202.7%, which puts real weight on whether the earnings profile can support a share price at this level.
- The recent FDA clearance to proceed with the SUMMIT trial in PH-COPD, alongside the US$380.7m settlement with Liquidia, may influence how investors think about future profit durability, potential market opportunities and the timing of cash flows that underpin earnings power.
- There is a second opinion on United Therapeutics worth weighing. See what analysts think United Therapeutics's shares could be worth.
The stock's next move may depend on whether United Therapeutics' current earnings justify a price in the US$560s.
If you want more ideas built around similar earnings driven stories, a focused stock screen is a useful next step. You can start with 37 healthcare AI stocks.
Is United Therapeutics Still Cheap on Earnings?
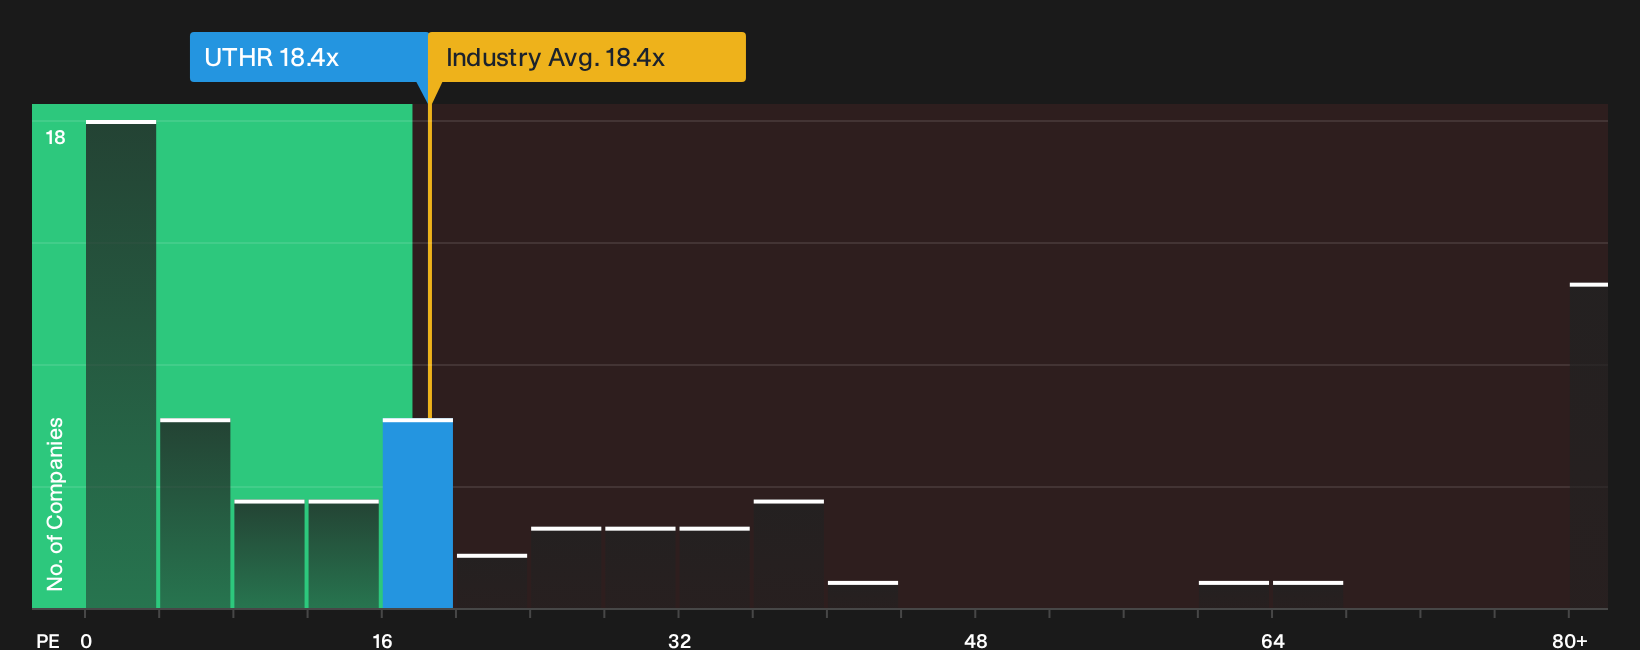
The P/E ratio works well for United Therapeutics because earnings remain the main anchor for how investors frame the story today. United Therapeutics trades on a P/E of 18.4x, compared with the biotech industry average of about 18.4x and a peer group closer to 24.0x. That leaves the stock on a lower multiple than similar companies even after the recent FDA clearance for the SUMMIT trial in PH-COPD and the Liquidia settlement reset expectations around its treprostinil franchise.
The fair P/E level implied by a more tailored model, which blends the company’s margins, growth assumptions, risk profile and size, sits above where the shares trade now. On this framework the current 18.4x P/E screens as undervalued relative to what investors might typically pay for a business with United Therapeutics' earnings profile. Explore the numbers behind United Therapeutics's P/E valuation.
The United Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for United Therapeutics leaves off by spelling out what kind of future for growth, margins and earnings would need to play out for the current share price to look materially higher or lower over time, and they sit on the company’s Community page. Rather than a single headline multiple or one model output, each one lays out the key assumptions behind its fair value view so you can track those against actual results as they arrive.
Community views on United Therapeutics split between those who see long runway in pulmonary fibrosis and organ programs and those who focus on pressure in the older franchises.
Bull case: 13% undervalued
"Lifecycle management of the prostacyclin franchise through multiple delivery platforms, including nebulized Tyvaso, Tyvaso DPI, soft-mist inhalers and once-daily ralinepag based regimens, creates opportunities to defend and extend the treprostinil and ralinepag portfolio…"
Discover why this Narrative puts United Therapeutics at 13% undervalued.
Bear case: 21% overvalued
"Bearish analysts expect United Therapeutics to continue facing pressure on core pulmonary hypertension revenue and earnings as competition in inhaled prostacyclins increases and past annual sales declines weigh on sentiment…"
Explore why this Narrative puts United Therapeutics at 21% overvalued.
United Therapeutics’ valuation leaves one crucial angle unexplored
Numbers only tell part of the story for United Therapeutics, because the track record and pay structure of the people in charge can heavily shape how those earnings evolve from here. See who runs United Therapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com