
Missed TFI International's Run? What Holders Had To Believe
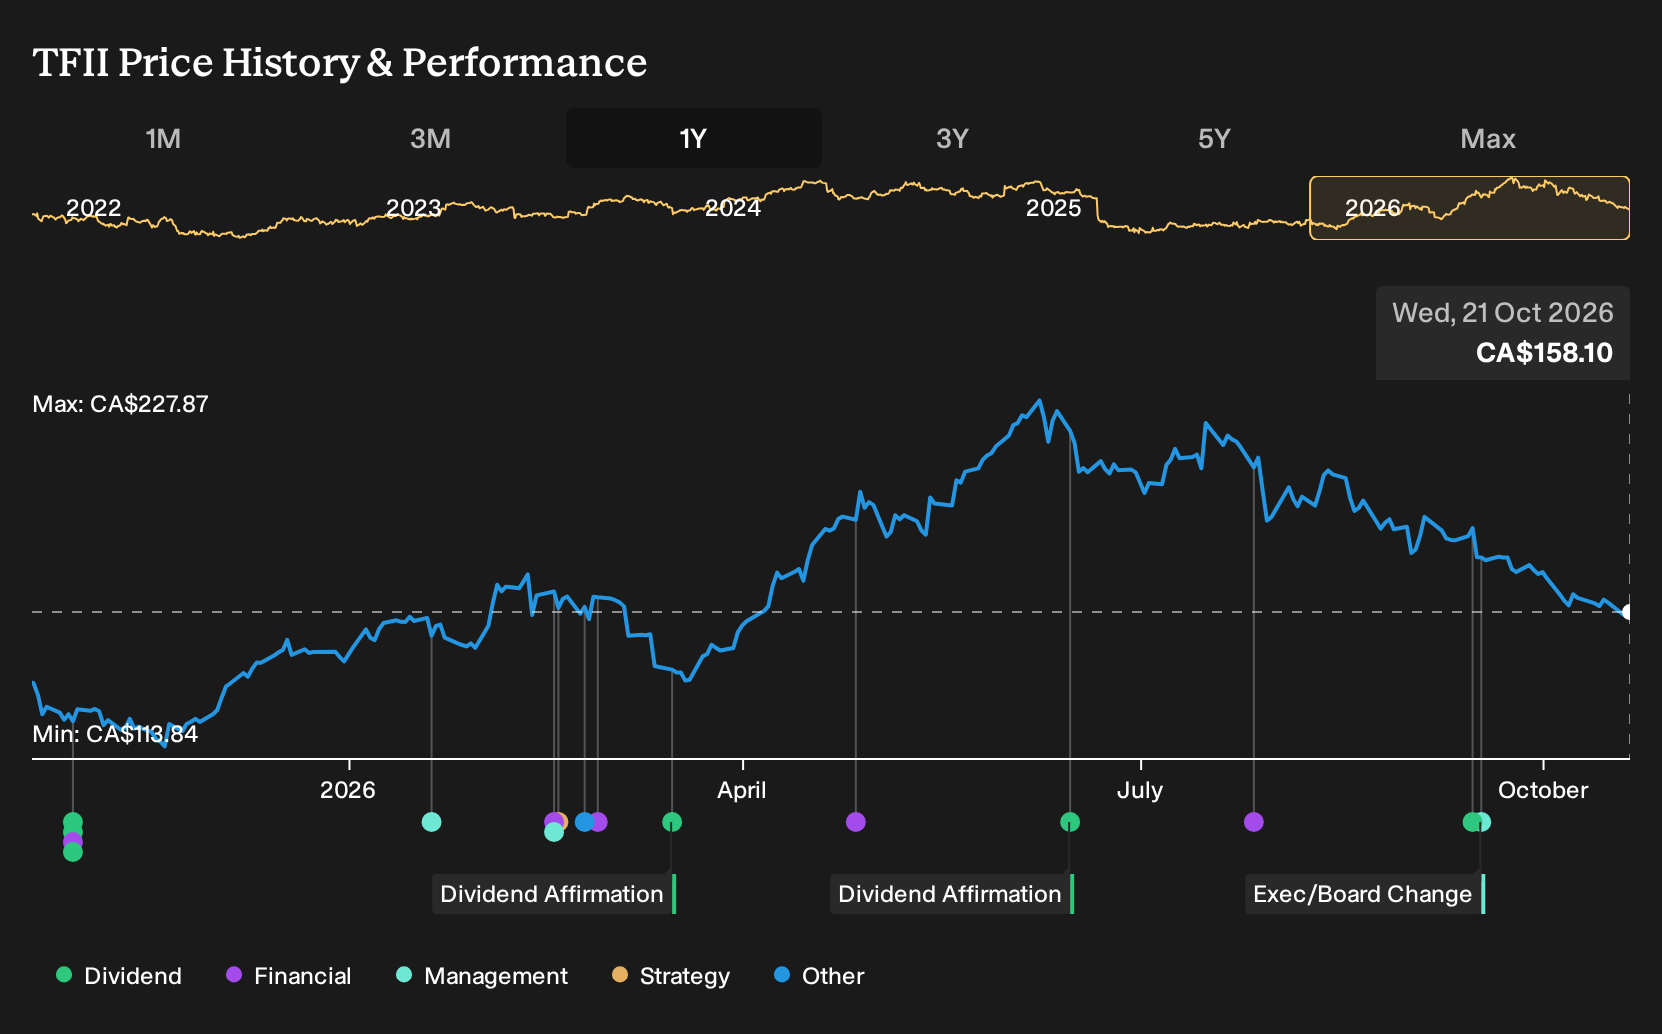
If you only skimmed headlines about freight uncertainty and stubborn LTL margin issues at TFI International, a flat or even weak result might have seemed entirely plausible. Holding TFI International over the past year would have returned 22.8%, including dividends. If you had been weighing that decision back in October 2025, with analysts split almost 30% apart on fair value, what did the facts on record actually signal about this outcome risk?
If the move has made TFI International harder to judge, start where the gap is still open and scan 4 high quality undervalued stocks.
The Two TFI International Stories You Had To Choose Between
The shares cost CA$135 at the start of the period, and anyone weighing TFI International then had to decide which story felt more realistic.
The bullish narrative pointed to a Fair Value of CA$170, a price that assumed e-commerce demand, AI, and automation would support a sub-90 LTL operating ratio and strong free cash flow from a more brokerage heavy model.
The bearish view argued for a Fair Value of CA$96.4, built on concerns that autonomous delivery, decarbonization spending, and driver shortages would strain freight demand and compress cash generation.
What The Results Changed For TFI International
Q2 2026 results showed TFI International with revenue of US$2.29b and net income of US$136.2m, compared with US$2.04b and US$98.2m in Q2 2025, lifting net margin from 4.8% to 5.9%. Shipment growth, LTL operating ratio gains, and acquisitions supported the bullish focus on better efficiency and free cash flow, although LTL pricing and margin execution kept the cautious case alive. Overall, the evidence cut both ways.
The decision hinged on whether margin expansion would actually appear in reported numbers. For any other hauler, start by checking segment operating ratios and net margin, and compare them with the story you are being sold about technology, mix, and acquisitions.
What You Are Paying For In TFI International Today
Today TFI International trades at CA$158, with this Narrative setting its Fair Value above that level based on current financials and business mix. The focus has shifted from broad tech hopes to how truckload, logistics, and U.S. LTL repricing shape cash generation.
The Narrative asks you to weigh whether U.S. LTL service and pricing can move closer to Canadian levels while current truckload and logistics margins hold. A buyer at today’s price has to judge that specific execution hurdle.
"The main requirement is that TFI International executes on its U.S. LTL turnaround and service improvement plan so that pricing, mix, and claims costs move closer to its Canadian operations and large peers, while truckload and logistics maintain current margin progress."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 26% below our estimate - runs a single high grade gold asset as anchor for nearby exploration ground.
- Company 2 - 47% below our estimate - operates linked gold and copper deposits sharing processing plants and exploration teams.
- Company 3 - 45% below our estimate - builds and runs tailored compute hardware and logistics networks for hyperscale buyers.
That is three of the list. See the full list of 7 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com