
Is Marathon Petroleum (MPC) Undervalued Or Is The Rally Priced In?
Marathon Petroleum has turned into one of the strongest performers in the U.S. refining space over the past few years, and the share price now puts a lot of weight on what its future cash flows can support. With the stock coming off an all time high after a sharp multi year climb, the key issue for you is whether the current valuation is still grounded in the cash the business can generate.
- Over the past 5 years the share price has delivered a very large gain of about 7x, which puts a lot of past optimism and future expectations into focus when you think about what its cash flows can realistically justify.
- Recent reports of tightening global diesel supply and record refining and marketing margins suggest Marathon Petroleum's cash generation may benefit from strong refining economics, although those conditions can shift and matter a lot for how dependable those cash flows look over time.
- If you'd rather focus on earnings, this one's for you. See why Marathon Petroleum's 15.4x P/E tells a different valuation story.
The issue now is whether the current stock price is adequately supported by Marathon Petroleum's cash flows when measured against a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want a broader watchlist while you evaluate Marathon Petroleum's cash flows, consider using a focused stock screen built around 33 high quality undervalued stocks.
Is Marathon Petroleum a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model looks at what Marathon Petroleum can return to shareholders based on future free cash generation. Over the last twelve months the business produced about $13.9b of free cash flow, and the 2 Stage Free Cash Flow to Equity model then assumes this level eases back toward lower but still meaningful annual figures over the coming decade as the refiner matures.
Those projections, when discounted, put Marathon Petroleum's estimated intrinsic value modestly above the current share price of $467.98. Because the recent surge in diesel prices and strong refining margins are already well known, the DCF outcome suggests the market is not pricing the stock far beyond what its current and projected cash flows can plausibly support. Find out what Marathon Petroleum could be worth using our Discounted Cash Flow (DCF) estimate.
The Marathon Petroleum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Marathon Petroleum sit between the cash flow model above and your own expectations by spelling out which combinations of future growth, margins and earnings would need to play out for the shares to end up worth materially more or materially less than today. Each scenario ties a fair value to a particular view of Marathon Petroleum's possible catalysts and risks so you can track over time which storyline appears to be unfolding.
Community views on Marathon Petroleum split between those who still see upside and those who think most of the good news is already in the price.
Bull case: 10% undervalued
"Refining investments at Galveston Bay, Garyville, Robinson and El Paso are aimed at converting lower value inputs into higher value products..."
Discover why this Narrative puts Marathon Petroleum at 10% undervalued.
Bear case: 8% overvalued
"The numbers suggest that a fairly valued, bearish view on Marathon Petroleum already reflects strong refining margins, substantial cash returns, and continued MPLX growth..."
Explore why this Narrative puts Marathon Petroleum at 8% overvalued.
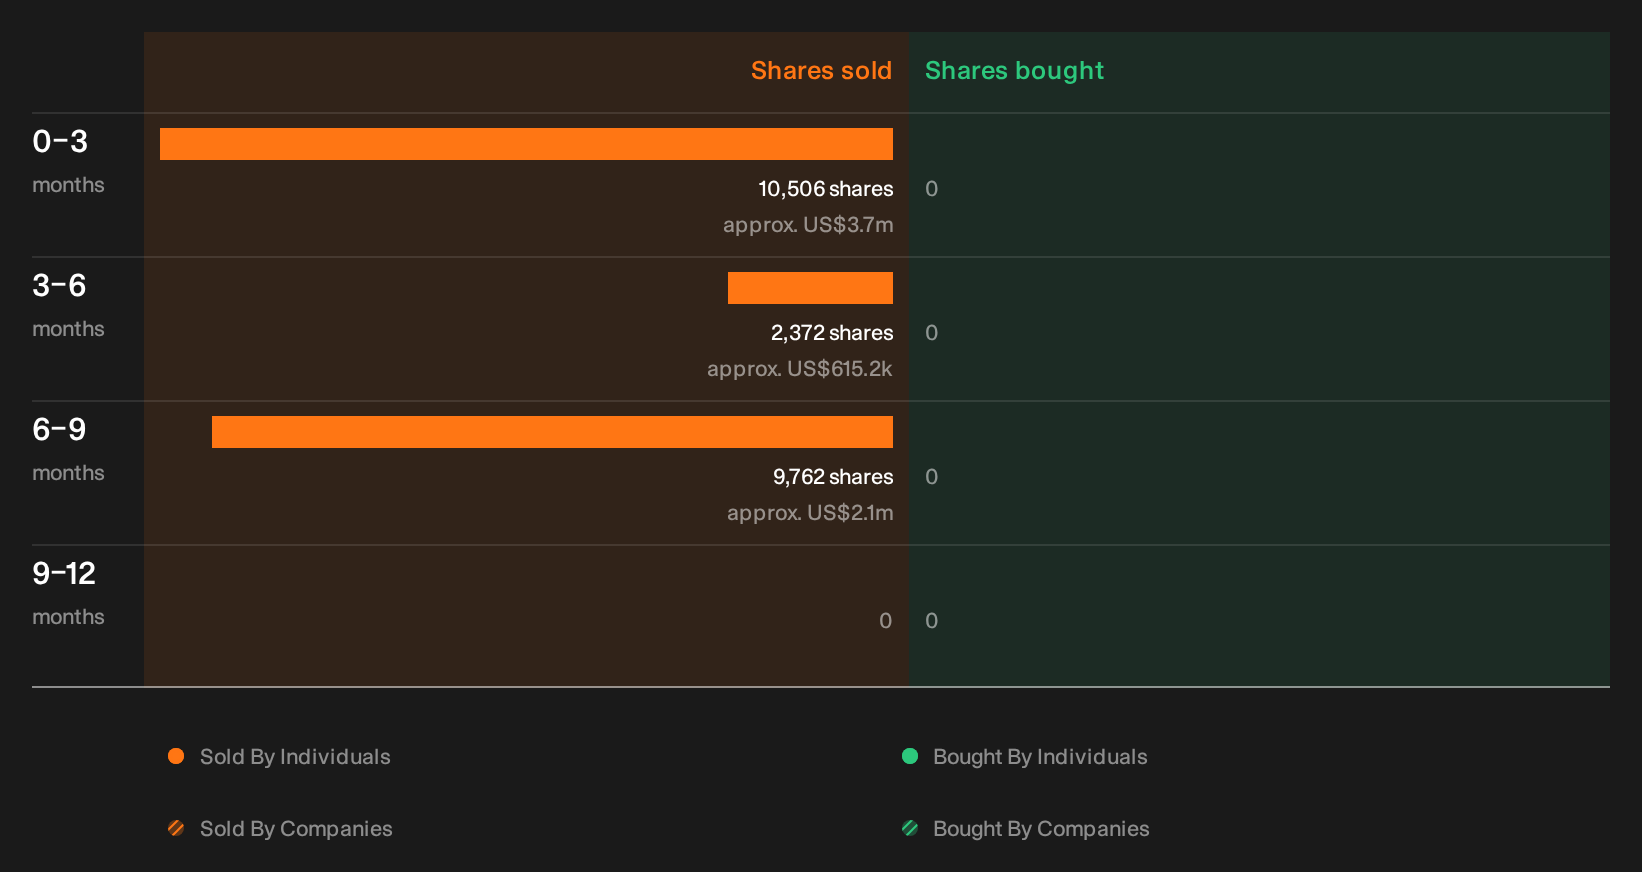
Marathon Petroleum’s price is only one signal, the insider moves are another
Valuation only tells part of the story for Marathon Petroleum, and recent management share sales flagged by our checks raise a separate question about who is trimming exposure and by how much. See the recent insider selling flagged for Marathon Petroleum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com