
CG Oncology (CGON) CCO Hire Puts Its Launch Valuation Narrative To The Test
CG Oncology (CGON) has put commercial execution in sharper focus after appointing industry veteran Isabel Kalofonos as Chief Commercial Officer. The move is tied directly to preparations for a possible cretostimogene grenadenorepvec launch.
For context, CG Oncology shares trade at US$62.24, with the stock delivering a 48.94% year to date share price return and a 48.51% total shareholder return over the past year. This comes even after a 20.46% decline in the 30 day share price, which suggests some of the earlier momentum has cooled as investors reassess execution risk ahead of a potential launch.
Scan how other late-stage biotechs with fresh commercial leadership are setting up for potential launches by reviewing the hand-picked 21 high quality undiscovered gems that share similar execution questions.
CG Oncology now appears positioned between two narratives. One suggests that the commercial build, leadership hire and pullback could create room for additional upside. The other contends that most of the valuation already reflects that setup.
Most Popular Narrative: 32% Undervalued
On Simply Wall St’s most followed narrative, CG Oncology’s fair value sits at $91.08 compared to the last close at $62.24. This frames today’s pullback as a valuation gap rather than a completed story.
The main thing that has to go right is successful execution on late stage trials and regulatory submissions alongside scaling virus manufacturing and a lean urology focused commercial build.
The current valuation implies that the market is placing limited value on cretostimogene’s potential reach across more than 100,000 NMIBC patients per year and on CG Oncology’s cash position of about US$1.0 to US$1.1 billion with no debt and runway guided through 2029.
See why 2 investors see CG Oncology as 32% undervalued.
Result: Fair Value of $91.08 (UNDERVALUED)
Still, the narrative can break if regulators or payers push back on cretostimogene pricing or if operating costs stay high and delay any path to profitability.
Find out about the key risks to this CG Oncology narrative.
Another View: What CG Oncology’s P/B Ratio Signals
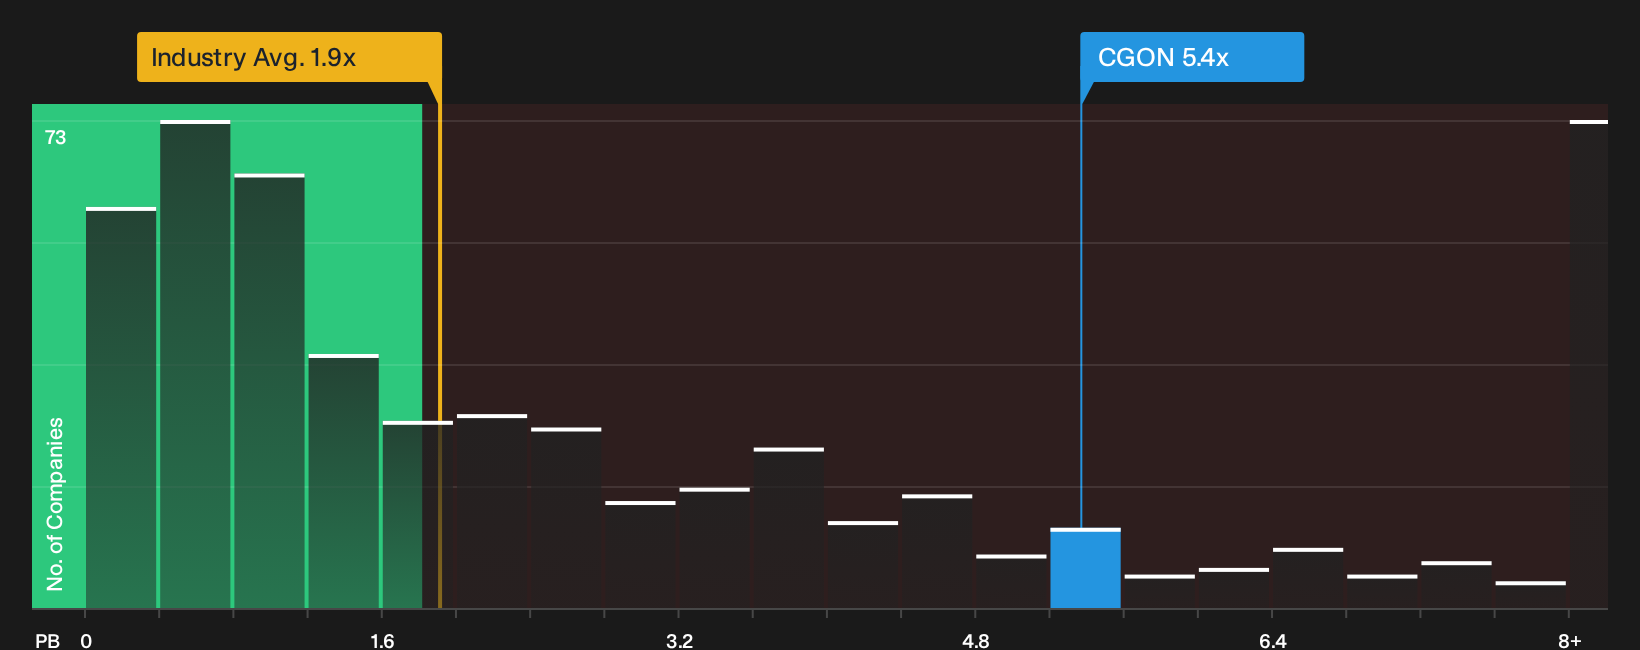
The story looks very different when you shift from fair value estimates to today’s P/B. CG Oncology trades at 5.4x book value compared with 1.9x for the wider US biotechs group and 12.6x for its peer set. That mix can point to either pricing power or valuation risk. Which side do you think it leans toward?
To see how this price tag lines up against the underlying numbers and what that gap might mean for future upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Here is how CG Oncology’s current multiple stacks up visually against sector peers, which can help you judge whether that premium feels justified based on your own thesis.
Next Steps
Wondering whether current enthusiasm around CG Oncology matches the risk and reward mix on the table today? Move quickly, review both sides of the data, then weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond CG Oncology?
Do not stop with CG Oncology alone. Broaden your watchlist now so you can compare this story against other opportunities before the next round of catalysts hits.
- Target resilient opportunities that aim to keep drawdowns in check by scanning a 31 resilient stocks with low risk scores built around lower risk profiles.
- Hunt for quality at a discount by reviewing a curated 33 high quality undervalued stocks that blend strong fundamentals with pricing that may not fully reflect them.
- Build staying power into your portfolio by checking a list of solid balance sheet and fundamentals (25 results) that highlights companies with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com