
How Domestic Aluminum Expansion At Century Aluminum Stock Has Changed Its Investment Story
- Century Aluminum is ramping up U.S. primary aluminum capacity through restarts at Mt. Holly and a planned large smelter in Inola, Oklahoma, supported by existing Section 232 tariffs that affect import costs.
- The company is being framed as a national security supplier, with retired Gen. David Petraeus and the American Primary Aluminum Association highlighting its role in military grade aluminum and domestic supply resilience.
- This article examines how Century Aluminum's investment narrative is influenced by its Oklahoma smelter plans and the national security positioning.
Scan for other defense linked materials producers with tariff tailwinds by reviewing our curated 33 best rare earth metal stocks, which sit alongside Century Aluminum in the broader critical metals story.
Century Aluminum Investment Narrative Recap
For Century Aluminum, the big idea you would need to buy into is pretty simple. The business is leaning into being a U.S. centric primary aluminum supplier, with restarts at Mt. Holly and the planned Oklahoma smelter intended to turn that positioning into higher volumes over time. The Petraeus comments and Section 232 focus matter to this story because they support the frame of aluminum as critical infrastructure, not just a commodity.
In the near term, the key swing factor still looks like how well new and restarted capacity is executed while keeping a grip on costs, especially at more complex assets like Jamalco. The biggest operational risk is that premiums or supply tightness soften while Century Aluminum is in spend mode on Oklahoma and ramp ups, which would leave the business more exposed to any margin pressure.
The most relevant recent development linked to this national security angle is the executive order that lets the planned Oklahoma project access up to 300,000 tonnes per year of lower tariff imports, in addition to existing Section 232 tariffs. When combined with Petraeus publicly flagging aluminum as a security concern, this creates a clearer policy framework around how this future capacity could be supplied and priced.
For you as a shareholder, that matters less as a headline and more as a potential support for the project economics. If Oklahoma progresses as outlined, it connects to a broader list of potential catalysts, including higher potential shipments, better absorption of fixed costs and a more integrated energy and alumina chain. The flip side is straightforward. Any change in tariff treatment, import rules or execution timing could weaken that catalyst and keep Century Aluminum more dependent on current plants and existing premiums for earnings power.
Century Aluminum Consensus Targets In Context
Century Aluminum's analyst narrative points to revenues of US$4.7b and earnings of US$1.2b by 2029. That outlook is built on forecast revenue growth of 20.9% per year and an earnings step up of about US$597m from US$603.0m today.
Uncover why Century Aluminum's fair value indicates a potential 89% upside to its current price before that discount narrows.
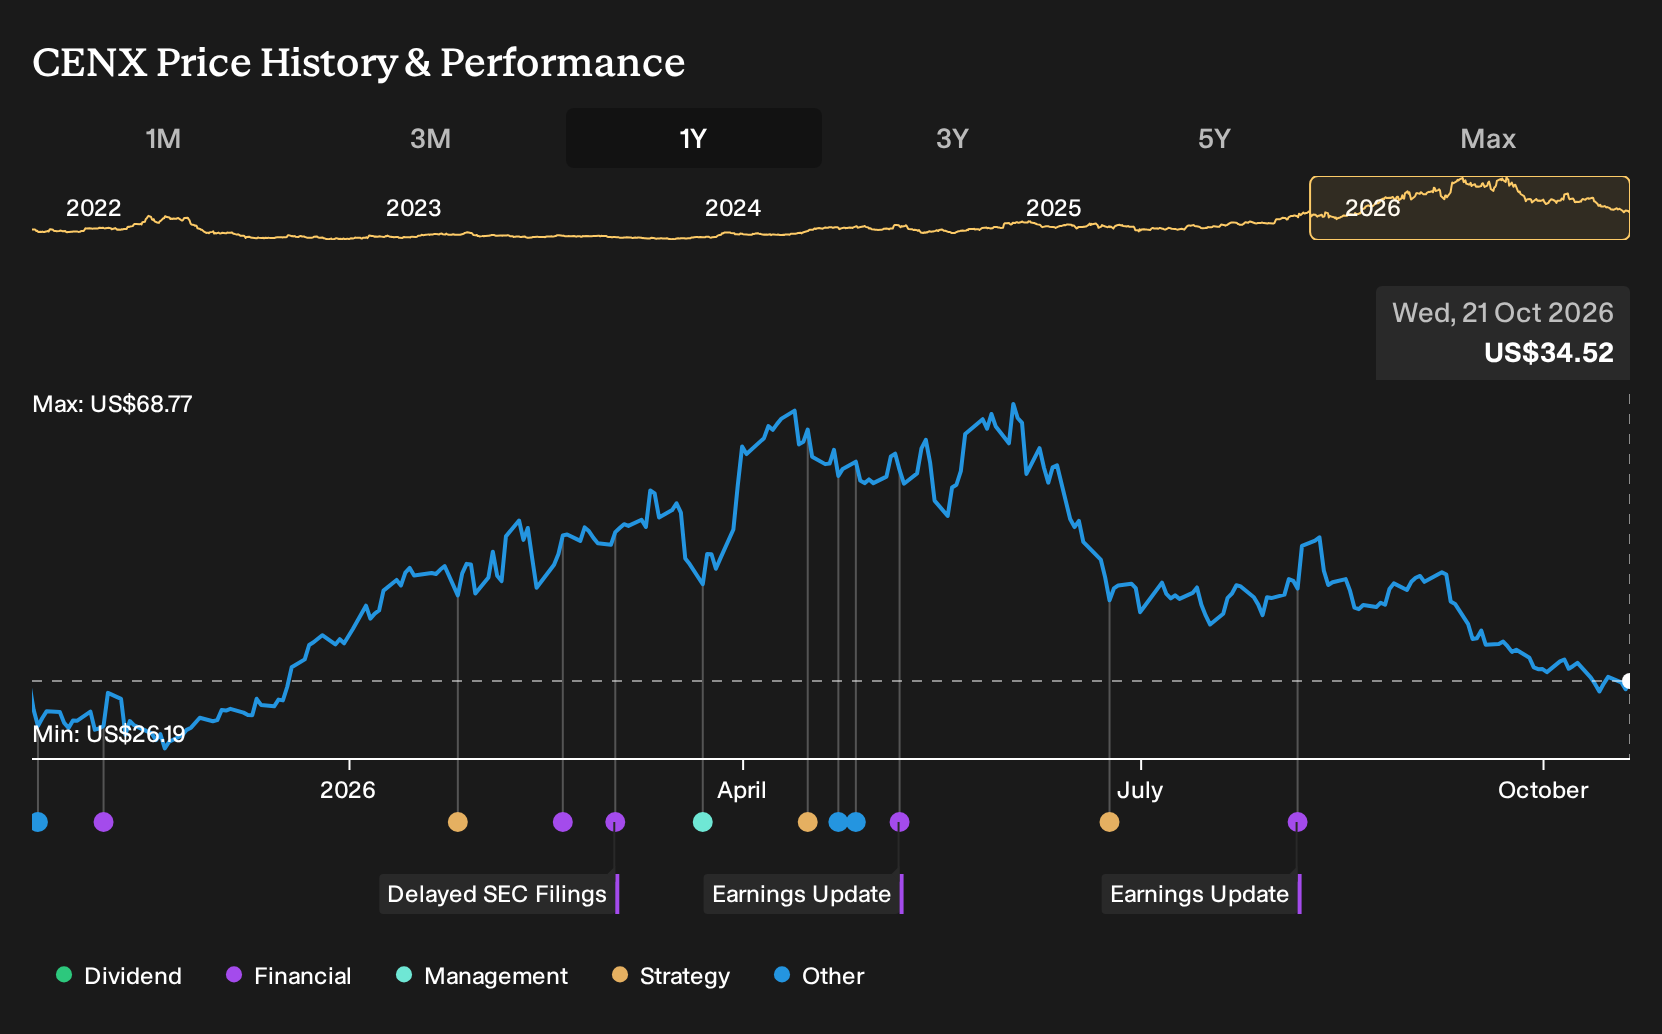
Exploring Other Perspectives
You might focus on Century Aluminum’s tariff and tax credit support, while the most optimistic analysts fixate on earnings potential. Before this news, the bullish camp was sketching out about US$4.7b of revenue and US$1.5b of earnings by 2029. Those views could shift as the national security story evolves. Compare several angles before deciding anything.
Explore 4 other Century Aluminum fair value estimates, including one that suggests a potential upside of as much as 448% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Century Aluminum research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Century Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Century Aluminum's overall financial health at a glance.
Looking For More Ideas Beyond Century Aluminum?
Once you have a view on Century Aluminum, it can help to widen the lens and compare it with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener lets you filter for traits that matter to you, then stack those candidates against what you see in this stock.
- For investors who care most about paying less than they think a business is worth, start with a focused group of 33 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- If capital preservation and stability are higher on your list than rapid gains, narrow your search to a 31 resilient stocks with low risk scores that screens for resilience based on a range of financial risk checks.
- When you want potential upside but still care about balance sheet strength, filter the market for a 21 high quality undiscovered gems that flags companies with solid fundamentals that are not widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com