
Top 3 Canadian Undervalued Stocks With P E Under 9
Oil prices jumping above $111 on fresh Middle East conflict risk has pushed energy back to centre stage for Canadian investors. When headlines lock onto crude, many small but solid Canadian businesses get ignored as money crowds into the obvious trades. That neglect can create mispricing. This piece walks through three high quality under the radar Canadian stocks that score well on balance sheet strength and fundamentals from our high quality undiscovered gems filter.
The three stocks that follow are only a sample from this idea, and the full screen surfaced 7 more Canadian companies with equally compelling stories that are not covered below. To see the broader field and identify which ones might deserve a place on your watchlist, head straight into the High-Quality Undiscovered Gems screener.
Yellow Pages (TSX:Y)
Yellow Pages is a small Canadian marketing group that now focuses on digital tools for local lead generation, while still running its long standing print directories. It generated about $191 million from its Yellow Pages segment in Canada and has a market value of roughly $163 million.
Yellow Pages ties directly into the High Quality Undiscovered Gems theme through its digital marketing services for small businesses, pairing tools like YP.ca placement and social campaigns with a P/E of 8.7x and a 10% net margin. The quality narrative now depends more on how the decline in print interacts with that high return profile.
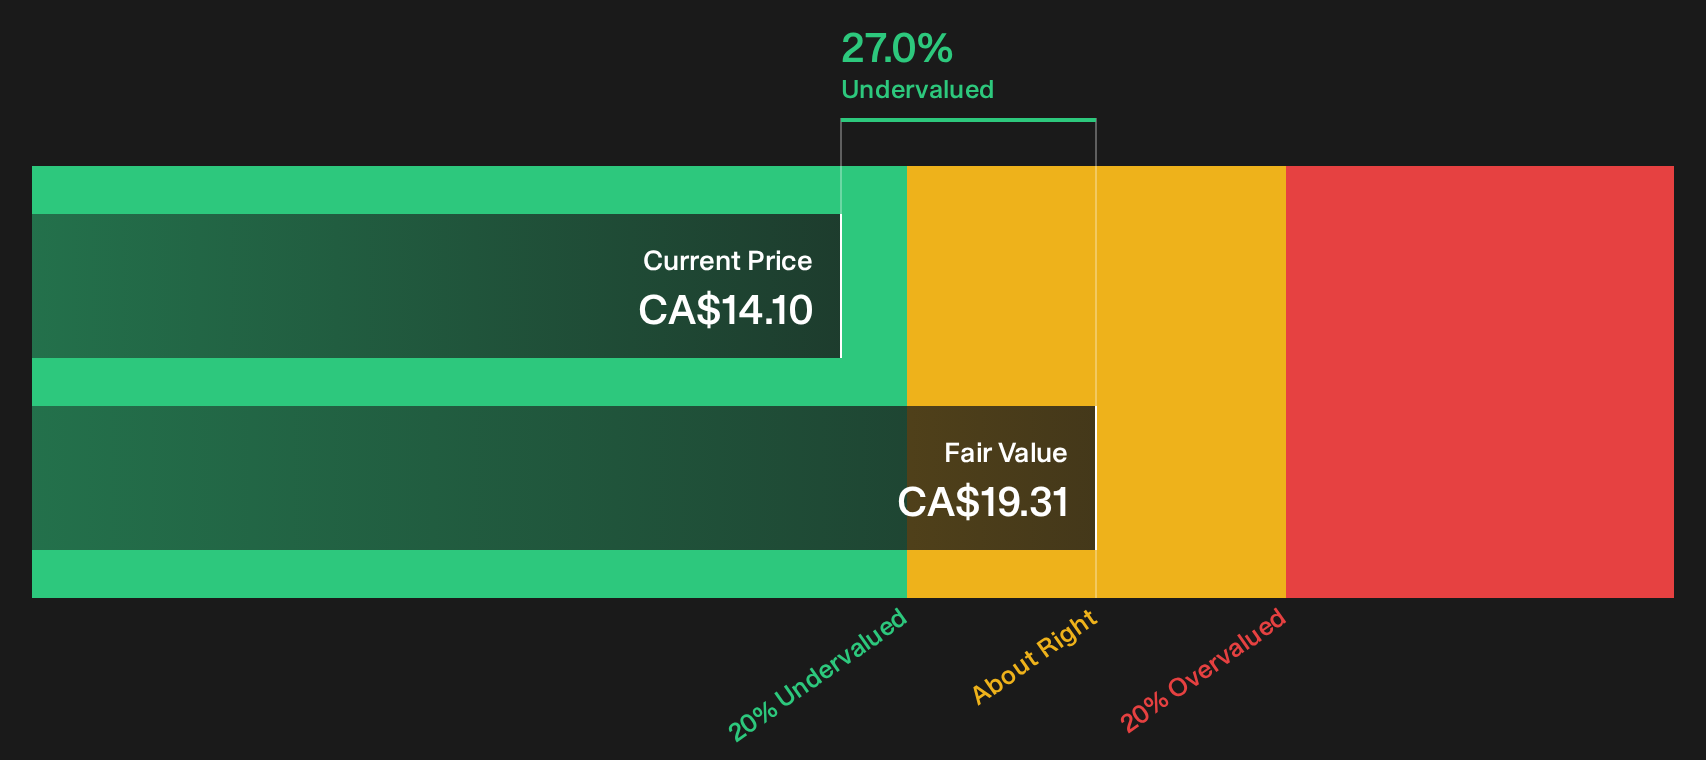
That trade off sits at the centre of the story, and the DCF valuation analysis for Yellow Pages shows how far that high return profile is already baked in.
Torex Gold Resources (TSX:TXG)
Torex Gold Resources is a mid cap miner built around the 100% owned Morelos Complex in Guerrero, Mexico, which generated about $1.8b of revenue and anchors its status as a potential high quality gem. Its CA$6.8b market value keeps it off many large fund radars.
Torex Gold Resources fits this High Quality Undiscovered Gems theme through a single, sizeable gold hub that already produces, is still being expanded and continues to draw fresh capital into exploration around it.
"Successful completion and ramp-up of the Media Luna project, now supported by underground mining rates ahead of plan at Media Luna and ELG and on-schedule progress toward first ore at Media Luna North by late 2026, is set to materially increase production volumes and extend mine life, supporting long-term revenue growth and cash flow stability."
What really tests that potential upside is one pressure point on future margins that still needs to move in Torex Gold Resources' favour.
That margin swing is exactly what the full narrative for Torex Gold Resources unpacks, showing how Torex Gold Resources could turn today’s pressure into accelerating cash generation potential beyond the current mine plan.

Fortuna Mining (TSX:FVI)
Fortuna Mining is a Vancouver based precious and base metals producer anchored by the Lindero and Séguéla gold mines, with extra upside potential from the Bambadji exploration project. It generated about $680 million from Sango, $357 million from Mansfield and $145 million from Bateas, and has a market value near $4.3b.
For the High-Quality Undiscovered Gems theme, Fortuna Mining brings operating gold mines plus a growing West Africa pipeline that can matter for investors who want smaller producers with real assets rather than just drill stories.
"Expansion at Seguela and the development of Diamba Sud position Fortuna to restore and surpass its previous production levels, with higher-margin and longer-life ounces, aligning with anticipated increases in global demand for gold and other strategic metals, which could support future revenue and cash flow growth."
What comes next for Fortuna Mining largely turns on how one pressure point shapes future all in costs and the cash that eventually reaches shareholders.
That “all in cost” question is exactly what the full narrative for Fortuna Mining unpacks, revealing how Fortuna Mining could turn future cost pressure into accelerating cash generation potential.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time momentum headlines hit, the cleaner balance sheets and quiet breakout stories can already be flying. Scan what others miss while it matters and get in early.
- Spot cash rich balance sheets before they catch mainstream attention by running the list of solid balance sheet and fundamentals (7 results) and see which businesses still trade like the market has not noticed.
- Track income focused opportunities that aim to keep paying investors even when prices swing by reviewing the curated set of 3 dividend fortresses built for consistency seekers.
- Zero in on gold producers that could benefit if sentiment rotates into hard assets by combing through the hand picked 35 elite gold producer stocks and judge the setups for yourself.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com