
Is ATCO (TSX:ACO.X) Still Undervalued Following Its Recent Share Price Jump?
ATCO (TSX:ACO.X) recently drew fresh attention after a share price move that left the stock up about 9% over the past month. This has prompted investors to reassess its recent financial profile and valuation.
That 9.4% 1 month share price return sits alongside a 41.1% year to date share price gain and a 51.5% 1 year total shareholder return, which together point to momentum that investors appear to be pricing into ATCO’s story after a more muted 90 day patch.
Scan beyond ATCO’s recent surge and compare it with a hand picked 8 resilient stocks with low risk scores that may appeal if you are focusing on steadier profiles with lower risk scores.
Bulls see ATCO’s recent run as overdue recognition of its diversified operations. Bears see investors overreacting to short term momentum. The valuation work now needs to show which side the current price better reflects.
Most Popular Narrative: 12% Undervalued
On the narrative view, ATCO’s fair value sits at about CA$91 per share, a touch above the recent CA$79.82 close. This frames the current optimism as still leaving some upside on the table rather than fully pricing in the story.
Robust long-term demand for modular and affordable housing, driven by government policy and urbanization, positions ATCO to capitalize on significant infrastructure investment initiatives in Canada and internationally. Recent government commitments and ATCO's scalable modular manufacturing capacity are likely to translate to higher revenue growth over the next several years.
See why 34 investors see ATCO as 12% undervalued.
Result: Fair Value of CA$91 (UNDERVALUED)
Still, the narrative can unravel quickly if higher debt servicing costs squeeze ATCO’s margins, or if expected government backed housing and infrastructure contracts fail to materialize.
Find out about the key risks to this ATCO narrative.
Another View: ATCO Looks Expensive On Earnings
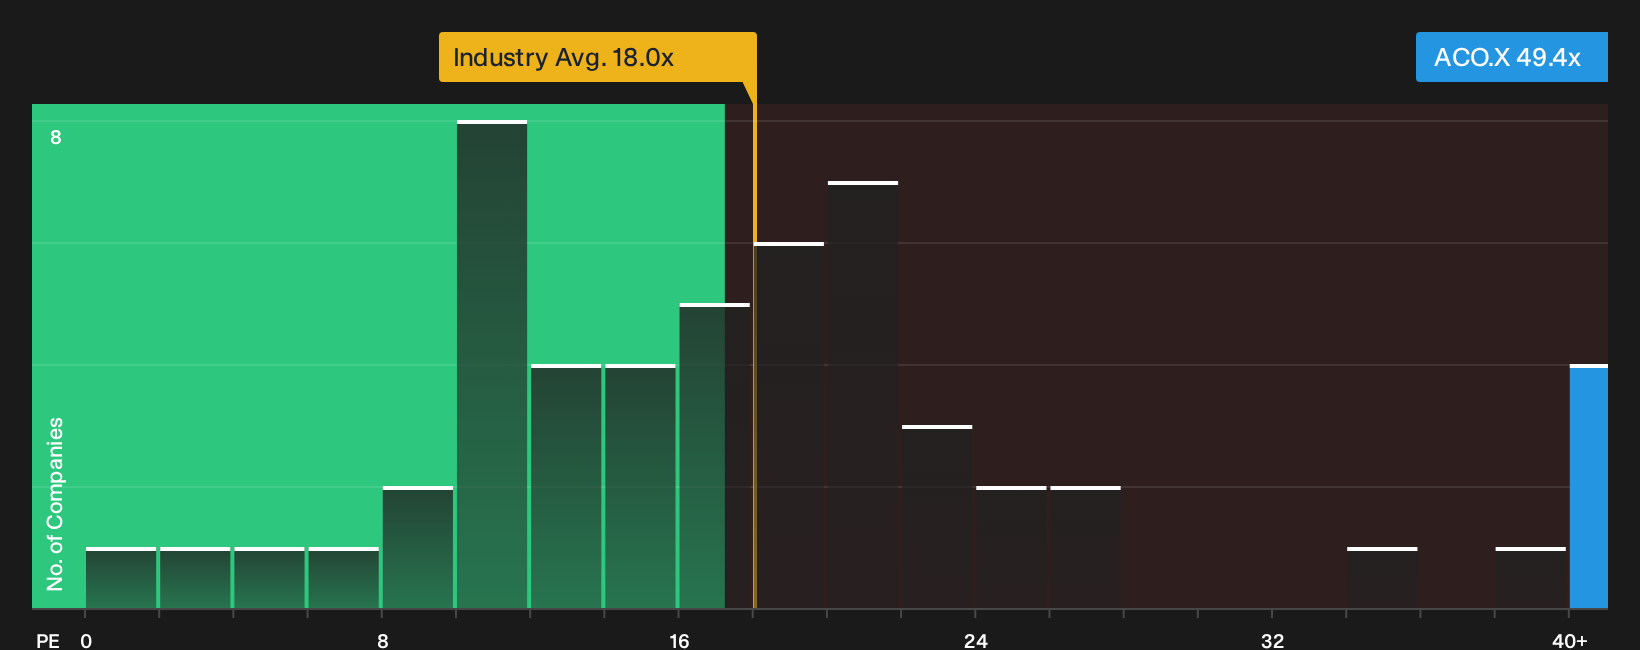
On a simple earnings yardstick, ATCO tells a different story. The stock trades on a P/E of 49.4x, compared with a fair ratio of 39.6x, peer levels at 40.7x and a global integrated utilities average of 17.9x. That gap points to valuation risk if sentiment cools.
Our DCF work suggests modest undervaluation, yet this earnings multiple argues investors are already paying up for the story. The question is which yardstick you trust more when momentum fades.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Have mixed views on ATCO after all this, or leaning one way? Consider acting before sentiment shifts and test the numbers yourself, starting with 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond ATCO?
If ATCO has sharpened your appetite for opportunity, do not stop here. Broaden your watchlist with new angles, sectors and risk profiles using the Simply Wall St screener.
- Target resilient balance sheets and steadier financial profiles by starting with a curated list of solid balance sheet and fundamentals (7 results) that can help anchor your portfolio.
- Hunt for quality at a discount by scanning a focused 4 high quality undervalued stocks that highlights companies where fundamentals and pricing may be misaligned.
- Turn income into a core pillar of your approach by reviewing a hand picked 3 dividend fortresses that prioritizes higher yields with supporting metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com