
First Community (FCCO) Q3 Earnings Flash Stronger Profit Than Stock Reaction
First Community came into this Q3 2026 report with a reputation as a quietly efficient regional lender priced at a modest 11.9x trailing P/E and offering a 2.08% dividend yield. The stock barely budged on the numbers, ticking up just 0.5% to US$32.77. Yet the headline result was far stronger than that muted move suggests.
Earnings per share reached US$0.86 for the quarter, and trailing twelve month profit stood at US$25.97 million, pointing to earnings power that looks more robust than the one day share price reaction implies.
If you appreciate the earnings strength at First Community but prefer a broader set of regional lenders with comparable income characteristics on your radar, consider comparing it against the curated group in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$25.28m vs. US$20.07m (up about 25.9%)
- Net Income (Q3 2026 vs Q3 2025): US$8.04m vs. US$5.19m (up about 54.9%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.86 vs. US$0.68 (up about 26.8%)
- Net Interest Margin (Q3 2026 vs Q3 2025): 3.51% vs. 3.27% (higher margin on earning assets)
Ask Charlie what makes First Community’s earnings growth look durable.
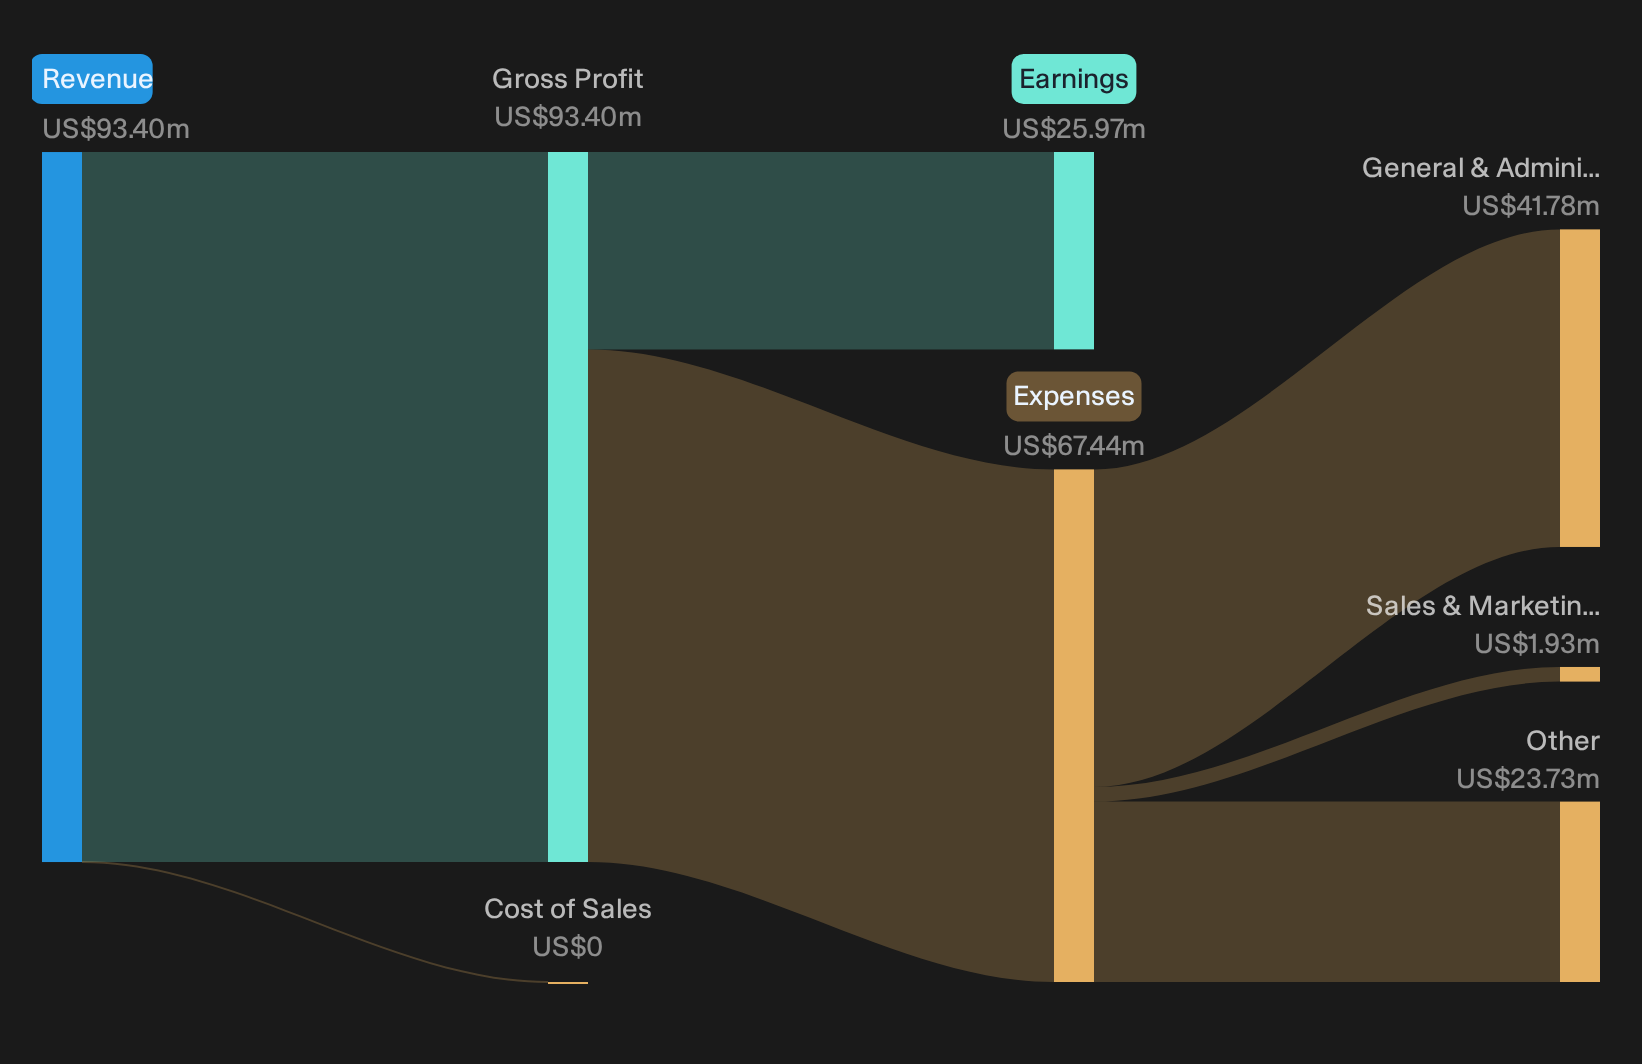
First Community earnings that support a bullish view
For anyone leaning positive on First Community, this quarter gives the relationship-banking story some real backing. Revenue of US$25.28m and net income of US$8.04m both moved ahead of last year, while basic EPS reached US$0.86. A higher net interest margin at 3.51% versus 3.27% suggests the lending franchise is holding its own on pricing and funding. That mix of stronger profitability and healthier spread income fits a thesis built on a diversified, community-focused bank that can still generate solid earnings from its local footprint.
First Community risks that still worry cautious investors
Even with better profit metrics, cautious readers will notice the share price barely moved, up just 0.5% on the day. Recent 30 day and 90 day returns are both slightly negative, which tells you investors remain hesitant to fully reward the stronger quarter. The modest market reaction hints at lingering concerns about regional concentration, competition from larger and digital rivals, or future credit costs, even if those worries do not yet show up directly in the latest income statement.
Are investors overestimating how much First Community's improved net interest margin can support future performance, or are analysts even more optimistic? See the consensus price target analysis for First Community.Hunt For Quietly Mispriced Earnings
First Community recently released stronger earnings while the share price showed little movement. The real opportunity could be in stocks that the market has not fully revalued yet.
- Company 1 - 23% below our estimate - sells grid testing equipment utilities may order as electricity networks are upgraded.
- Company 2 - 39% below our estimate - runs device trade-in and refurbishment programs that convert recycling subsidies into repeat recommerce transactions.
- Company 3 - 30% below our estimate - supplies accelerated computing platforms that cloud providers purchase to support new AI-focused data centers.
Three companies from the same screener. Open all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com