
How AI Networking Expansion Will Impact Cisco (CSCO) Stock
- Cisco Systems recently outlined new Silicon One chips, deep-buffered systems, optics and SONiC-based architectures aimed at AI data centers and distributed AI fabrics, alongside expanded hyperscaler deployments and future product shipments running through 2027.
- The tie up with NVIDIA and partners on the Ultra-Dense Small Form Factor Pluggable optical standard points to Cisco pursuing tighter control over AI networking hardware building blocks and supply, which directly affects its cost profile and product differentiation in large AI infrastructure deals.
- We will now look at how Cisco's push into vertically integrated AI networking silicon and optics could reshape its broader investment narrative.
Cisco Systems Investment Narrative Recap
To own Cisco Systems today, you need to believe the firm can turn its AI centric networking push into durable earnings while keeping hardware driven margin pressure under control. The main short term swing factor is how efficiently Cisco converts its US$9.3b AI order book and broader network refresh demand into revenue through FY27.
The biggest risk sits in the same place. A heavier hardware mix, higher memory costs and any security incidents on Cisco infrastructure could squeeze non GAAP gross margin further or slow orders. The latest silicon and optics news mainly reinforces the existing AI build out story rather than changing those near term drivers.
The most relevant update is Cisco’s new Silicon One based AI networking stack, including 51.2T systems already in production with hyperscalers and 102.4T G300 sampling with shipments underway. These deployments, together with expanded AI optics, directly relate to the US$7.5b of AI infrastructure revenue Cisco has guided to for FY27.
For you as a shareholder, the main operational question is execution. If Cisco ramps 51.2T and future 51.2T top of rack silicon such as G302 on time and manages supply, the AI cycle can help offset gross margin headwinds. Any slippage in delivery, ecosystem adoption or SONiC based architectures would make existing concerns over hardware mix and valuation more pointed.
Cisco Systems' current analyst narrative points to US$83.4b in revenue and US$20.1b in earnings by 2029, built on an assumed 9.6% yearly revenue growth rate and an increase in profit from US$13.3b today to that US$20.1b figure. This represents roughly a 50% uplift in earnings over the period.
Uncover how Cisco Systems' fair value indicates a 28% potential upside to its current price that may not continue for long.
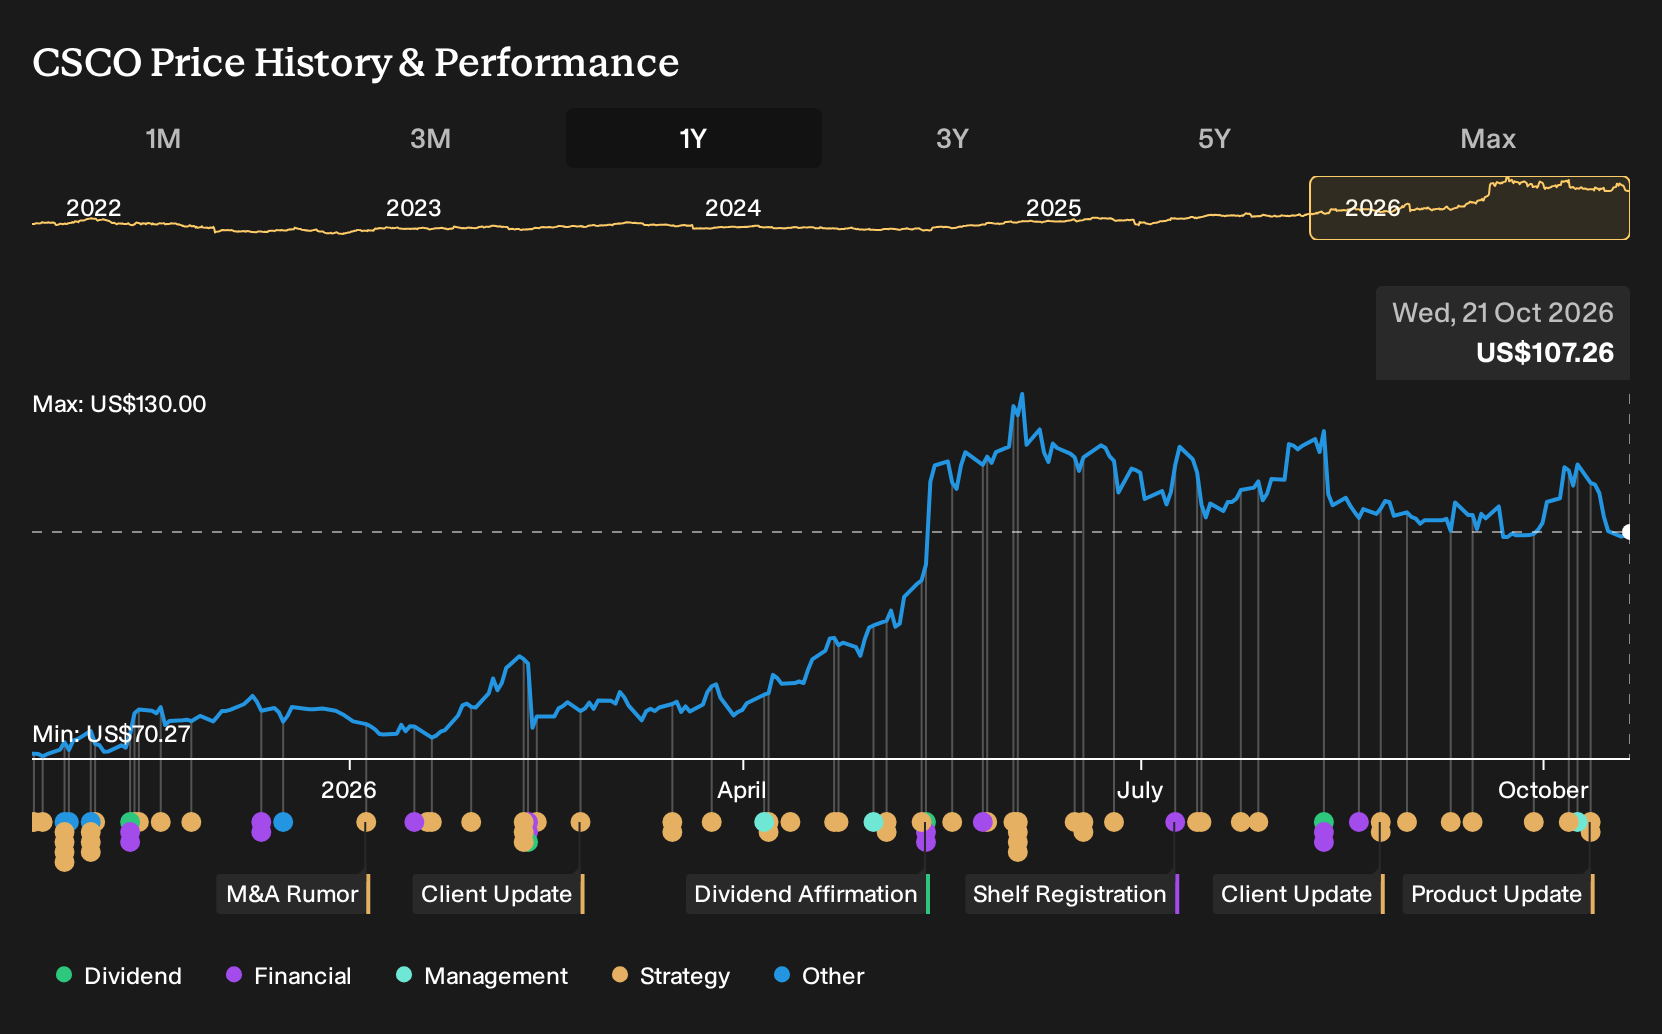
Exploring Other Perspectives
You have a very different story if you focus on one alternate concern. The more cautious analysts worry that Cisco Systems is leaning too hard on a narrow group of AI hyperscalers. Their scenario is built on revenue reaching about US$78.0b and earnings of US$19.3b by 2029. Those figures sit below the consensus view and support a lower US$110.0 price target, so the fresh silicon and optics news could push that narrative closer to or further from reality as forecasts get refreshed.
Explore 5 other Cisco Systems fair value estimates, including one that suggests it could be worth just $110.56.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cisco Systems research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking for more investment ideas beyond Cisco Systems?
If Cisco Systems has sharpened your focus on AI infrastructure and resilient business models, it can be useful to widen the lens and compare it with other opportunities on the market using the Simply Wall St Screener.
- For readers who want potential mispriced opportunities with solid fundamentals, start by scanning a 21 high quality undiscovered gems that might not yet be on everyone’s radar.
- If capital preservation and steadier profiles matter most to you, filter for 31 resilient stocks with low risk scores that score well on resilience and financial robustness.
- When balance sheet strength is a priority, focus on companies in our list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial discipline with durable operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com