
Should Lithium Project PEA Require Action From Equinor (OB:EQNR) Investors?
- Standard Lithium, together with Equinor, has filed a positive Preliminary Economic Assessment for the Franklin lithium project in East Texas. The assessment outlines up to 70,000 tonnes per year of battery grade lithium carbonate over a modelled 20 year life and recommends progression to a Preliminary Feasibility Study.
- The Franklin report gives Equinor a potential entry point into large scale lithium chemicals, with high grade brine resources, direct lithium extraction testing, and optional bromine and potash revenue streams that could reshape how its future cash flows are split between hydrocarbons and energy transition materials.
- This development raises the prospect that Equinor's investment narrative could shift as the large scale Franklin lithium PEA reframes its energy transition optionality.
Equinor Investment Narrative Recap
To own Equinor, you need to be comfortable with a business still anchored in oil and gas while gradually adding transition projects. The key near term driver remains reliable production and cash generation from the Norwegian Continental Shelf and international fields, supported by long term gas contracts and disciplined spending.
The biggest risk is that earnings, which analysts expect to decline on average over the next few years, soften faster than capital and transition plans adjust. The Franklin lithium PEA is interesting but does not change that near term picture. It looks incremental to the core hydrocarbon and renewables story for now.
The Franklin lithium assessment matters most when viewed alongside Equinor’s broader energy transition portfolio. It adds another potential stream of future cash flow tied to critical minerals, alongside offshore wind and low carbon projects, rather than replacing the existing oil and gas engine that still provides the bulk of revenue today.
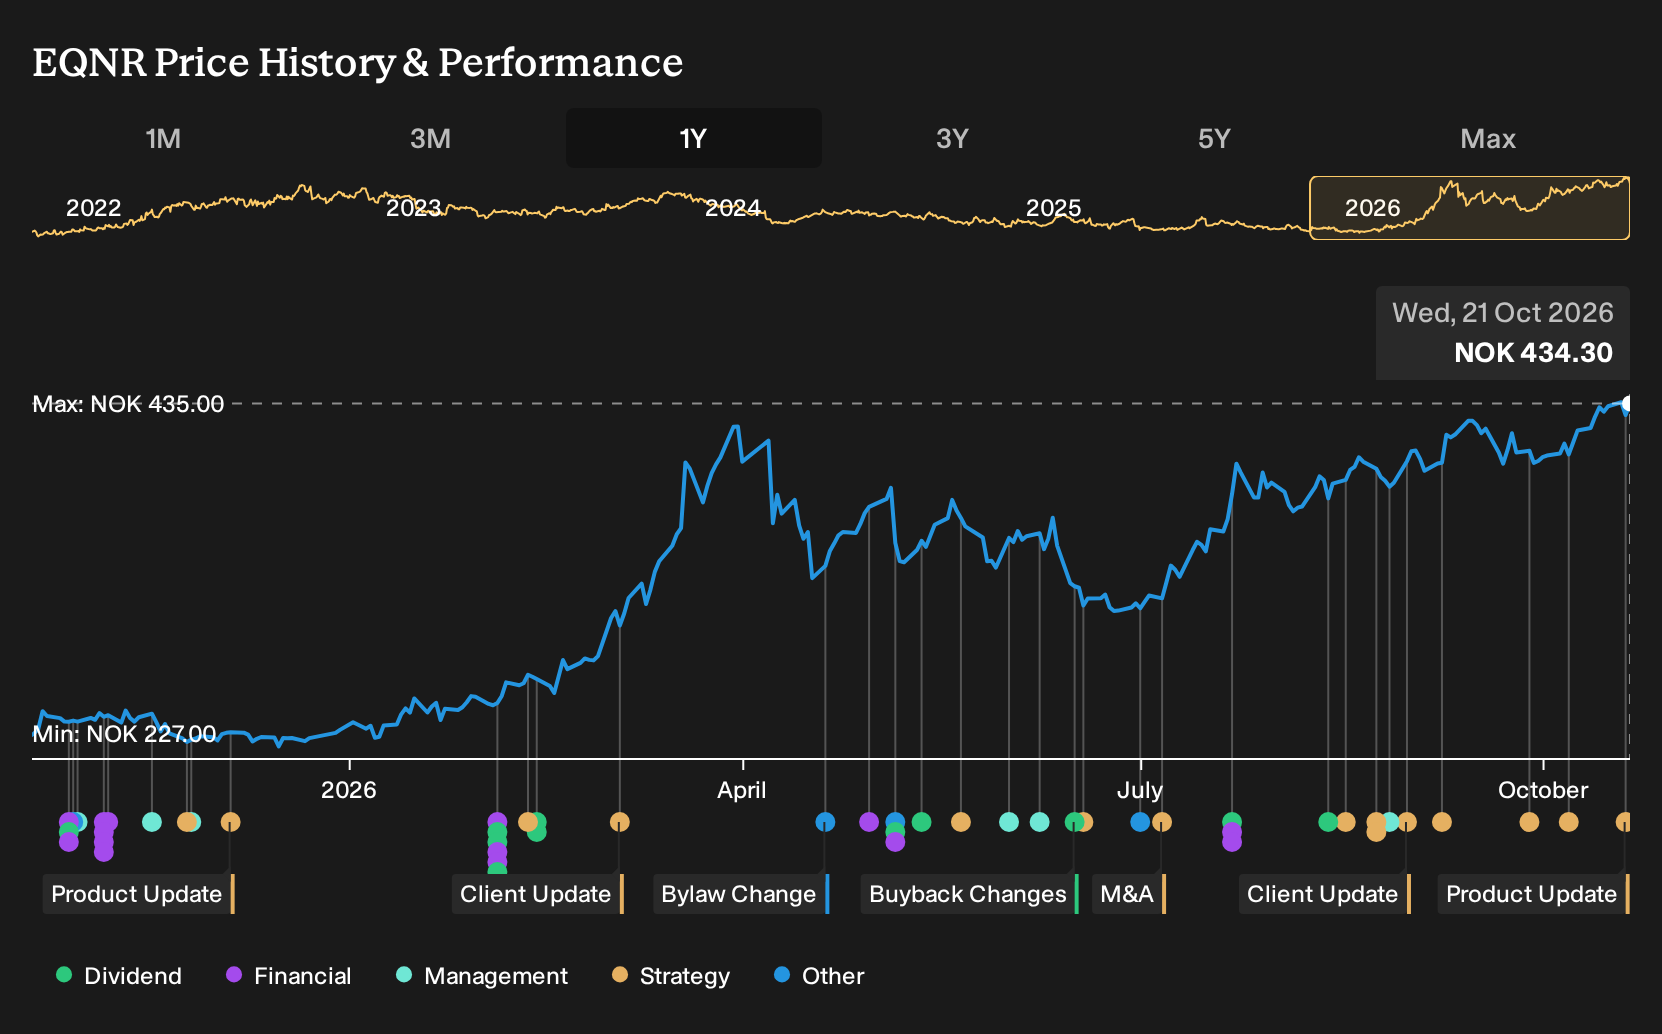
Among recent developments, the ongoing 2026 share buyback programme is the clearest operationally relevant counterpoint. Active repurchases and incentive related buybacks show that Equinor is still prioritising capital returns. At the same time, it commits to long dated projects like Franklin, which concentrates execution risk around keeping legacy assets productive as new ventures mature.
Equinor's current analyst script points to revenues of $96.2b and earnings of $7.8b by 2029, based on a projected 5.4% yearly decline in revenue and a move from $9.1b in earnings today to that 2029 consensus, which is a reduction of $1.3b rather than an increase.
Uncover why Equinor's fair value indicates a 13% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts already saw Equinor as a quiet compounding story, not a moonshot, with revenue assumptions of about $122.3b and earnings around $9.8b by 2029. You can now ask whether a large lithium PEA becomes the extra catalyst those forecasters were missing. Views clearly differ. Use that spread to test your own thesis.
Explore 6 other Equinor fair value estimates, including one that suggests as much as 7% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Equinor research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Equinor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinor's overall financial health at a glance.
Looking For More Ideas Beyond Equinor?
Once you have a view on Equinor, the next step is to line it up against other opportunities so you can decide where your next dollar works hardest.
The Simply Wall St Screener helps you move from a single story to a full watchlist, filtered by the traits that matter most to you.
- If you care most about valuation and quality, use our hand picked 189 high quality undervalued stocks that pair solid fundamentals with prices that analysts consider appealing.
- If resilience and lower risk are higher on your checklist, scan a curated 227 resilient stocks with low risk scores that may help you reduce portfolio volatility.
- If you are hunting for less crowded opportunities, sort through a focused 617 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com