
Is Lucid Group (LCID) Undervalued As It Expands Into France?
Lucid Group (LCID) is pushing ahead with expansion in Europe as it prepares to open its first three French retail and service locations in early 2027, marking the start of a broader partner network rollout.
Lucid Group’s planned French rollout arrives after a tough stretch for the ticker, with the share price down 25% over the past month and about 71% year to date. The 1 year total shareholder return has declined roughly 83% and the 3 year total shareholder return is down more than 92%, signaling that investors remain cautious even as the business pushes ahead with new markets.
Explore other EV and auto stocks that may currently have stronger fundamentals than Lucid Group by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
After a slide this steep and with a fresh expansion plan on the table, Lucid Group now tempts bargain hunters while making others wonder whether waiting could offer a cleaner entry. How does the current valuation compare with that dilemma?
Most Popular Narrative: 58% Undervalued
Lucid Group last closed at $3.21, while the most followed valuation story points to a fair value of about $7.61. This frames the current sell off as a sizeable discount rather than just a weak chart.
The newly announced Uber and Nuro partnership, including a planned $300 million Uber investment and a commitment to deploy at least 20,000 Lucid Gravity vehicles as robotaxis over six years, is expected to open a large and fast-growing autonomous fleet market to Lucid, driving significant revenue expansion and potential margin improvement via technology licensing and high-volume fleet sales.
Lucid's accelerated vertical integration and securement of domestic supply agreements (e.g., with Graphite One and Panasonic) are reducing geopolitical supply chain risks, enabling more resilient production, cost control, and operational efficiencies that should support future gross margin improvement.
See why 185 investors see Lucid Group as 58% undervalued.
Result: Fair Value of $7.61 (UNDERVALUED)
Still, the narrative can break if deep losses persist or if fresh capital raises and potential dilution have a greater impact on how investors view Lucid Group.
Find out about the key risks to this Lucid Group narrative.
Another View: Lucid Group Looks Expensive On Sales
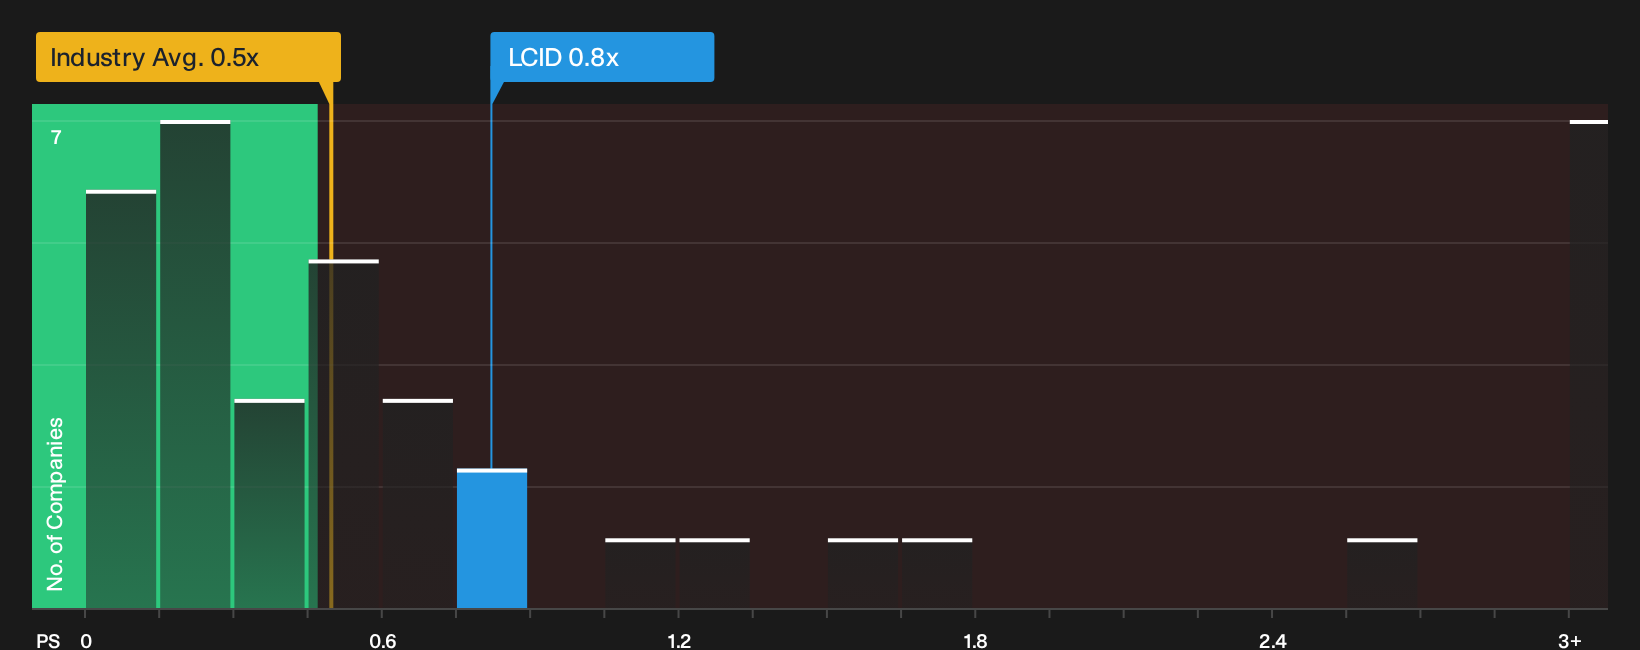
On the flip side of that $7.61 fair value story, Lucid Group screens as pricey on a simple sales multiple. The P/S ratio sits around 0.8x, compared with 0.5x for the wider US Auto group, while the fair ratio points to 0x. That gap suggests valuation risk if sentiment toward unprofitable EV makers weakens again.
For a closer look at how this pricing stacks up against fundamentals, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals can feel messy, especially with Lucid Group pulled between concern and optimism. Move quickly, review the data, and weigh the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Lucid Group?
If Lucid Group has you thinking harder about risk, reward, and timing, use this moment to widen your watchlist before the next setup passes you by.
- Target potential value opportunities early by scanning our hand picked pool of 33 high quality undervalued stocks that combine quality fundamentals with discounted pricing.
- Strengthen the defensive side of your portfolio by filtering for 31 resilient stocks with low risk scores that aim to keep volatility and financial red flags in check.
- Get ahead of the crowd by hunting through 21 high quality undiscovered gems that the broader market may not be focusing on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com