
Is Roblox (RBLX) A Bargain After Its 37% Slide In 2026?
Roblox has delivered a 69.0% gain over the past 3 years, even as the stock has struggled more recently. This raises a straightforward question for you as a shareholder or prospective buyer: Is the current US$52.55 share price still aligned with the cash the business can realistically generate in the years ahead?
- A 69.0% return over three years has reshaped the long term picture for Roblox, so any view on the stock today rests on how durable its future cash generation looks.
- Recent reports of weaker bookings, pressure on spending per player and ongoing legal challenges highlight how sensitive Roblox’s future cash flows may be to user behavior, regulatory outcomes and the need to keep producing viral hits like "Steal an Egg".
- Prefer to judge Roblox on sales? See why Roblox's 6.6x P/S tells a different valuation story.
The issue now is whether Roblox's current market value is justified by the cash flows implied by its intrinsic value estimate using a Discounted Cash Flow (DCF) approach.
If you want to stress test this same cash flow question beyond Roblox, you can compare it with a wider set of 33 high quality undervalued stocks
Does Roblox Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model looks at the cash Roblox can return to shareholders based on current and projected free cash flow. Roblox generated about $1.75b of free cash flow over the last twelve months, and the 2 Stage Free Cash Flow to Equity model then extends this with forecasts that imply growing cash generation into the early 2030s.
Those projections point to higher annual free cash flow by 2030 compared with today, so the DCF outcome sits meaningfully above the current $52.55 share price. The recent 2026 slide in the stock after weaker bookings guidance and legal uncertainty helps explain why the market is still pricing Roblox below what its cash flow profile suggests. Find out what Roblox could be worth using our Discounted Cash Flow (DCF) estimate.
The Roblox Narrative: What Would Justify Today's Price?
Narratives on Roblox pick up where the DCF question leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today, all in one place on Simply Wall St's Community page. Each scenario links its number to a clear view of how Roblox's user growth, margins and legal or business risks might shift, giving you something concrete to revisit as fresh information comes through.
Roblox holders on Simply Wall St are split between a product-led recovery story and a view that limited bookings visibility caps upside from here.
Bull case: 19% undervalued
"Some analysts with a positive view expect Roblox to turn current safety, AI creation and 18+ expansion efforts into a larger, more diversified bookings base over time..."
Discover why this Narrative puts Roblox at 19% undervalued.
Bear case: 5% overvalued
"Escalating costs, dependence on viral content, and competitive pressures risk long term profitability if user growth and monetization fail to match heavy investments and expansion ambitions..."
Explore why this Narrative puts Roblox at 5% overvalued.
One more question for Roblox that the cash flow model does not answer
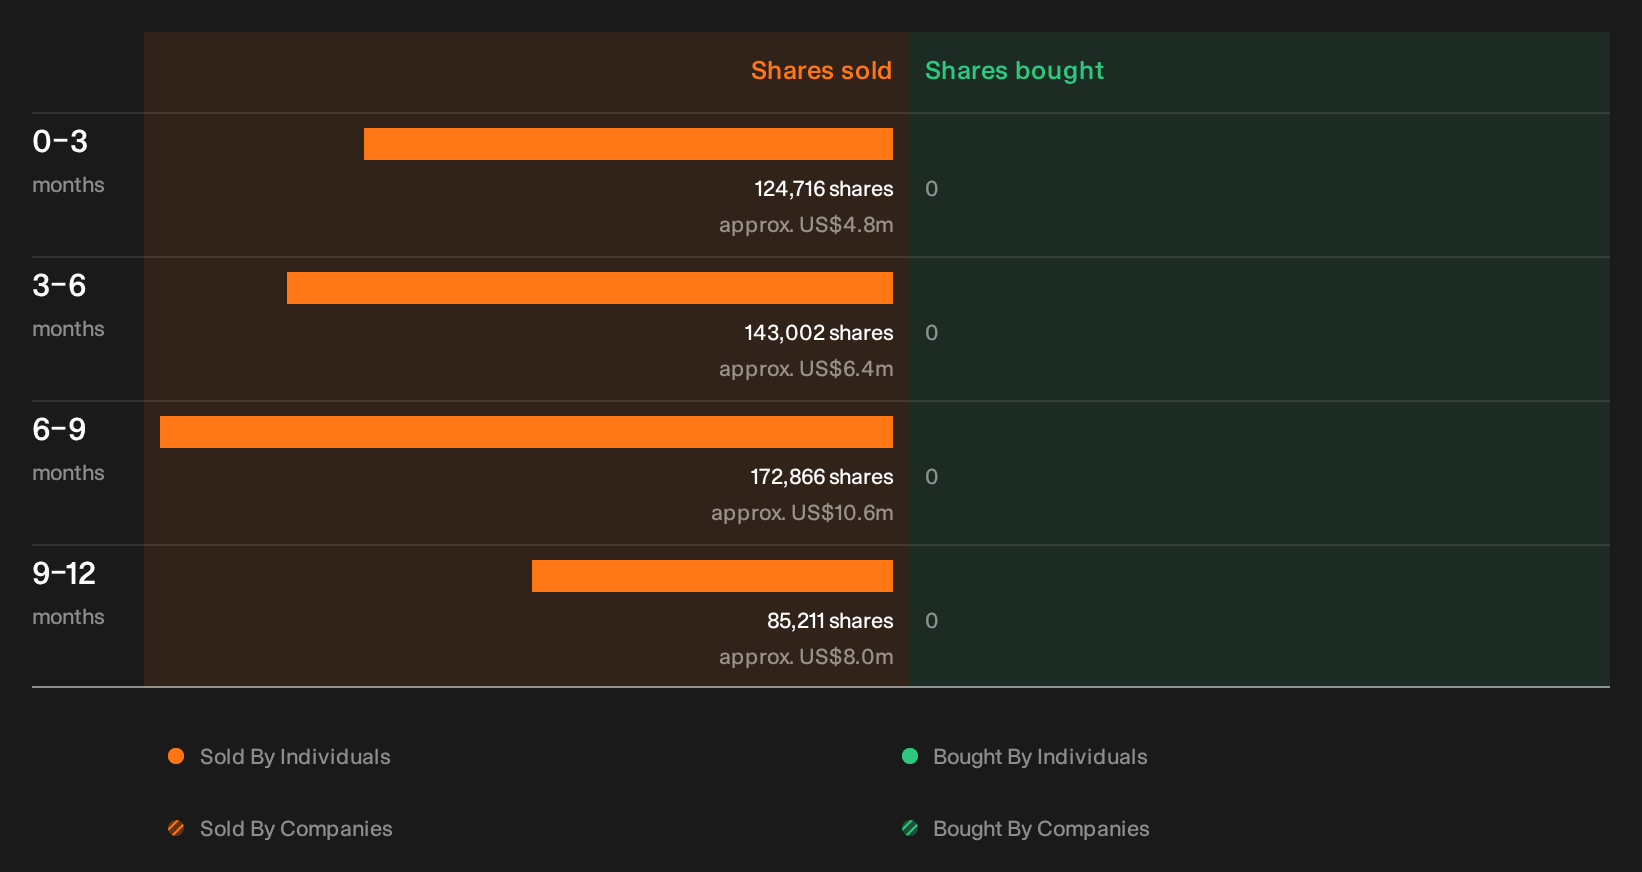
Cash based valuation work sketches one picture of Roblox, yet our checks also highlight recent share sales by insiders, with the individuals, sizes and possible takeaways still waiting for you to review. See the recent insider selling flagged for Roblox.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com