
EBAY Stock Layoffs: What to Know as eBay Plans Job Cuts for Second Time This Year
EBay (EBAY) shares inched higher on Oct. 21 after the online marketplace confirmed another round of layoffs — putting potential cost savings back in focus. The company plans to eliminate about 1,000 jobs, representing roughly 9% of its workforce, to redirect resources toward faster-growing businesses.
EBAY stock has been a blockbuster investment in 2026, currently trading nearly 40% above its price at the start of this year.
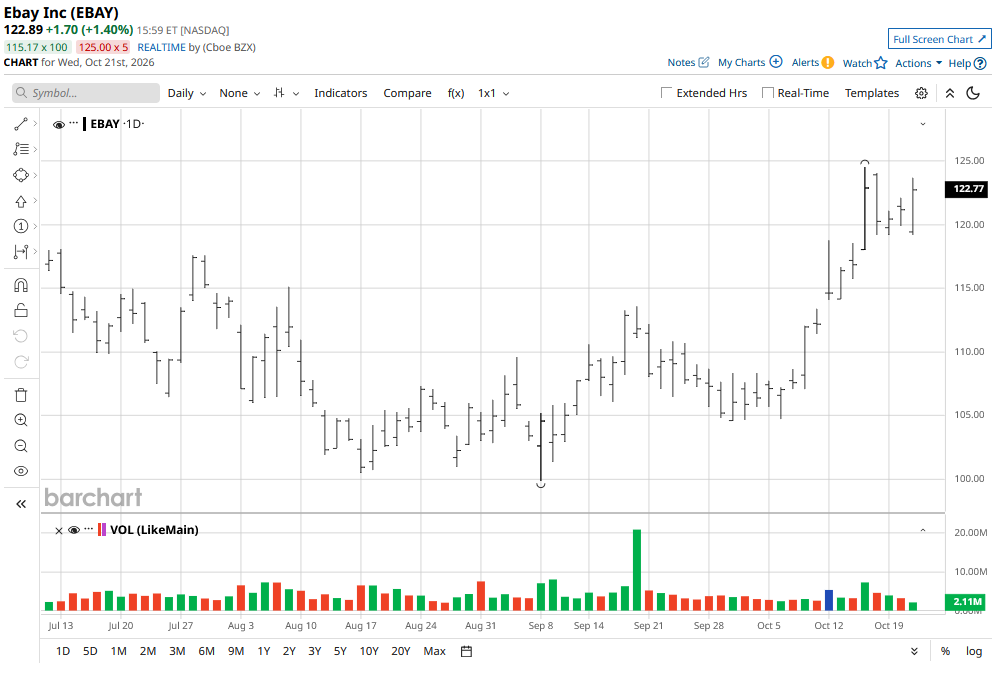
What Layoffs Really Mean for eBay Stock
In an employee memo, eBay’s chief executive Jamie Iannone said affected workers would receive notification in the coming days. Meanwhile, the e-commerce giant will continue hiring in selected areas that support its priorities, according to The Wall Street Journal.
For shareholders, this latest round of layoffs signals a smaller expense base that would leave more room to fund expansion without sacrificing profitability.
But the outcome mostly depends on execution: repeated job cuts could disrupt operations, and the media reports haven’t established a quantified savings target.
Investing in EBAY shares therefore warrants demanding evidence that management can sustain marketplace growth while translating a leaner organization into stronger earnings.
Erste Group Issues a Bullish Note on EBAY Shares
Also on Wednesday, analysts at Erste Group initiated coverage of EBAY stock with a “Buy” rating, citing improving growth and a valuation they consider moderate relative to earnings.
Consensus is for the Nasdaq-listed firm to report $1.11 in earnings per share (EPS) for its fiscal Q3 on Oct. 28, up from $1.10 per share in the same quarter last year.
In their research report, analysts dubbed eBay’s investment in Depop, particularly in the U.S., an avenue for further expansion. They expect margin to improve by 2028 at the latest and believe the firm’s revenue is growing faster than its rivals.
EBay has historically gained about 1.68% in November, which makes it even more attractive as a near-term holding.
What’s the Consensus Rating on eBay?
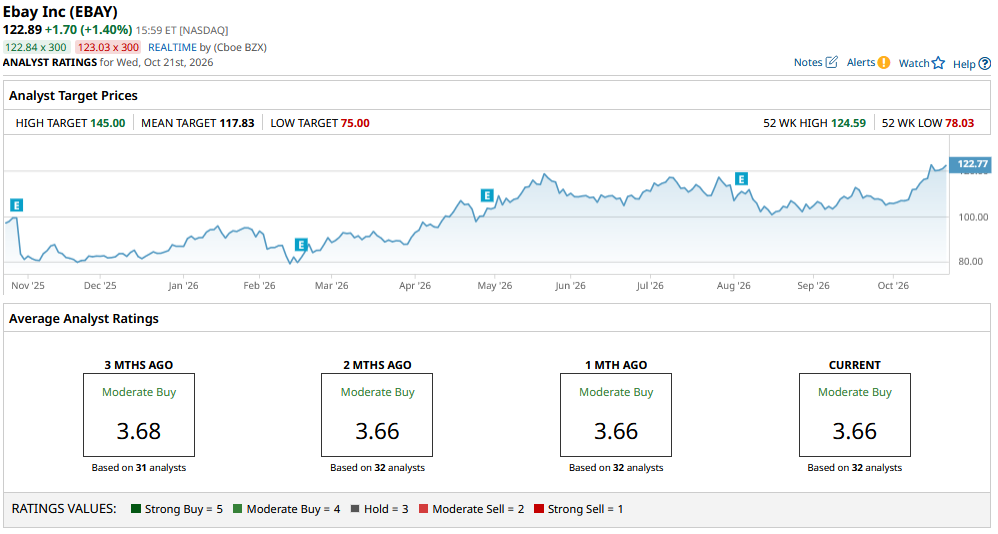
Other Wall Street analysts also find eBay shares attractive at their current price of about $123.
The consensus rating on the e-commerce platform sits at “Moderate Buy” currently, with price targets as high as $145 indicating potential upside of about 20% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.