
What Evergy (EVRG)'s Earnings Beat Means For Shareholders
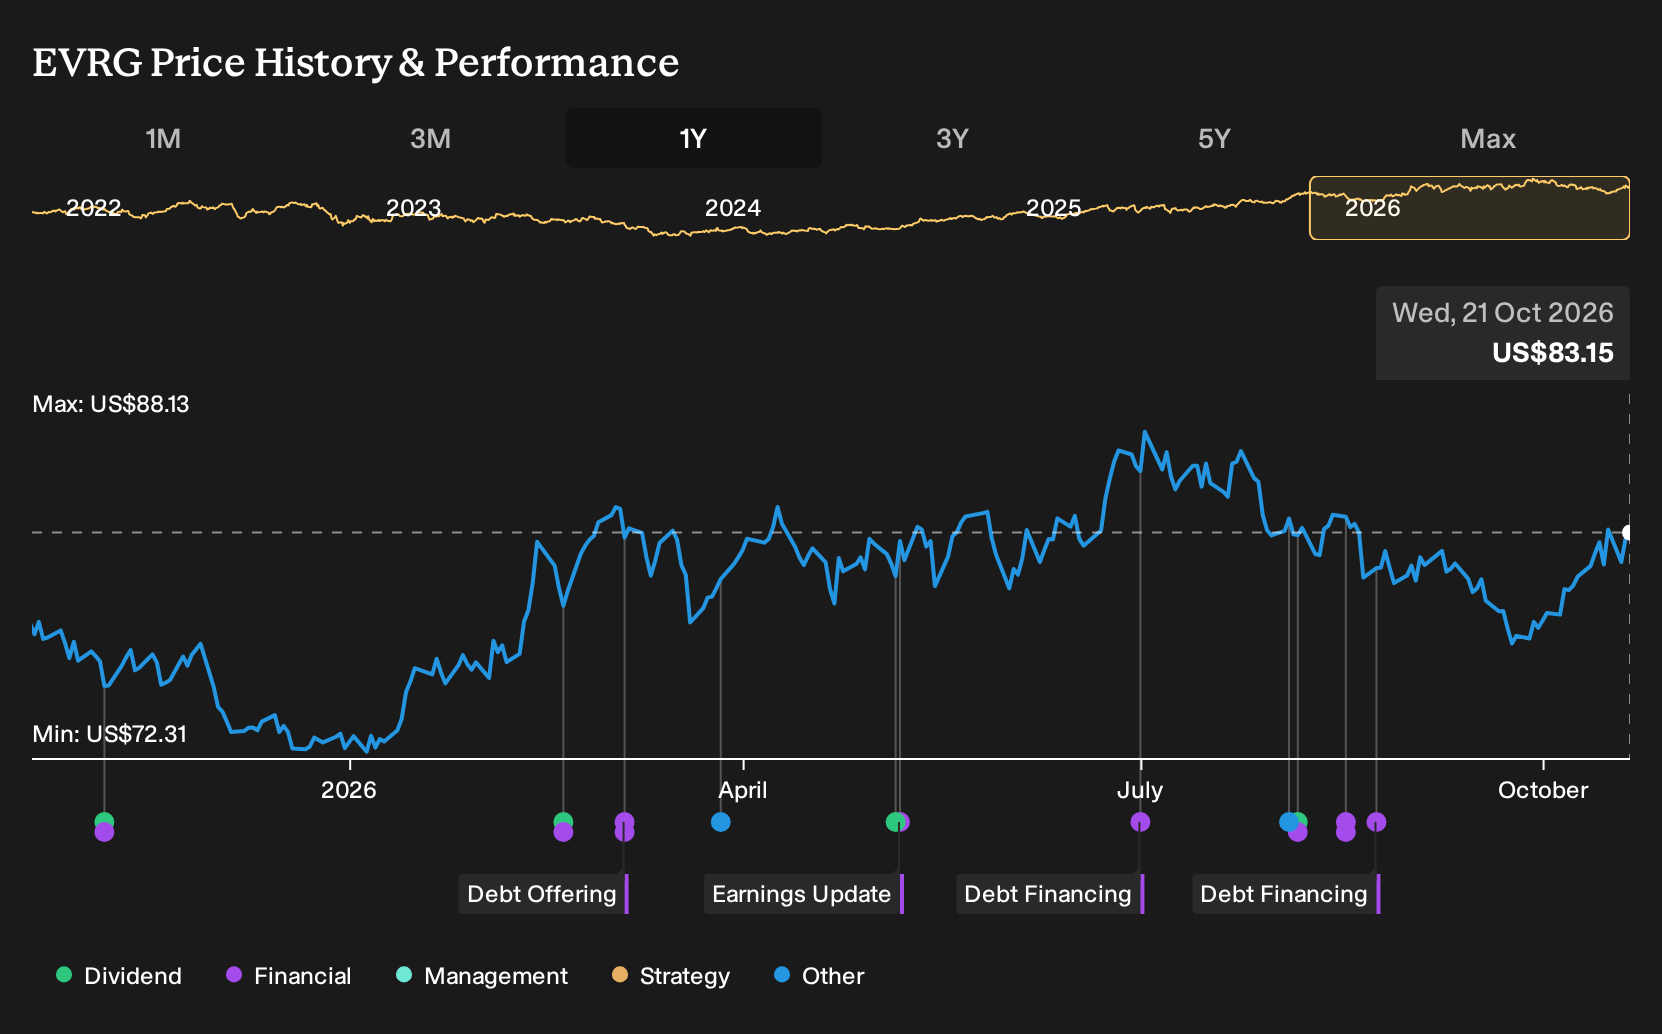
- Evergy has recently drawn attention after analysts highlighted a positive Earnings ESP of 4.41% and a Zacks Rank of 2, following two quarters in which the utility beat earnings estimates ahead of its next scheduled report, previously expected on 5 November 2026.
- The stronger earnings setup points investors back to Evergy’s underlying operations. Execution on large capital projects and cost discipline will be central to how any future earnings surprises translate into longer term fundamentals.
- We will now look at how Evergy’s recent positive earnings setup could influence the investment narrative built around its capital program.
Scan how Evergy’s earnings setup compares with other regulated utilities that pair capital spending with cost control by checking the curated 42 power grid technology and infrastructure stocks.
Evergy Investment Narrative Recap
For an investor in Evergy, the core belief is that large data center and industrial demand, paired with a heavy grid and generation buildout, can support steady earnings while customer bills stay manageable. The recent positive Earnings ESP and past estimate beats help confidence in short term execution, but do not fundamentally change that long range thesis.
The closest near term swing factor is how project costs, interest expense and operations spending show up in upcoming results. Higher capital needs and equity issuance sit on the other side of that. If cost pressure or regulatory pushback on rates intensifies, the risk to margins and returns becomes more visible.
The most relevant data point to link with the current earnings setup is Evergy’s planned US$21.6b grid and generation capital program for 2026 to 2030, plus about US$1b of extra generation investment. Those projects, tied to roughly 3 GW of contracted large load and targeted 7% to 8% retail load growth, underpin the story investors are really underwriting.
The near term earnings beat narrative only matters if it signals smoother execution on that build plan, manageable operations and maintenance costs, and stable regulatory outcomes as rate cases reflect the growing asset base. Your judgment comes down to whether the balance sheet, including the US$3.5b credit facility and ongoing equity issuance, comfortably supports that build without eroding returns.
Evergy's narrative projects US$7.3b revenue and US$1.3b earnings by 2029. This aligns with analysts' expectations of 6.4% yearly revenue growth and an earnings increase of about US$374m from earnings of US$925.8m today.
Uncover why Evergy's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$61.57 to US$89, which already shows how far opinions on Evergy can stretch. Those views sit alongside real execution questions on heavy capital spending, customer ramp risks and future rate decisions. Use that spread to stress test your own roadmap, rather than simply confirm it.
Explore another Evergy fair value estimate, including one that suggests as much as 7% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Evergy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Evergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evergy's overall financial health at a glance.
Looking for more investment ideas beyond Evergy?
If Evergy has sharpened how you think about earnings setups, capital plans and balance sheets, you can use that same lens across a broader watchlist using the Simply Wall St screener.
- For readers who want potential upside with a margin of safety, scan companies that combine quality fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- If capital preservation and steadier profiles rank higher on your priorities, focus on the 31 resilient stocks with low risk scores to see businesses with more resilient risk scores.
- When balance sheet strength is non negotiable, narrow your search to companies on the list of solid balance sheet and fundamentals (25 results) and filter for the financial traits that matter most to you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com