
Globe Life (GL) Stock May Be About Right Following Buyback Guidance
Globe Life has delivered a powerful run for long term holders, which naturally pushes the question back onto its earnings and whether those profits still justify where the share price trades today. With recent news around earnings and capital returns fresh in mind, the focus is shifting to what the current valuation really asks investors to pay for the insurer's profit stream.
- Globe Life has returned 94.5% over the past 5 years, which raises the question of how much future earnings strength is already reflected in the current valuation.
- Recent profit results and a larger share repurchase plan highlight how management is using excess capital, which can influence per share earnings power and the multiple investors are willing to pay.
- Your read on Globe Life is one view; the desks covering it have another. See what analysts think Globe Life's shares could be worth.
The issue now is whether Globe Life's current price is adequately supported by its earnings when set against the Fair Ratio benchmark.
If you are weighing Globe Life's earnings based valuation against other ideas, a targeted stock screen built around 33 high quality undervalued stocks can give you a clean starting list for further research.
Is Globe Life Fairly Priced on Earnings?
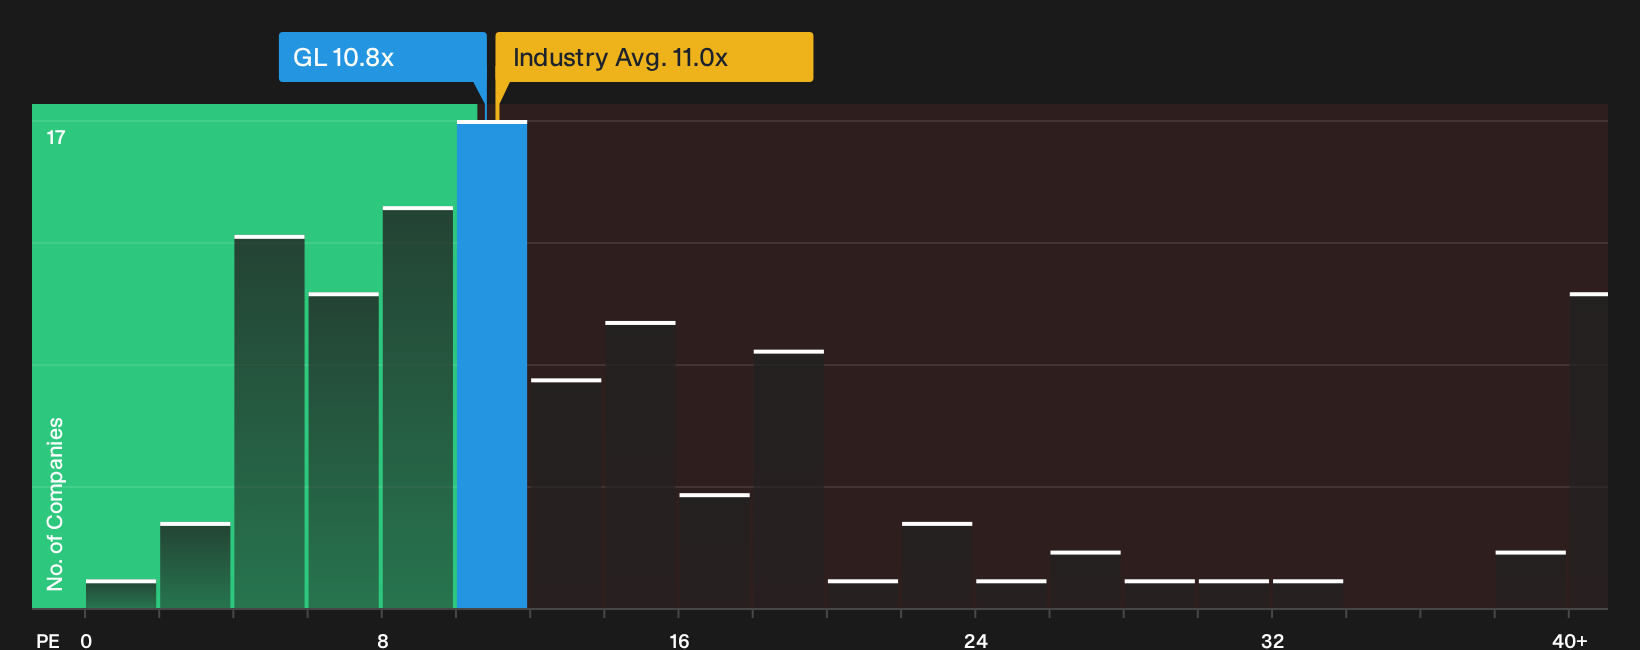
A P/E lens fits Globe Life because earnings per share sit at the center of how investors judge insurers. On that measure, Globe Life currently trades on a P/E of 10.8x, which is slightly below the Insurance sector average near 11.0x and far below the broader peer group reference near 38.6x.
Compared with a Fair Ratio that already incorporates Globe Life's profitability profile and risk, the current P/E is somewhat elevated but not by a wide margin. Because management has recently raised share repurchase guidance despite a small Q3 2026 earnings miss, the market is effectively valuing each dollar of Globe Life earnings at a level that appears broadly aligned with what the model suggests investors might expect to pay. Explore the numbers behind Globe Life's P/E valuation.
The Globe Life Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Globe Life leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s level on the Community page. Each narrative links Globe Life's potential catalysts and key risks to a specific fair value estimate so you can track over time which version of the story is actually unfolding.
Globe Life followers are split between a camp that sees more upside left and another that views the current setup as roughly fairly valued.
Bull case: 13% undervalued
"Planned deployment of AI applications across administration, underwriting and sales support is aimed at lowering the administrative expense ratio from about 7.3% of premium…"
Discover why this Narrative puts Globe Life at 13% undervalued.
Bear case: roughly fairly valued
"Although Globe Life is rolling out broader AI tools across underwriting and administration, the recent rise in health obligations to 56.8% of premium…"
Explore why this Narrative puts Globe Life at roughly fairly valued.
One more Globe Life question before you move on
Everything so far has focused on what Globe Life looks like today. Professional coverage also sketches out where earnings and profits might be a few years from now, which can sharpen how you judge the current multiple. Explore where analysts expect Globe Life to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com