
Gentherm (THRM) Swung To A Loss As Raised 2026 Outlook Put Value In Focus
Balancing Gentherm’s Q3 Loss With Raised 2026 Outlook
Gentherm (THRM) moved into focus after its latest quarterly update combined a swing to a modest net loss with a sizeable increase to full year 2026 product revenue guidance.
That mix of a small quarterly loss and sharply higher 2026 revenue guidance has not yet helped Gentherm’s share price. It has fallen 21.6% over the past month and 37.7% over the past quarter, while the 1 year total shareholder return is down 11.8% and the 5 year total shareholder return has declined 65.8%. This suggests momentum has been fading as investors reassess both growth potential and execution risk.
Compare Gentherm’s mix of pressure and potential with other auto-linked opportunities by scanning our hand picked 33 high quality undervalued stocks that combine cash flow support with balance sheet strength.
Gentherm now trades at a steep discount to both analyst targets and some intrinsic value estimates after this swing to a quarterly loss. Is that a market overreaction, or a fair price for the execution risk ahead?
Most Popular Narrative: 40.8% Undervalued
Gentherm’s most followed valuation narrative points to a fair value of $48 against a last close of $28.44, which frames the current share price as meaningfully discounted if those assumptions hold.
The combination with Modine Performance Technologies, which cuts Gentherm’s light vehicle exposure from roughly 97% of revenue to about 63% and creates a US$2.6b company with a path to more than US$3.5b of revenue and US$0.5b of EBITDA by 2030, adds scale in commercial vehicle, off highway and power generation that can support both revenue growth and margin resilience.
See why 3 investors see Gentherm as 41% undervalued.
Result: Fair Value of $48 (UNDERVALUED)
Still, Gentherm’s story can crack if Modine Performance Technologies integration stumbles, or if inflation, logistics and warranty costs keep squeezing already thin margins.
Find out about the key risks to this Gentherm narrative.
Another Take On Gentherm’s Valuation
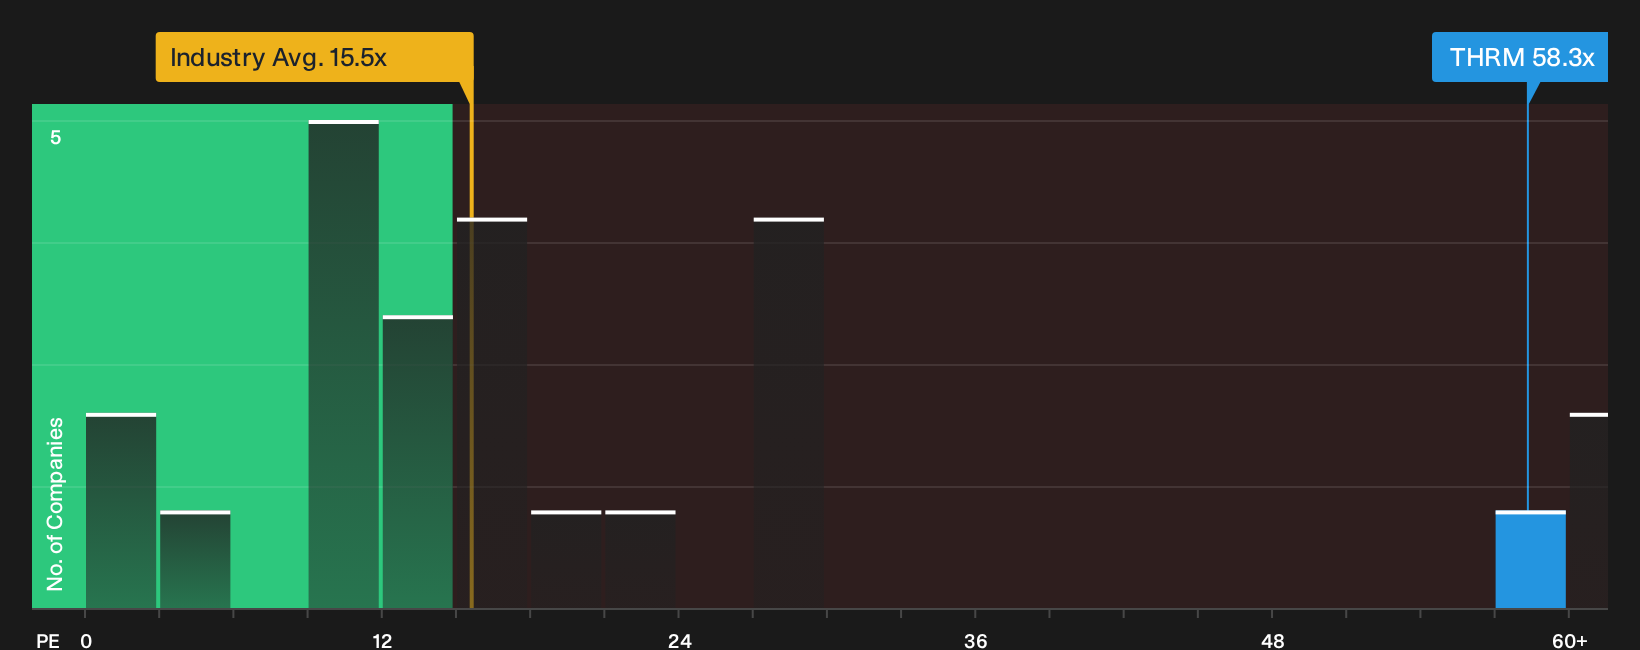
The community view pegs Gentherm at $48 per share, yet the current P/E of 58.3x screens as expensive next to both the Auto Components group on 15.8x and an estimated fair ratio of 44.1x. That premium narrows the margin for error if earnings forecasts slip.
For a closer look at what the numbers imply if the market moves back toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in Gentherm’s story can look either encouraging or worrying depending on which data point you focus on, so move fast and stress test the numbers yourself by weighing the 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Gentherm?
If Gentherm has you rethinking where risk and reward line up, broaden your watchlist now so you are not relying on a single story.
- Target resilience by scanning a 31 resilient stocks with low risk scores that screens for businesses with lower overall risk profiles and potentially steadier performance.
- Hunt for value with a 21 high quality undiscovered gems that highlights under followed companies with solid fundamentals that the market may be overlooking.
- Strengthen your core holdings by focusing on a list of solid balance sheet and fundamentals (25 results) that prioritizes robust finances and healthier debt positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com