
Will Earnings Beat Change Chemed (CHE) Stock Narrative
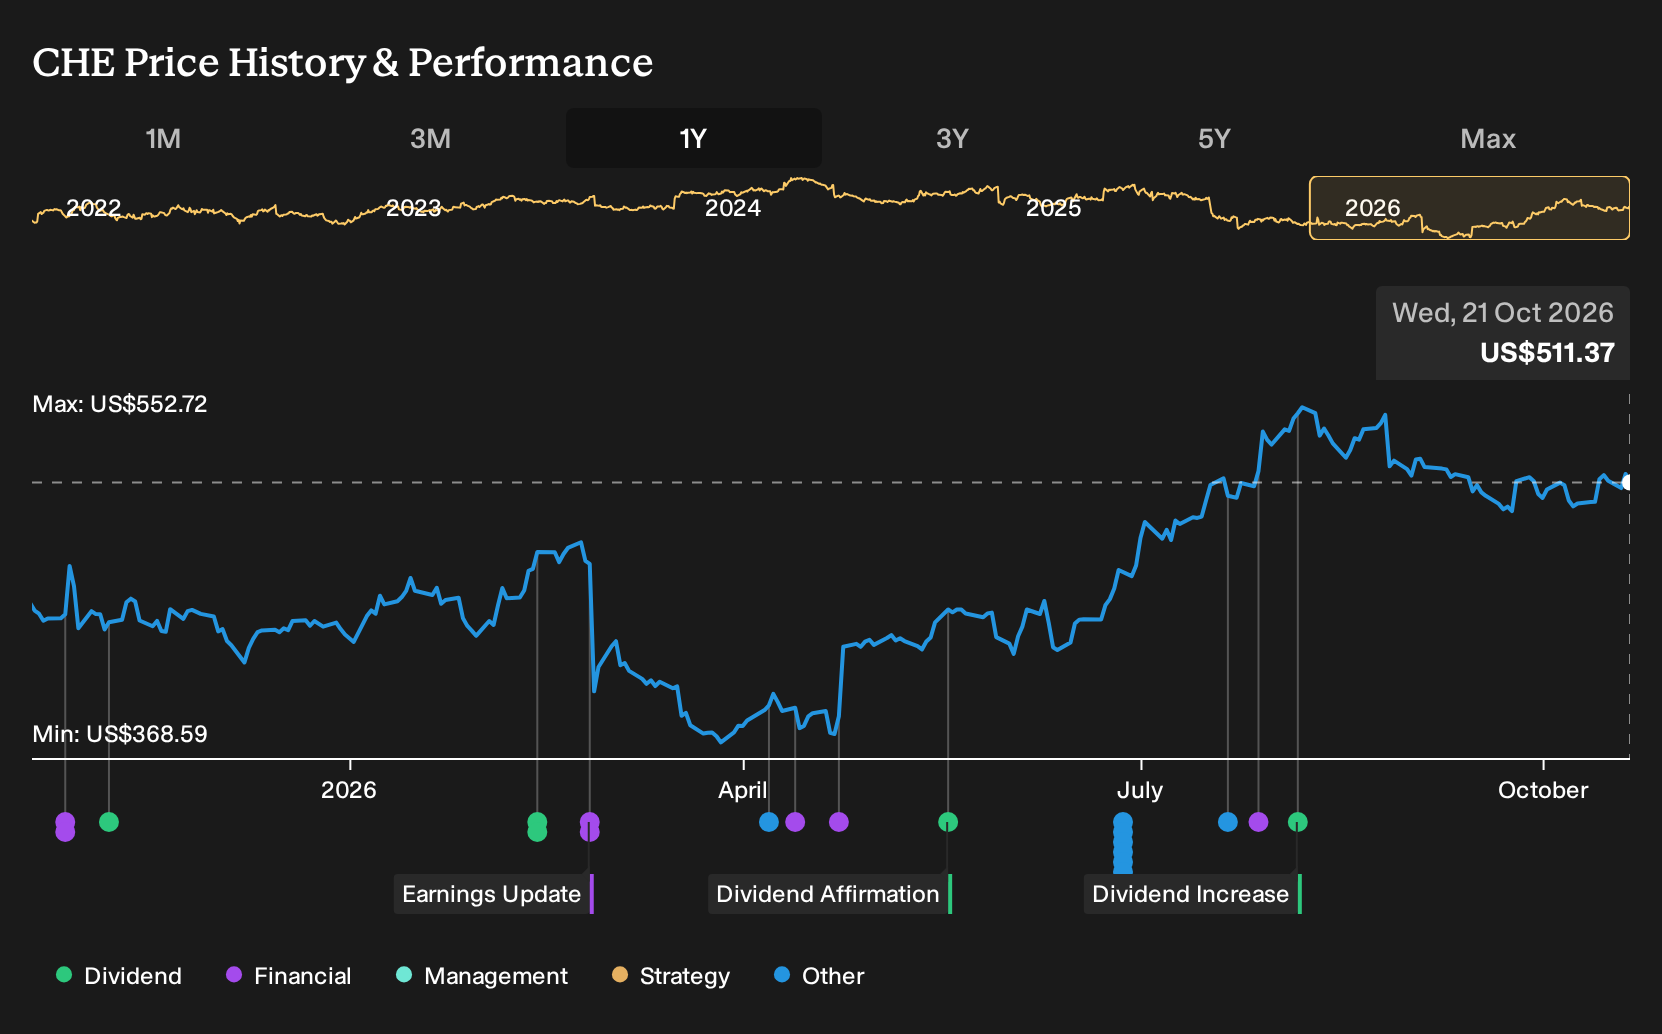
- Chemed reported a strong Q2, with revenue coming in 1.2% above analyst expectations and full year EPS guidance also ahead of prior estimates.
- The combination of hospice care at VITAS and household services at Roto Rooter appears resilient despite industry pressure from labor shortages and reimbursement constraints.
- We will look at how Chemed's investment narrative evolves as its Q2 revenue and EPS beats interact with hospice and home services trends.
Look beyond Chemed and compare its combination of hospice and home services resilience with our curated list of 31 resilient stocks with low risk scores that also aim to hold up under industry pressure.
Chemed Investment Narrative Recap
To own Chemed, you need to be comfortable with a healthcare and home services mix that leans heavily on hospice reimbursement rules and consumer repair demand. The recent Q2 beat on revenue and full year EPS guidance signals that operations are holding up against labor and reimbursement pressure. The key short term swing factor remains VITAS execution on Medicare Cap management and patient mix.
The biggest risk is still policy or rule changes that squeeze hospice rates or reset Medicare Cap dynamics, paired with higher lead costs at Roto Rooter that could pressure margins if pricing power softens. Based on what is disclosed, the latest quarter supports confidence in execution, but it does not remove those structural issues.
With no new company specific announcements tied directly to this Q2 release, the most relevant context is the ongoing ramp of new Certificate of Need locations in Florida that had already been highlighted. Those build outs in counties such as Pinellas and Marion matter because they expand the VITAS reach into areas described as underserved and deepen Chemed’s exposure to hospice under use.
For you as an investor, the interaction between that footprint expansion and current Q2 performance is practical. Stronger guidance gives Chemed more room to keep investing in operations, technology and process improvement to support those new sites while working on Medicare Cap mitigation and cost control. The same projects that underpin the Florida rollout are closely linked to the main catalysts and to the reimbursement and margin risks already on the table.
Chemed Consensus Outlook And Embedded Assumptions
Chemed's narrative projects revenues of US$3.2b and earnings of US$401.0m by 2029. That path uses analyst assumptions of 7.0% yearly revenue growth and an earnings increase of about US$126.0m from current earnings of US$275.0m.
Uncover why Chemed's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Chemed’s hospice admissions mix as the key swing factor rather than just Medicare Cap risk. Before this Q2 beat, the bullish camp was already penciling in US$3.2b of revenue and US$412.0m of earnings by 2029. You can treat this Q2 update as a chance to reassess which narrative is closer to your own expectations.
Explore 2 other Chemed fair value estimates, including one that suggests there may be as much as 36% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Outstanding investment outcomes are often associated with independent thinking, so consider trusting your own judgment.
- A great starting point for your Chemed research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chemed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Chemed's overall financial health at a glance.
Looking For More Ideas Beyond Chemed?
If the Chemed story has sharpened your thinking about risk, returns and business quality, it can be useful to line it up against a wider bench of potential holdings. The Simply Wall St Screener helps you scan the market through clear filters so you can focus on companies that better match your risk tolerance and income or growth goals.
- For investors who want potential upside with tighter risk controls, consider scanning a group of resilient candidates through the 31 resilient stocks with low risk scores.
- If income is a priority and you care about yield strength, take a look at companies offering steady payouts in the 7 dividend fortresses.
- For readers searching for mispriced opportunities with solid fundamentals, the 21 high quality undiscovered gems can help surface ideas that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com