
What Wacker Chemie Doubters Overlooked
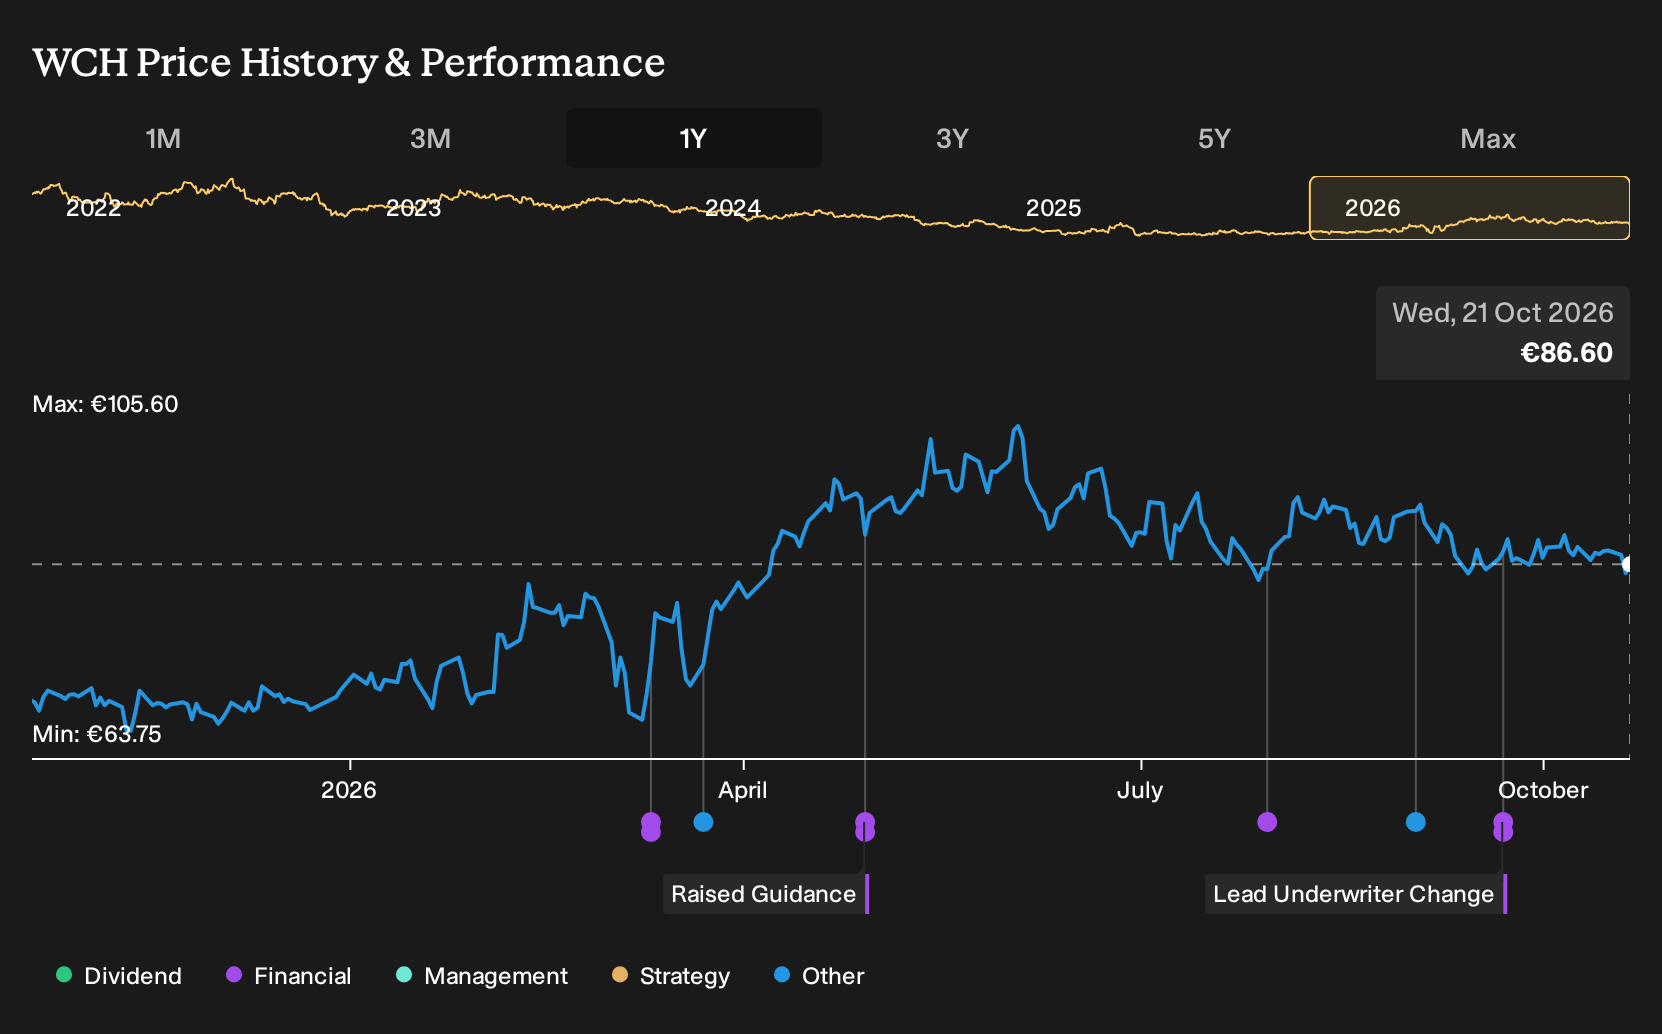
If you had looked at Wacker Chemie in late 2025, the debate was sharp. One bullish view argued that polysilicon and renewable energy investments would drive future value, while a bearish camp warned that global emission costs and overcapacity could crush operating margins. Holding Wacker Chemie over the past year would have returned 30.2%, including dividends. If that outcome rested on information already on record, what exactly were investors seeing at the time?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Wacker Chemie. Zero in on 190 high quality undervalued stocks for companies trading below our estimates.
What Wacker Chemie Investors Were Actually Arguing About
The shares cost €67.65 at the start of the period, and anyone looking at Wacker Chemie then had to decide which story felt more realistic.
The bullish narrative put Fair Value at €71.64. It was based on revenue increasing 3.1% a year with profit margins at 3.2%, supported by heavier exposure to polysilicon and renewable energy related products.
The bearish view pointed to a Fair Value of €52. It focused on rising emission costs and global overcapacity that could pressure margins even if reported profit margins moved to 4.2% over time.
What The Results Actually Tested At Wacker Chemie
The clearest data point came from Wacker Chemie reporting Q2 2026 revenue of €1,517.6m and net income of €340.8m, with net margin at 22.5% compared with a loss and a 1.7% margin in Q2 2025. That profit swing supported the focus on higher earnings and cost control, although one strong quarter alone did not settle the longer term margin debate.
The lesson is simple. When a thesis hangs on profitability improving, track net margin across several reports and compare it directly with the percentages used in your original story.
What Wacker Chemie’s Price Seems To Assume Now
Wacker Chemie trades at €86.6 after a 30.2% gain over the past year. The selected Narrative places its Fair Value below that level, framing the current quote as already pricing in cleaner execution rather than a deep turnaround discount.
Analysts behind this Narrative focus on whether cost programs, the biosolutions ramp up and product mix really turn into steadier margins. A buyer today effectively assumes those efforts work. The question is how that sits with the risk that underused assets and energy costs keep earnings from matching that script.
"Although Wacker Chemie is rolling out a single ERP system and AI tools to tighten planning and execution, the slower than expected ramp of new biotech capacities and the turnaround status of most biosolutions units suggest that any uplift from digitalization could be outweighed by prolonged underutilization and weak revenue contribution from this segment, which would limit group earnings."
One Narrative disagrees with today's price. → See where this Narrative says Wacker Chemie should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 32% below our estimate - builds out multichannel retail and e-commerce while lifting earnings and dividend payouts.
- Company 2 - 28% below our estimate - widens direct and retail probiotic distribution as adult health products gain shelf space.
- Company 3 - 43% below our estimate - secures forensic software contracts as departments adopt new subscription tools for digital evidence.
Three companies from the same screener. Open the full list of 203 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com