
Is Ultra Clean Holdings (UCTT) Undervalued After Its Sharp Pullback?
Ultra Clean Holdings (UCTT) has been pulled into focus after a sharp share price retreat following several years of strong gains, prompting investors to reassess how the market is pricing its revenue and integration model.
Ultra Clean Holdings has moved from a strong year to a sharp setback, with the 30 day share price return down 28.51% and the 90 day move down 48.07%. At the same time, the year to date share price return of 91.14% and 1 year total shareholder return of 87.37% still point to longer term momentum that is now clearly fading in the short run.
Scan other potential opportunities in semiconductor suppliers by comparing Ultra Clean Holdings with a curated list of 55 AI infrastructure stocks that are also exposed to chip equipment demand cycles.
Bulls point to Ultra Clean Holdings’ strong multi year share gains and integration story. Bears highlight the recent slump and current loss making position. Which side does today’s valuation actually lean toward?
Most Popular Narrative: 62% Undervalued
On the most followed view, Ultra Clean Holdings screens as undervalued, with a fair value of $137 against the last close at $52.22, putting a lot of weight on how its growth and efficiency story plays out.
New product qualifications and business wins, especially at the Czech facility, are expected to contribute incremental revenue starting in Q4, positioning Ultra Clean to benefit from continued accelerated investment in advanced fabs and the robust outlook for semiconductor capital equipment spending (impacts revenue growth).
A surge in AI-driven capital investment and strong expectations for new fab buildouts in 2026 support solid long-term demand for Ultra Clean's advanced process subsystems, reinforcing the company's exposure to the ongoing expansion of digital infrastructure and complex chip manufacturing (supports long-term revenue trajectory).
See why 22 investors see Ultra Clean Holdings as 62% undervalued.
Result: Fair Value of $137 (UNDERVALUED)
Still, heavy reliance on a few large customers, along with ongoing tariff and supply chain friction, could quickly challenge the upbeat Ultra Clean Holdings narrative.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: DCF Flags Ultra Clean Holdings As Expensive
The popular narrative tags Ultra Clean Holdings as undervalued at a fair value of $137, yet our DCF model presents a very different picture. On that framework, the estimated future cash flow value is $12.31 per share, which sits well below the current $52.22 price and points to an overvalued signal instead.
This kind of gap between a story built on earnings and margin expansion and a cash flow driven lens leaves investors with a simple question: Which set of assumptions feels more realistic for how Ultra Clean Holdings actually converts growth into cash over time?
Look into how the SWS DCF model arrives at its fair value.
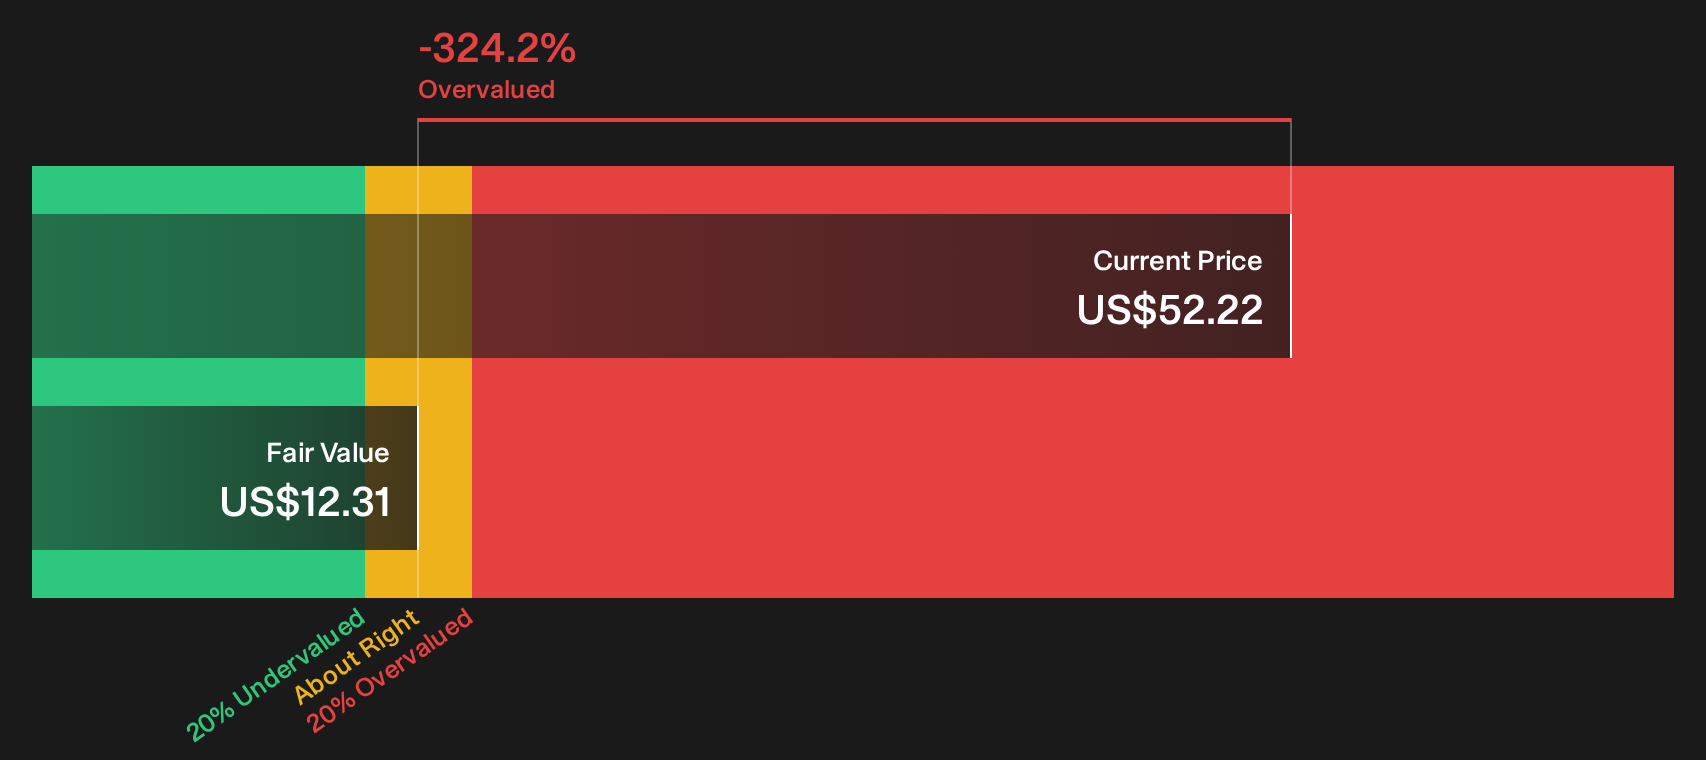
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ultra Clean Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Ultra Clean Holdings is clearly split. Move quickly, test the assumptions on both sides, and weigh the 3 key rewards and 2 important warning signs.
Looking for more Ultra Clean Holdings style opportunities?
If Ultra Clean Holdings has sharpened your sense for pricing power and risk, do not stop here. Use fresh ideas from targeted screeners to keep raising your game.
- Target resilient balance sheets by running your filters through a list of solid balance sheet and fundamentals (25 results) so you are not relying on fragile financing when conditions tighten.
- Hunt for quality at a sensible entry point by lining up candidates in the 33 high quality undervalued stocks that match your return and risk expectations.
- Lock in income-focused opportunities by reviewing a curated pool of 7 dividend fortresses that pair higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com