
V.F (VFC) Eyes An Earnings Beat, Is It Still Undervalued?
Recent commentary around V.F (VFC) has focused on the upcoming September 2026 earnings release, where expectations for a possible earnings beat appear alongside forecasts for lower year-on-year profit and revenue.
V.F shares at US$17.15 have staged a sharp rebound, with a 31.42% 30-day share price return and a 4.07% gain over the past week. However, the stock is still down 5.56% year to date, and the 5-year total shareholder return of 71.40% in losses highlights how fragile momentum remains, despite a 14.72% total shareholder return over the last year.
Scan how V.F stacks up against other potential rebound stories by reviewing the hand picked 33 high quality undervalued stocks now on Simply Wall St.
Bulls see a profitable recovery taking shape at V.F, while bears view the 5 year slide as a value trap in progress. Which case does the current valuation actually support next?
Most Popular Narrative: 9% Undervalued
The most followed narrative on V.F pegs fair value around $18.77, slightly above the last close at $17.15. This frames today’s rebound as a modest discount rather than a deep value outlier.
The strategic focus on expanding higher-margin channels, including direct-to-consumer and e-commerce, is beginning to drive improved gross margins and deeper customer engagement, expected to lift both revenue growth and net margins over time as V.F. capitalizes on the sustained consumer shift toward digital and premium shopping experiences.
See why 50 investors see V.F as 9% undervalued.
Result: Fair Value of $18.77 (UNDERVALUED)
Still, the whole V.F story hangs on a clean Vans turnaround and a reduction in leverage. Setbacks on either front could quickly challenge this undervalued thesis.
Find out about the key risks to this V.F narrative.
Another View On V.F Valuation
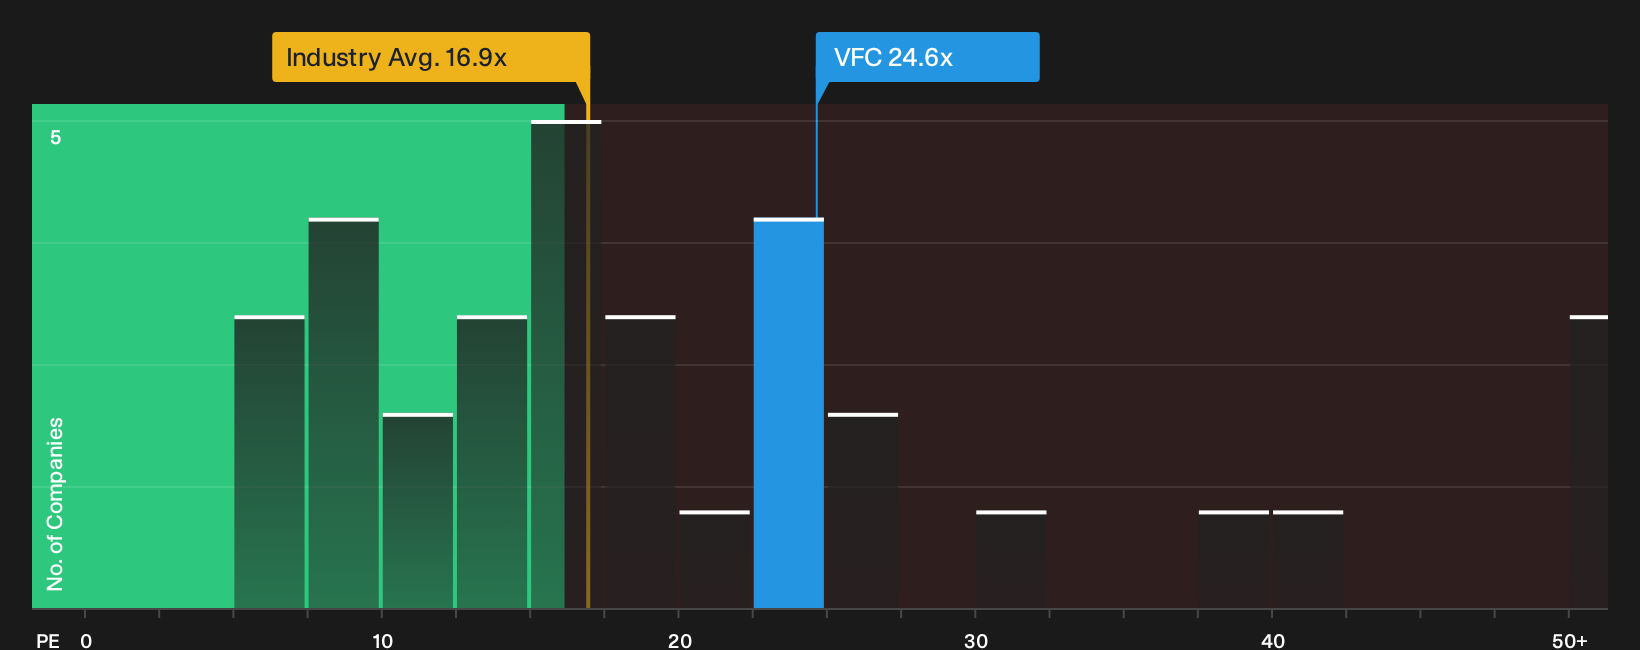
The story looks different when you stop thinking in terms of fair value at $18.77 and focus on what the market is already paying for V.F earnings. The stock trades on a P/E of 24.6x, which is richer than both the US Luxury industry at 17x and peers at 18.8x. However, it sits close to its fair ratio of 25.5x. That mix points to limited room for error on execution rather than a clear bargain, so the real question is whether you see more risk in the turnaround missing, or in staying on the sidelines if it works.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on V.F is split, and that is exactly when doing your own homework matters most. Move quickly and review the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond V.F?
If V.F has your attention but you want a broader watchlist, use these hand picked screens to spot fresh ideas before the crowd catches on.
- Target stronger income potential by scanning companies described as 7 dividend fortresses that may help anchor a portfolio with meaningful cash returns.
- Hunt for quality at a discount by reviewing the 21 high quality undiscovered gems that combine solid fundamentals with limited market attention.
- Prioritise resilience first by checking out the 31 resilient stocks with low risk scores that score well on stability while still offering equity upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com