
Graco (GGG) Misses On Earnings And Guidance After The Drop Is It A Buy
Graco (GGG) just delivered third quarter numbers that combined higher sales with softer profitability, missing Wall Street expectations and sending the stock lower after hours as investors weighed the new guidance.
Graco comes into this report with mixed momentum, with a 30-day share price return of 6.82% and a 90-day gain of 5.22%, yet a year-to-date share price move that is down 1%. Longer term, the 3-year total shareholder return of 21.92% and 5-year total shareholder return of 17.06% point to more modest compounding. Recent headlines have centered on the earnings and guidance miss and the new ABB technology partnership, and the sharp after-hours reaction suggests investors are reassessing both Graco’s near-term earnings power and how much risk they are willing to take on for that growth story.
Capitalize on this earnings reset by scanning for industrials with similar growth profiles but different risk setups through our curated 33 high quality undervalued stocks. After that after-hours drop, the question for Graco now is whether this pullback has cleared room for fresh upside or if most of the easy gains are already behind the stock.Most Popular Narrative: 10.4% Undervalued
Graco’s most followed valuation storyline puts fair value at $91.29, above the last close at $81.81. This frames the post-earnings pullback as a discount that hinges on execution in a few key areas rather than broad pessimism about the business.
The main factor that must go right is continued execution on disciplined M&A and integration, so acquired businesses such as COROB, Color Service, Radia and Valco Melton contribute meaningfully alongside organic semiconductor and infrastructure demand.
The integration of COROB and other acquired businesses such as Color Service and Radia, which together are expected to generate about US$190 million of annual revenue, extends Graco into tinting and related niches and can add to revenue and earnings as these operations scale.
See why 10 investors see Graco as 10% undervalued.
Result: Fair Value of $91.29 (UNDERVALUED)
Still, tariff shocks that cannot be passed on to customers, or weaker organic demand in housing-linked Contractor lines, could quickly challenge this 10.4% undervalued Graco narrative.
Find out about the key risks to this Graco narrative.
Another View: Graco On Earnings Versus Price Tag
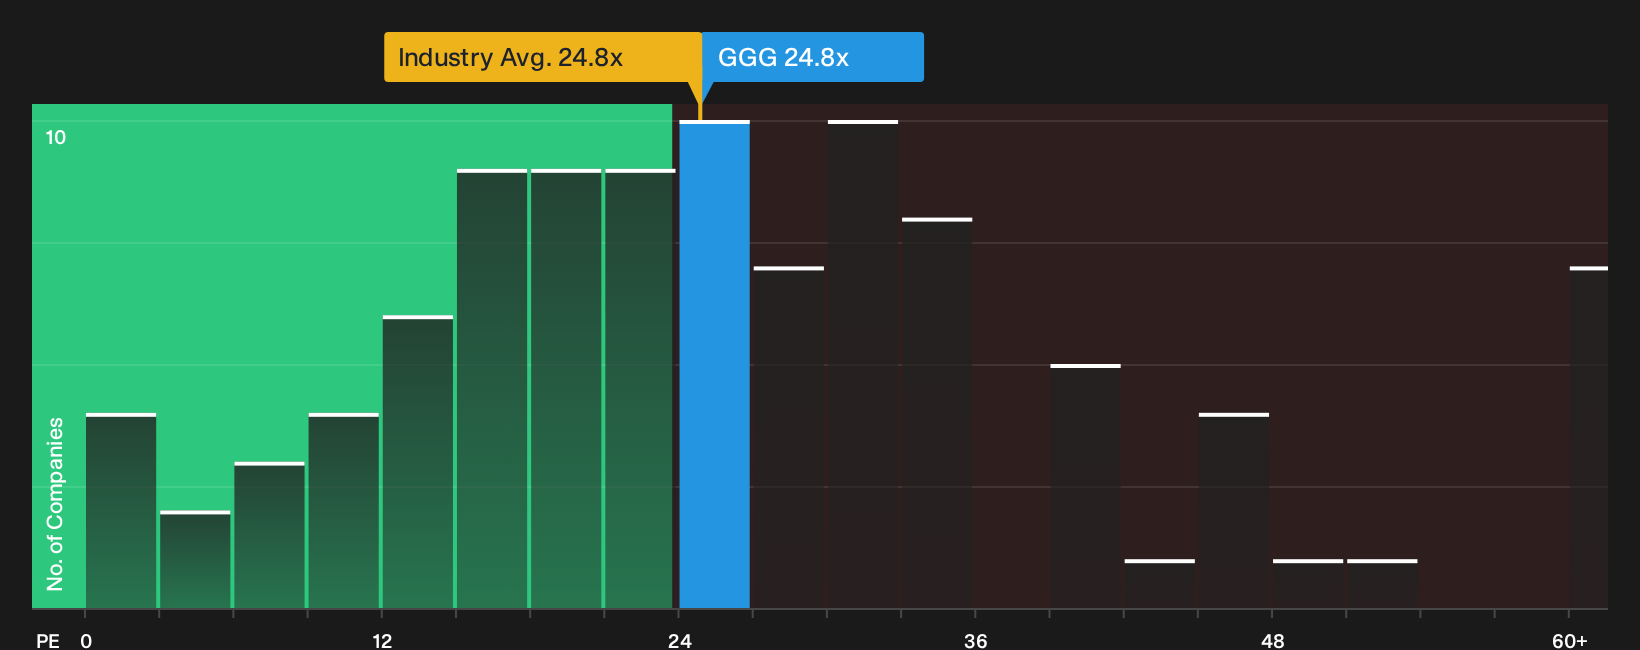
On one hand, Graco looks about 10.4% undervalued against a $91.29 fair value using analyst cash flow style assumptions. On the other, the current P/E of 24.8x is higher than the US Machinery average at 24.5x, the peer average at 23.9x, and a fair ratio of 19.6x. That gap points to meaningful valuation risk if sentiment cools.
This leaves a simple question for you as an investor: Does the stronger return on equity at 21.2% and high quality earnings justify paying a richer multiple, or is this where patience around price starts to matter most, especially after an earnings wobble?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Graco is mixed, which is exactly when it helps to pressure test the numbers yourself and decide how much optimism you share. If you want a quick snapshot of the upside case that others are focusing on, start with the 4 key rewards.
Looking for more investment ideas beyond Graco?
If Graco has you rethinking your watchlist, use this moment to widen your search. Fresh ideas now can matter more than reacting later.
- Target resilient payout streams by reviewing the 7 dividend fortresses and see which income opportunities line up with your risk tolerance.
- Hunt for quality at a discount with the 21 high quality undiscovered gems and spot businesses where the fundamentals do more talking than the headlines.
- Prioritize capital preservation by scanning the 31 resilient stocks with low risk scores so you are not caught off guard when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com