
Chewy (CHWY) Earnings Beat Raises The Question Of Whether The Stock Is Already Fully Valued
Chewy (CHWY) just posted quarterly revenue of US$3.33b, roughly matching expectations, while EBITDA came in ahead of forecasts. However, the share price dropped as enthusiasm and published estimates moved out of sync.
Chewy’s latest report landed after a tough stretch, with the share price declining 36.31% year to date even though the 3-year total shareholder return is still positive at 26.44%. Recent trading has been firmer, with a 4.25% 90-day share price return hinting that sentiment is stabilising as investors recalibrate expectations around growth prospects and risk.
Scan how Chewy’s recalibrated expectations compare with other potential breakouts by reviewing our curated list of 21 high quality undiscovered gems that are waiting for a rerating.
Chewy has just reminded investors it can grow revenue and beat EBITDA forecasts, yet the share price is still down sharply this year. Does that reset create a better risk reward or a value trap at today’s valuation?
Most Popular Chewy Narrative: 26% Undervalued
Chewy closed at $21.33 while the most followed narrative pegs fair value at $28.64, so the gap in expectations is wide and very specific about what needs to work over time.
The growth of Chewy Health categories and the expected ramp in Chewy Vet Care, where clinics are currently outperforming prior economic cases with roughly US$3.5 million in clinic revenue and US$0.8 million of attached Chewy.com revenue per location, create a higher margin health and services mix that can raise gross profit dollars and adjusted EBITDA.
See why 76 investors see Chewy as 26% undervalued.
Result: Fair Value of $28.64 (UNDERVALUED)
Still, the Chewy narrative can break if softer premium spending lingers, or if slower organic sales and cautious guidance keep weighing on analyst expectations.
Find out about the key risks to this Chewy narrative.
Another View: Chewy Looks Expensive On Earnings
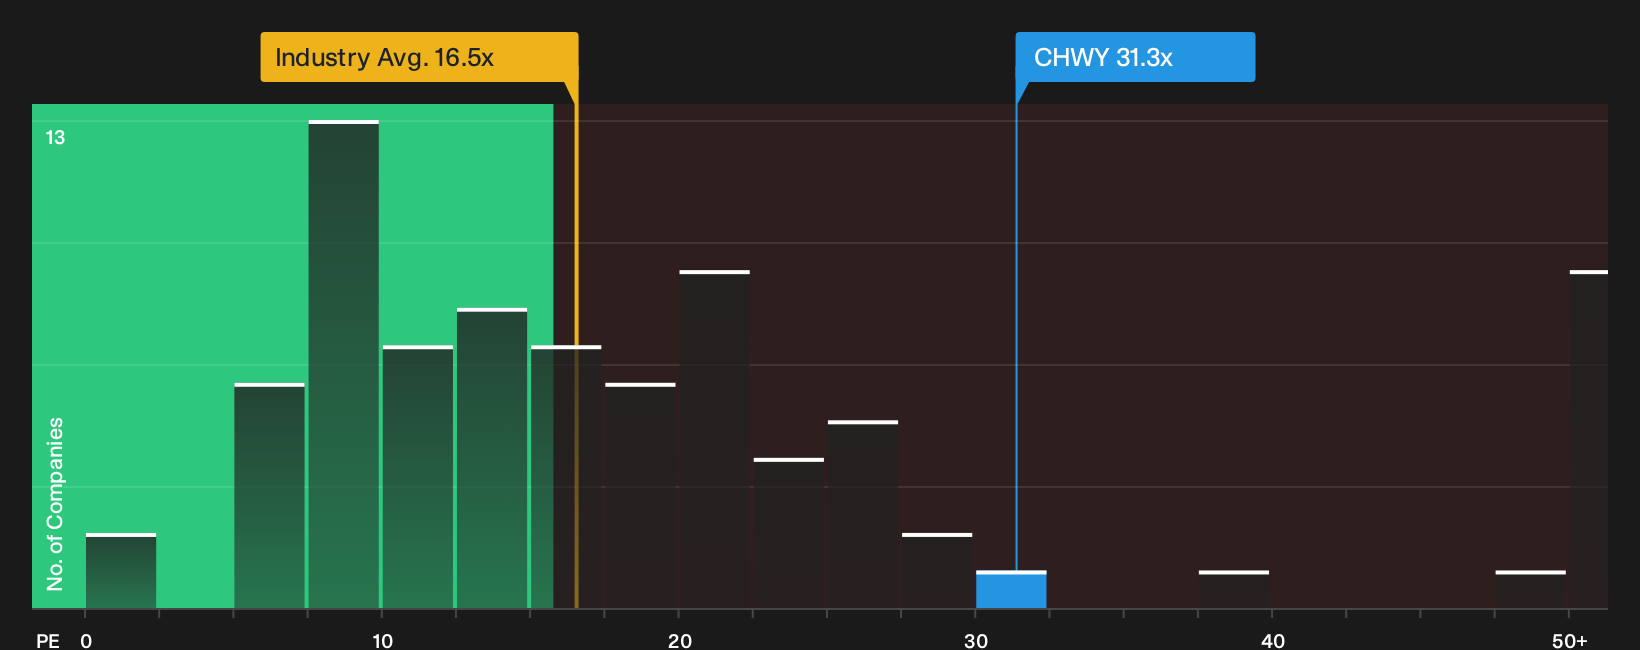
Chewy may screen as undervalued on fair value estimates, yet its current P/E of 31.3x is almost double the US Specialty Retail average of 16.5x and well above its own fair ratio of 21.1x. That gap raises a simple question: Is the market overpaying for the growth story today?
For investors who want to see how that earnings multiple picture is built from the ground up, the valuation breakdown lays out the moving parts in detail, from peer comparisons to the fair ratio estimate, in one place See what the numbers say about this price — find out in our valuation breakdown..
Viewed alongside the broader sector, this puts Chewy at a clear valuation premium on earnings, which can work for or against you depending on how future results line up with expectations
Next Steps
Sentiment around Chewy is split, which is exactly when dispassionate analysis matters most. Move quickly, pull apart the numbers, and weigh the 4 key rewards.
Looking for more Chewy-adjacent investment ideas?
Do not stop with Chewy. Broaden your watchlist now, or you risk missing opportunities that fit your goals better than this single stock ever could.
- Hunt for underappreciated quality by scanning our 33 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
- Target steadier income potential through a curated pool of 7 dividend fortresses that focus on higher yields with staying power.
- Prioritise resilience by reviewing a 31 resilient stocks with low risk scores designed to spotlight businesses with more robust risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com