
Murata Manufacturing (TSE:6981) Unveils Tiny Thermistor On Rich Valuation Questions
Murata Manufacturing (TSE:6981) is back in focus after unveiling its NCU01 series, billed as the world’s smallest 008004-inch NTC thermistor and aimed at cramped, thermally sensitive smartphone and wearable designs.
The fresh product news lands after a sharp pullback. Murata Manufacturing’s share price has fallen 17.15% over the past month and 22.61% over the past quarter. However, its year-to-date share price return of 93.15% and 1-year total shareholder return of 124.87% still point to strong longer-term momentum.
Scan beyond Murata Manufacturing and size up other component makers riding similar demand for miniaturized electronics with our hand-picked 93 robotics and automation stocks
The swing in Murata Manufacturing’s share price could be read as a reassessment of its ceramics and components engine, or simply as sentiment cooling after a strong run. The valuation work starts by separating those two stories.
Preferred P/E of 44.1x: Is it justified?
On earnings multiples, Murata Manufacturing trades on a P/E of 44.1x, which sits just below its peer average yet far above the broader Japanese electronic sector.
The P/E ratio links what investors are willing to pay today to the company’s current earnings. For a business like Murata Manufacturing that sells ceramic-based components, modules, and sensors into smartphones, autos, and industrial gear, this yardstick shows how much of a premium the market is placing on its profit engine.
Compared with a peer average P/E of 45.6x, the stock is described as good value, suggesting buyers are not paying quite as much for each unit of earnings as they are for similar companies. The same 44.1x multiple is described as expensive relative to the wider JP Electronic industry average of 15.4x, which indicates that investors are paying a materially higher price per yen of profit than for the typical sector stock. Against an estimated fair P/E of 38.3x, the market is also paying more than the level the fair ratio model highlights as a potential equilibrium if sentiment cooled.
Explore the SWS fair ratio for Murata Manufacturing.
Result: Price-to-earnings of 44.1x (OVERVALUED)
Still, the recent 1 month and 3 month share price declines, along with Murata Manufacturing’s premium P/E, leave little room if sentiment or end demand weakens.
Find out about the key risks to this Murata Manufacturing narrative.
Another view on Murata Manufacturing’s value
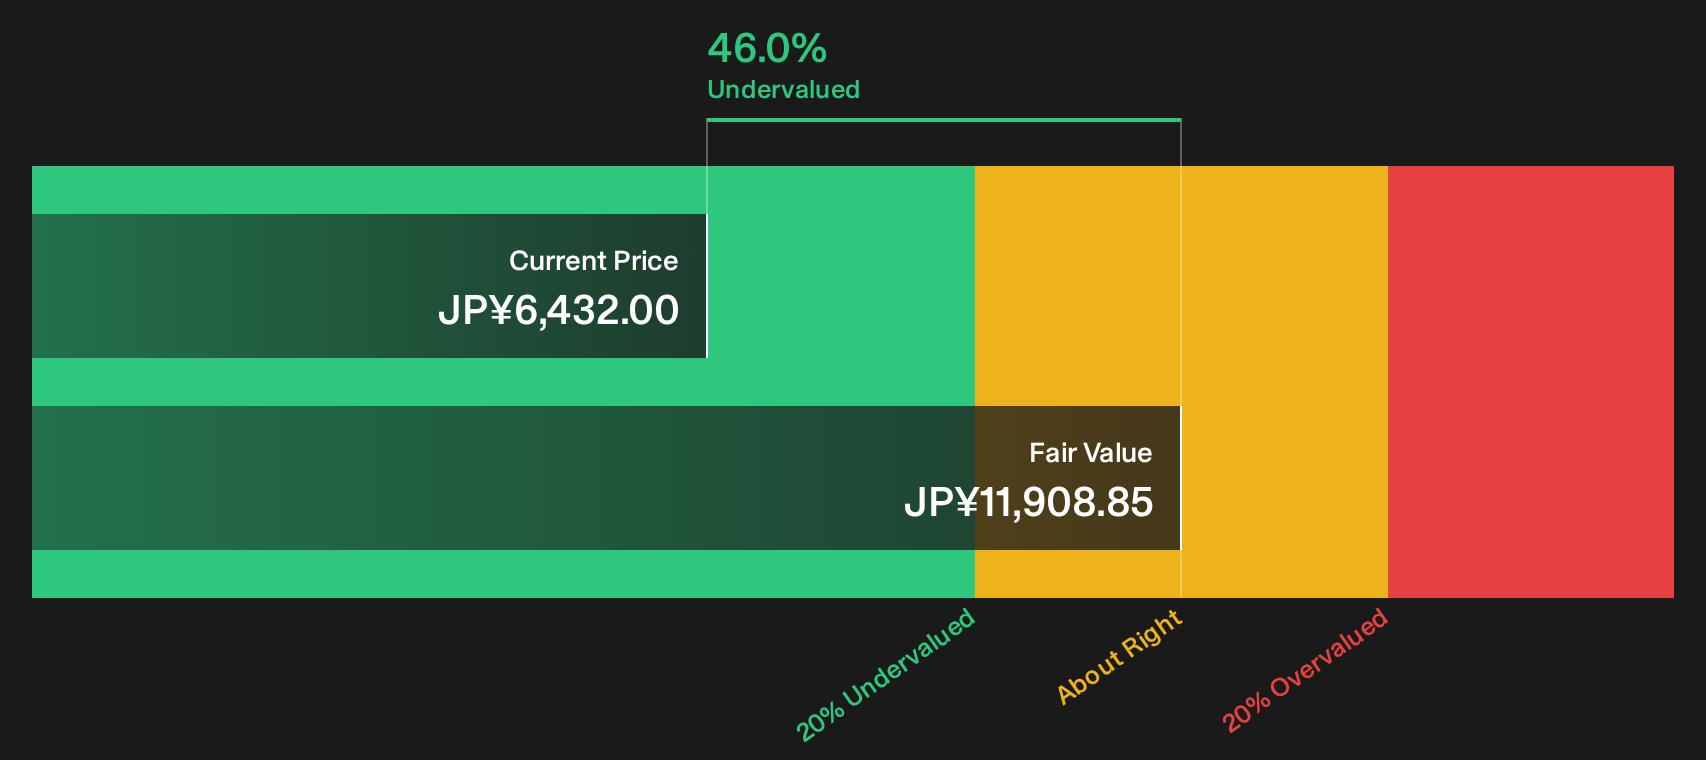
The DCF lens tells a very different story. Murata Manufacturing trades at ¥6,432, while our DCF model points to an estimate of future cash flow value of ¥11,908.85, which is described as 46% above the current price. On this view, the stock screens as undervalued. So which signal do you trust when the earnings multiple appears rich but the cash flow math indicates there is a gap?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murata Manufacturing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Murata Manufacturing is clearly mixed right now, so consider reviewing the numbers for yourself and weighing the 2 key rewards and 1 important warning sign.
Ready for more ideas beyond Murata Manufacturing?
If Murata Manufacturing has your attention, do not stop there. Broaden your watchlist with other clear, research-backed ideas built from consistent screening rules.
- Target potential mispricings by reviewing a curated 14 high quality undervalued stocks that combine earnings strength with more modest valuation multiples.
- Strengthen your income stream by scanning a focused 29 dividend fortresses that aim to pair higher yields with resilient payout histories.
- Sleep easier in rough markets by concentrating on a 21 resilient stocks with low risk scores that emphasise sturdier balance sheets and steadier share price behaviour.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com