
How Investors May Respond To Avient (AVNT) New CEO Appointment
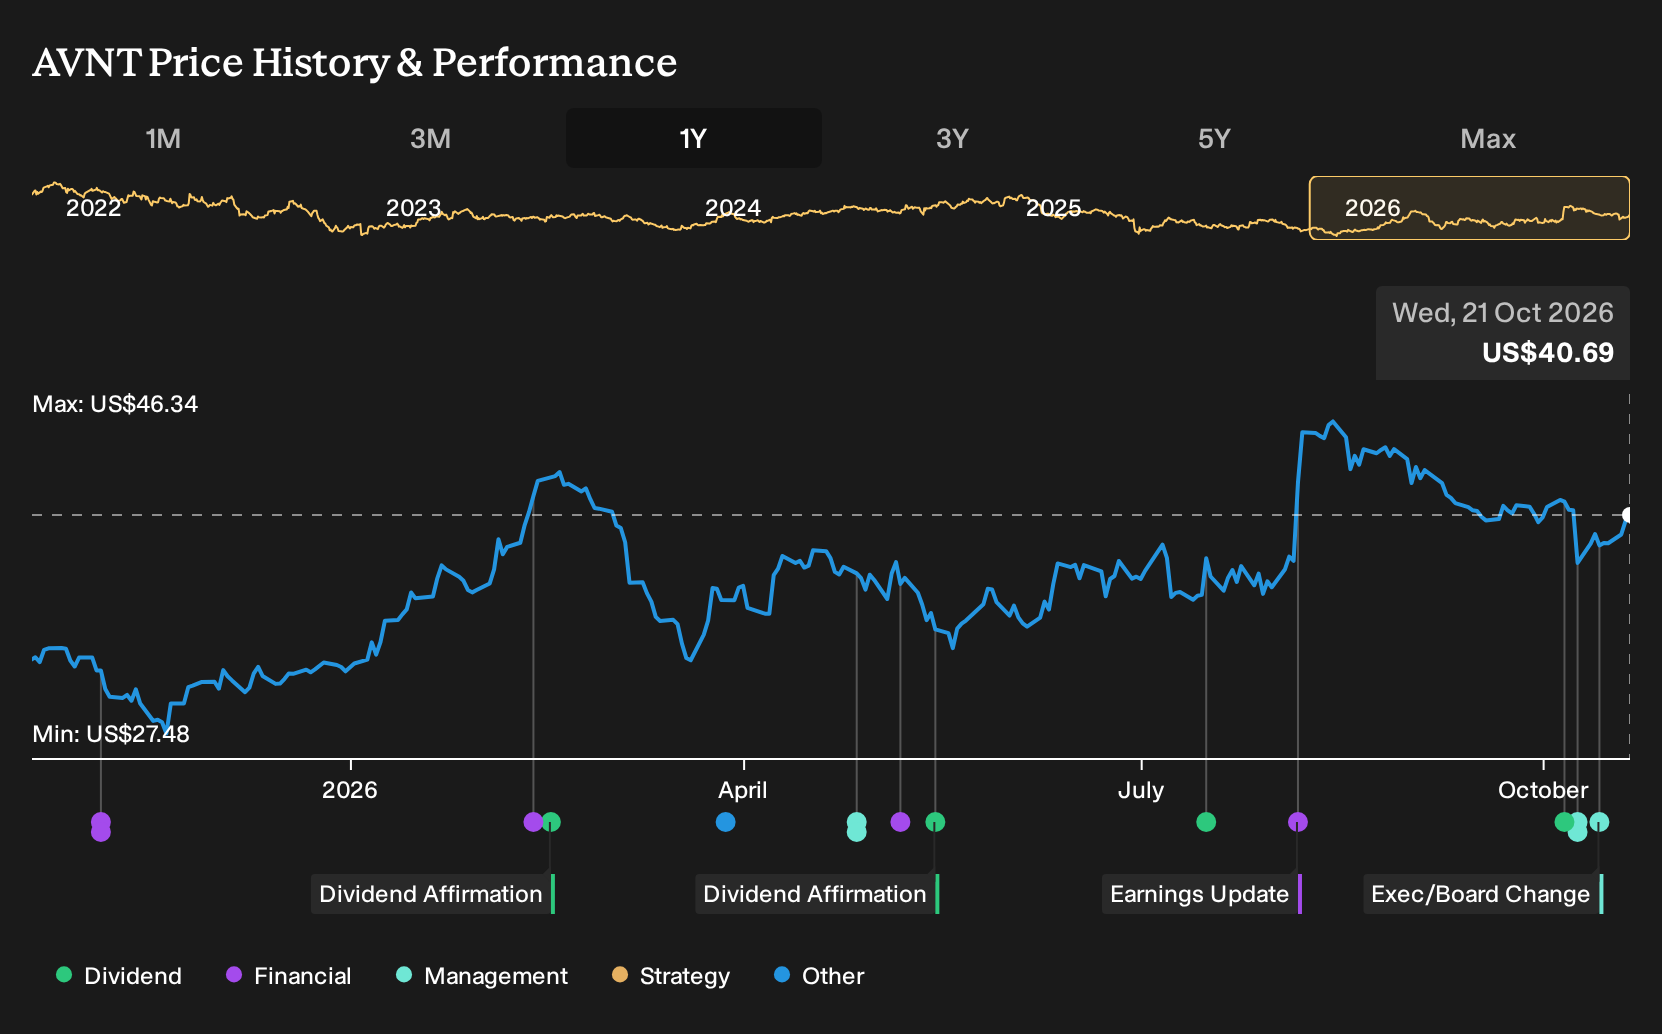
- Avient appointed Mike Frank as Chief Executive Officer and President in October 2026. He was also added to the Board, while Ashish K. Khandpur shifted into an advisory role through year end.
- Frank’s three decade career leading agricultural chemical and solutions businesses introduces deep end market experience that could influence how Avient prioritizes higher value specialty materials opportunities.
- The focus now is on how Avient’s investment narrative evolves as Mike Frank’s appointment as CEO and President reshapes leadership priorities.
Compare Avient's leadership reset with other materials and industrial businesses by scanning a curated 21 high quality undiscovered gems that may also be reshaping their story through fresh executive teams.
Avient Investment Narrative Recap
An investor in Avient needs to believe the company can keep shifting its mix toward higher value electronics, high performance computing and non PFAS packaging while wringing more efficiency out of its footprint. The near term swing factor is whether that higher margin pipeline offsets any lingering softness in transportation and other cyclical uses of its materials.
The biggest risk right now is that weaker vehicle and marine demand lingers longer than expected and blunts operating leverage, especially with debt not yet well covered by operating cash flow. The recent leadership changes look important for execution but do not on their own change those core business drivers.
The most relevant update around this leadership reset is the appointment of Mike Frank as CEO and President, alongside his election to the Board, and Richard Fearon becoming Non Executive Chairman. Frank’s background in specialty agricultural chemicals and large scale operations brings a different lens to how Avient might prioritize end markets and cost structure.
For catalysts, that experience could matter if management leans harder into electronics, data center infrastructure and non PFAS packaging, where analysts already see meaningful growth vectors, while keeping a close eye on productivity programs that previously supported record adjusted EBITDA margins. Execution risk is real, with a relatively new management bench and transportation exposure still hanging over the story.
What Analysts Are Baking Into The Avient Story
For anyone tracking Avient, the market script is already sketched out in the consensus numbers. Analysts are effectively asking investors to underwrite a path where the business leans on higher value materials while growing at a measured pace and expanding profitability.
On the top line, the current models assume revenue increases by 3.9% a year over the next three years. That is a steady rather than aggressive pace, which lines up with a portfolio that mixes cyclical transportation exposure with electronics, healthcare, packaging and other specialty applications.
Earnings today are put at US$170.0 million. The same forecast set points to consensus profits of US$338.5 million by 2029. That is almost exactly a doubling of the bottom line, roughly 2x the current level, built on the expectation that net margins step up from 5.1% to 9.0% over the next three years.
Those profit assumptions sit inside a broader 2029 snapshot. To reconcile the analyst price targets, the models plug in 2029 revenue of about US$3.7b and earnings of US$338.5 million, with Avient valued at a P/E of 17.5x in that same year versus a higher multiple today. The view is that the mix shift and balance sheet work justify higher earnings, while the multiple used in the models still trends lower than both the current P/E and the wider US chemicals sector figure cited in the report.
Share count is not expected to move much in that framework. Forecasts build in only 0.17% yearly growth in shares outstanding over the coming three years, which means most of the earnings ramp is assumed to come from operating performance rather than financial engineering.
All of this sits inside a discounted cash flow style setup that uses an 8.09% discount rate in the Simply Wall St company report, with some references rounded to 8.1% elsewhere in the commentary. That rate, along with the 2029 revenue and earnings targets and the future P/E of 17.5x, underpins the current consensus view of what Avient could be worth on those numbers.
Avient's narrative projects US$3.7b revenue and US$338.5 million earnings by 2029. That path rests on 3.9% yearly revenue growth and an earnings increase of roughly 2x from the US$170.0 million level cited for earnings today.
Uncover why Avient's fair value indicates a 25% potential upside to its current price, an opportunity that could narrow quickly.
Exploring Other Perspectives
Another angle to watch is the more cautious take on Avient's end markets. The lowest analysts were already modeling 4.0% yearly revenue growth to about US$3.7b and earnings of US$321.3 million by 2029 before this CEO and investor relations refresh. That group points to weak packaging and consumer demand, so you can compare several viewpoints and decide how this leadership reset might reshape them.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avient research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avient's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avient?
Once you have a view on Avient, broaden your watchlist by scanning other opportunities where the numbers and stories might line up better with your goals.
- If you care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength before anything else.
- If value is your priority and you want companies where quality and price both matter, run through the 33 high quality undervalued stocks and see which stocks currently line up with that combination.
- If capital preservation sits near the top of your checklist, focus on the 31 resilient stocks with low risk scores to narrow in on businesses flagged with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com