
Ahead of American Express Earnings, Here's What Barchart Data Says Comes Next for AXP Stock
Options traders are betting on a near-term surge in American Express (AXP) shares as the credit card giant reports quarterly earnings before the market opens on Friday. The consensus is for American Express to record $4.47 in earnings per share (EPS) for its third financial quarter. This would represent nearly 8% growth versus Q3 of last year.
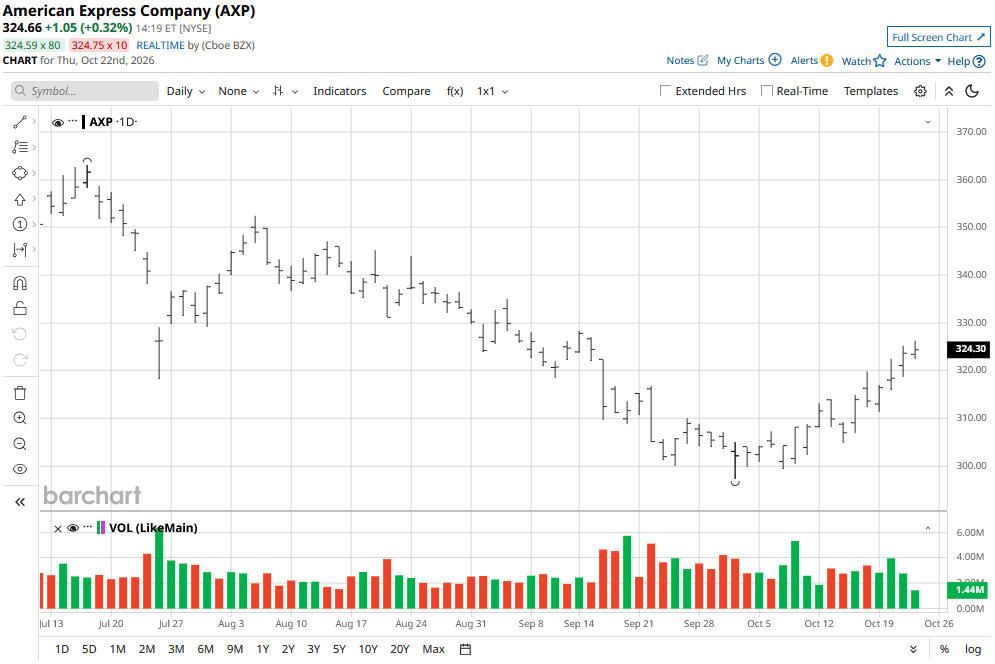
American Express stock has been rather muted in 2026, currently down about 12% versus the start of this year.
Options Data Signals a Post-Earnings Rally in AXP Stock
The technical setup heading into American Express’s earnings event isn’t particularly constructive. AXP stock is yet to reclaim its 100-day moving average (MA), and its RSI in the mid-60s suggests it already sits near overbought levels.
Still, options market sentiment is positive for American Express heading into the quarterly event. The put-to-call ratio on contracts expiring Oct. 30 is set at 0.58x currently, indicating a strong bullish skew.
According to Barchart, the upper price on those contracts is hovering around $335 as of this writing, signaling potential for a 3.28% rally through the end of next week.
A 1.17% dividend yield makes American Express even more attractive as a long-term holding.
What Makes American Express Shares Worth Buying
Beyond options data, AMEX’s premium-card business offers another reason for optimism.
In Q2, cardholder spending climbed 9% on a currency-adjusted basis, its strongest growth in three years, while Platinum became the firm’s fastest-growing U.S. consumer portfolio.
Continued recruitment of millennials and Gen Z clients could extend that momentum, supporting spending and recurring membership fees.
Meanwhile, buybacks offer another earnings tailwind. Average diluted shares outstanding fell 3% year over year in Q2.
Looking ahead, evidence that revenue growth is translating into stronger profitability, or a raised full-year outlook, could provide a key catalyst for American Express shares, particularly if credit losses remain contained.
What’s the Consensus Rating on American Express?
Wall Street analysts also remain convinced that AXP shares are undervalued at current levels.
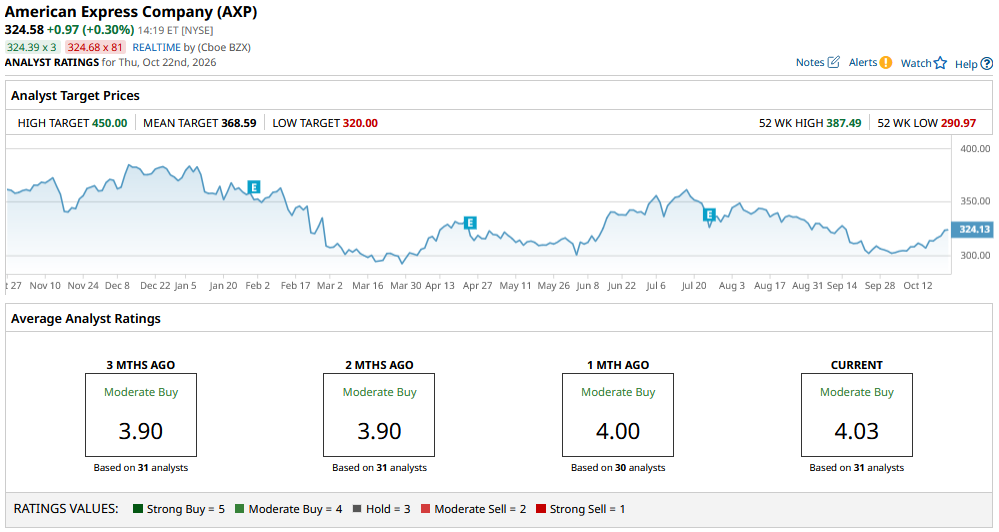
The consensus rating on American Express currently sits at “Moderate Buy,” with the mean price target of about $369 indicating significant upside potential from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.