
Is VinFast Auto (VFS) Cheap Following Its Asset Light Shift And Q2 Earnings?
VinFast Auto (NasdaqGS:VFS) is in the spotlight after its Q2 2026 earnings laid out an unusual mix of heavier ongoing losses, a shift to an asset-light model in Vietnam, and ambitious robotaxi plans.
Recent headlines around VinFast Auto’s asset-light shift in Vietnam, expanded EV leasing offers in the U.S., new electric buses in Europe and stronger domestic deliveries in Vietnam have not stopped the 30 day share price return from falling 11.54%, while the 5 year total shareholder return is down 69.43%. This suggests momentum has faded even as the business pushes new initiatives into multiple markets.
Scan how VinFast Auto compares with other potential turnaround or breakout stories by reviewing a curated set of 21 high quality undiscovered gems that combine strong fundamentals with room for the narrative to evolve.
VinFast Auto now trades at a much lower share price while still chasing scale, robotaxis and an asset-light shift. Does that mix leave more upside for new buyers or more risk for capital already at work?
Most Popular Narrative: 51% Undervalued
VinFast Auto last closed at $2.99, while the most followed narrative pegs fair value near $6.07. That gap rests on the idea that execution on GSM partnerships, asset light manufacturing and emerging market EV demand will eventually be reflected more fully in the share price.
The rollout of VinFast charging infrastructure and GSM ecosystem partnerships across Vietnam and other Asian markets, including commitments for approximately 1 million electric cars and 4 million electric scooters between 2026 and 2030, points to rising utilization of the product base and revenue growth from higher deliveries.
See why 8 investors see VinFast Auto as 51% undervalued.
Result: Fair Value of $6.07 (UNDERVALUED)
Still, the VinFast Auto story only holds if weak gross margins and heavy cash burn improve, and if GSM linked volumes prove resilient rather than inflated by related party demand.
Find out about the key risks to this VinFast Auto narrative.
Another View On VinFast Auto’s Valuation
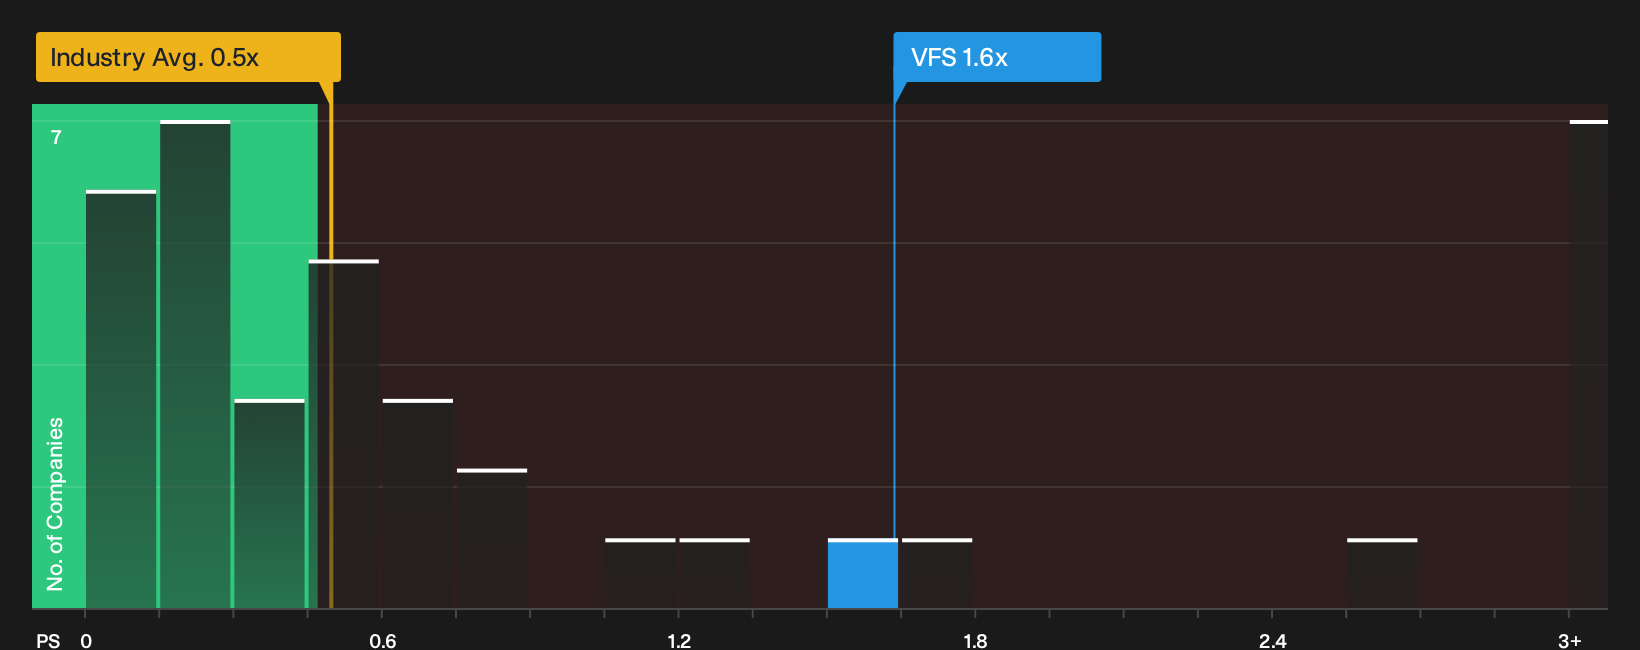
The story shifts once the focus moves from fair value estimates to what the market is actually paying for VinFast Auto’s revenue. The stock trades on a P/S ratio of 1.6x compared with 0.5x for the US Auto industry and 1.3x for peers, while the fair ratio model suggests 0x, which flags meaningful valuation risk if sentiment turns.
That gap leaves a simple question for investors to tackle. Is the premium P/S multiple a reward for future execution, or a pricing mismatch that could unwind if the growth and margin story stalls, especially with forecasts still pointing to ongoing losses.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around VinFast Auto can make it hard to tell whether caution or optimism should carry more weight, so move quickly and pressure test the story against your own expectations by reviewing the 1 key reward and 3 important warning signs
Looking for more VinFast Auto sized opportunities?
If VinFast Auto has sharpened your focus on risk and reward, do not stop here. Broaden your watchlist now so you are not late to the next story.
- Target potential upside in neglected corners of the market by scanning a curated set of 21 high quality undiscovered gems that pair strong fundamentals with limited attention.
- Strengthen portfolio resilience by focusing on companies with healthier finances and a sturdier footing using the list of solid balance sheet and fundamentals (25 results).
- Lock in income ideas that may complement growth holdings by reviewing a hand picked group of 7 dividend fortresses built around higher yields and stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com