
Eastern Bankshares (EBC) Nears Earnings, Is It A Bargain Or Fully Priced?
The clock is ticking for Eastern Bankshares (EBC), with the regional lender set to report quarterly earnings this Thursday after the closing bell. Expectations center on higher profit, stronger revenue and improved operating efficiency.
Eastern Bankshares shares have been gaining momentum into the release, with a 7-day share price return of 3.26% and a year to date move of 16.02% at a last close of US$21.51. The 1-year total shareholder return of 20.29% and very large 3-year total shareholder return of about 10x highlight how strongly sentiment has shifted over a longer horizon.
Scan beyond Eastern Bankshares and line up other regional lenders showing similar earnings momentum with the hand-picked 33 high quality undervalued stocks that may be priced for a potential breakout.
Eastern Bankshares now trades at a clear discount to both analyst targets and one estimate of fair value, even after the recent climb. Is that caution about the bank justified, or has the rerating barely started?
Most Popular Narrative: 14% Undervalued
On the most followed valuation view, Eastern Bankshares is priced below an assessed fair value of $25.13, with the shares last closing at $21.51. That gap rests on a story that leans heavily on mix shift, fee income and repricing rather than a simple bet on top line growth.
The multi year repricing of roughly US$2.8b of loans and US$1.5b of securities that currently earn around 4% to 6% on loans and 2.86% on securities, combined with comparatively low deposit costs that were around 1.46% to 1.51% in 1H 2026, is expected by management to be accretive to net interest income and to support margins as older assets roll off.
See why 2 investors see Eastern Bankshares as 14% undervalued.
Result: Fair Value of $25.13 (UNDERVALUED)
Still, that story can unravel quickly if deposit costs rise faster than planned or if net interest income aligns with the lower end of 2026 guidance.
Find out about the key risks to this Eastern Bankshares narrative.
Another View: Eastern Bankshares On Earnings Multiples
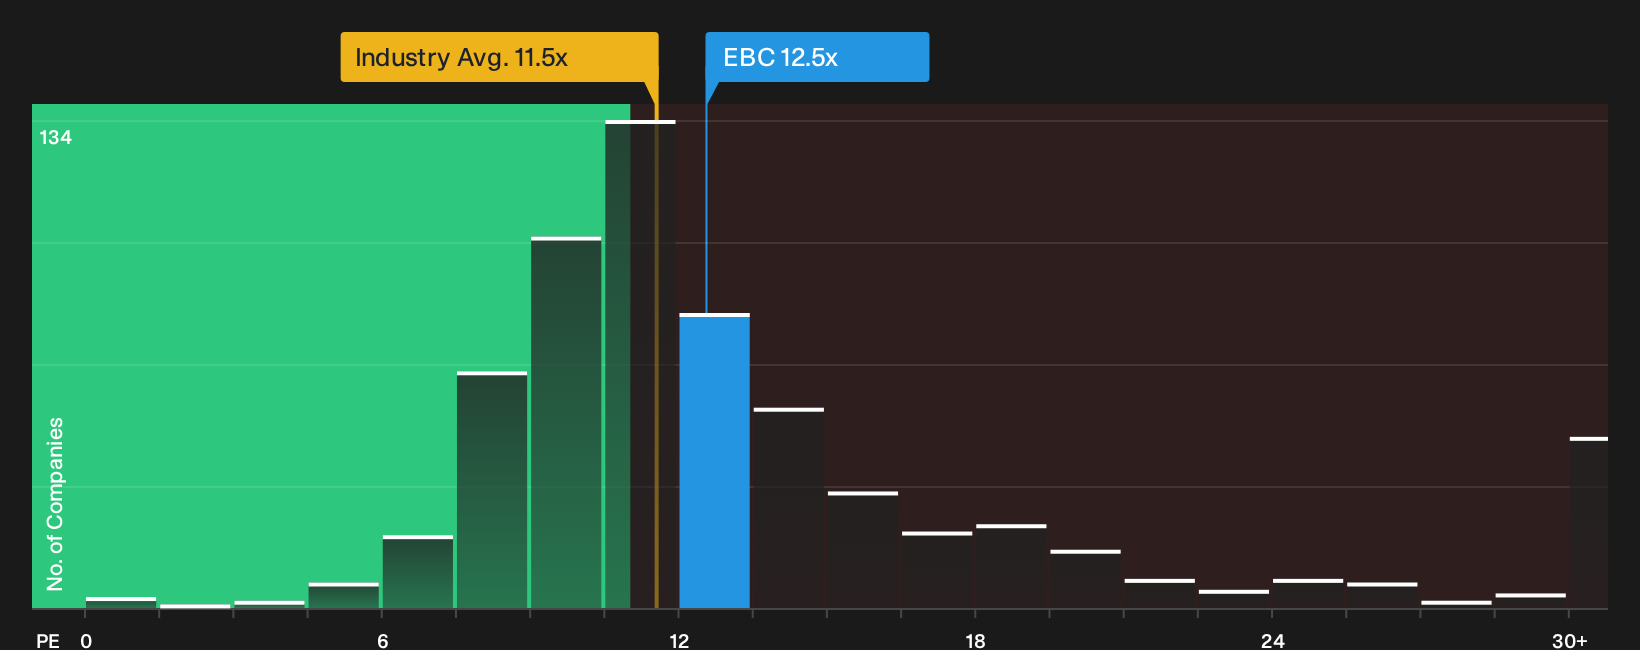
A different lens on Eastern Bankshares comes from its P/E of 12.5x. That sits above the US Banks industry at 11.5x and almost exactly on the fair ratio of 12.4x, which points to limited room for error if the profit story disappoints.
For anyone weighing that risk against the upside case built on earnings and capital returns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Eastern Bankshares story so far. If you want to move quickly and build your own view off the data, consider the balance of 3 key rewards and 1 important warning sign.
Looking for more Eastern Bankshares investment ideas?
Do not stop with Eastern Bankshares. Use the Simply Wall St screener to quickly uncover fresh opportunities that match your style before other investors get there.
- Target strong value potential by zeroing in on companies that combine quality metrics with pricing that still looks reasonable through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with cleaner finances and sturdier capital positions using the list of solid balance sheet and fundamentals (25 results).
- Spot under-the-radar opportunities early by scanning for companies with solid fundamentals that have yet to gain wide attention via the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com