
Oriental Land (TSE:4661) Could Be 2% Undervalued After EPS Estimates Rose
Oriental Land (TSE:4661) is back in focus after fresh analyst commentary pointed to higher consensus EPS expectations for the current year and a favorable Zacks Rank, setting up a debate over what investors are really paying for.
Recent trading has leaned in Oriental Land's favor, with a 1-day share price return of 1.42% adding to a 30-day gain of 8.07% and a 90-day rise of 22.27%. However, the 1-year total shareholder return is still down 5.88% after a 3-year decline of 28.66%, so recent momentum is building from a weaker long-term base.
Compare Oriental Land's rebound with a hand picked group of consumer-focused businesses showing similar earnings momentum and price action through the 73 high quality undiscovered gems.
After a sharp short term move and a modest discount to analyst targets, Oriental Land now sits between two readings. Is the market being too cautious, or are investors underestimating the risks?
Most Popular Narrative: 2% Undervalued
On the most followed view, Oriental Land’s fair value of ¥3,357.80 sits only slightly above the last close of ¥3,280. This puts the spotlight on how much more earnings power the parks and hotels can realistically produce from roughly flat attendance.
The opening of Fantasy Springs and new attractions is still expected to support guest attendance beyond the initial launch phase. This can help Oriental Land sustain Theme Park net sales and operating profit.
Merchandise and food and beverage sales are backed by record net sales per guest of ¥18,403 in FY ended March 2026 and about 5% year-on-year growth in Q1 FY ending March 2027. Further use of variable pricing and Disney Premier Access is expected to keep supporting revenue and net sales per guest.
See why 1 investors see Oriental Land as 2% undervalued.
Result: Fair Value of ¥3,357.80 (ABOUT RIGHT)
Still, the optimistic Oriental Land story frays quickly if rising personnel and maintenance costs squeeze margins further, or if guests resist higher ticket tiers and Premier Access.
Find out about the key risks to this Oriental Land narrative.
Another View: What Oriental Land’s P/E Is Really Saying
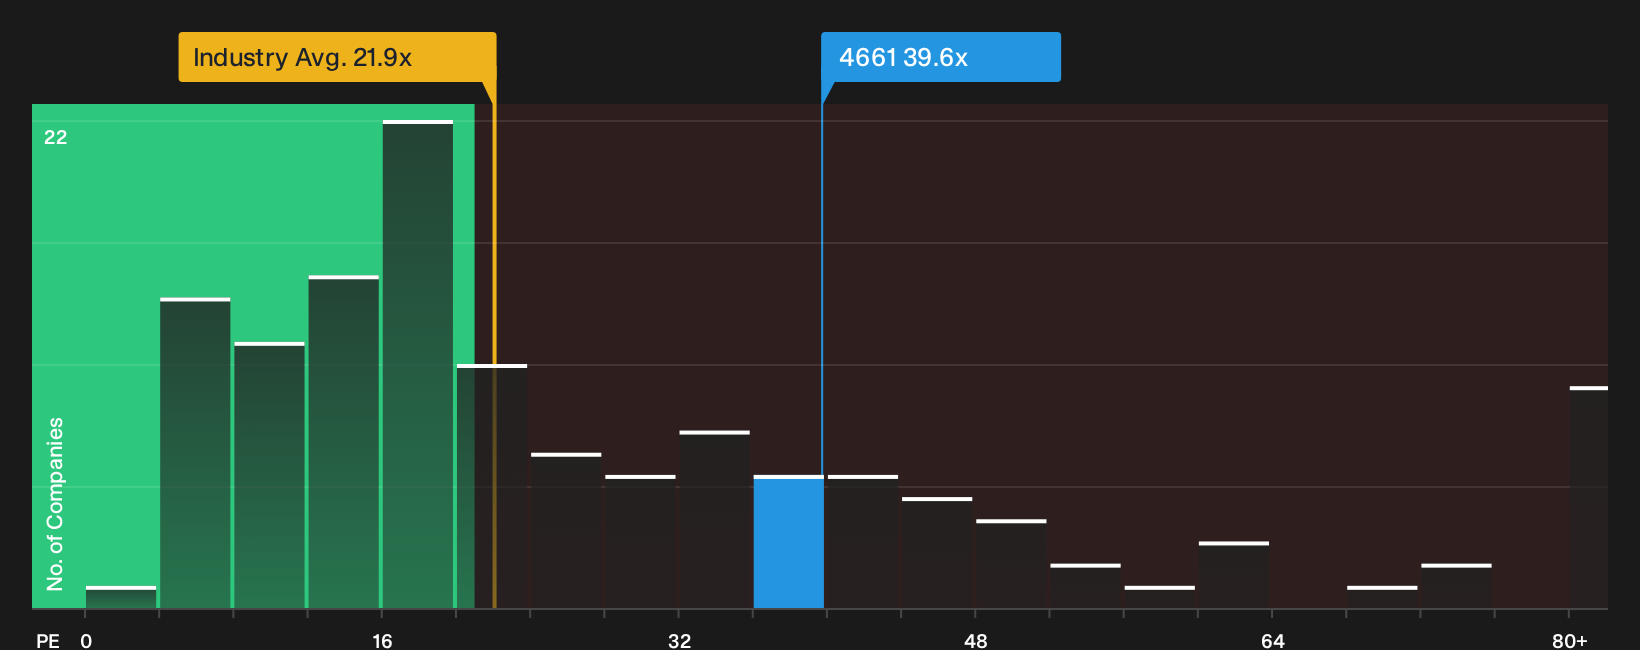
Analysts calling Oriental Land roughly fairly priced on a fair value of ¥3,357.80 are looking at future earnings power. A simple P/E check tells a very different story. The stock trades on 39.6x earnings, which is more than double peer averages at 18.7x and well above the estimated fair ratio of 30.3x. That gap points to a rich valuation where even small disappointments on margins or guest spending could matter a lot more than a 2% discount to fair value suggests.
To see how that earnings multiple stacks up in more detail, and what the fair ratio implies the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Oriental Land is finely balanced right now, so treat this as your cue to move fast, inspect the data yourself, and weigh the upside against the obvious risks. To see what the current optimism is based on, start with the 2 key rewards.
Looking for more investment ideas beyond Oriental Land?
If Oriental Land has your attention, do not stop there. Broaden your watchlist with other clear setups where the numbers and story already line up.
- Target dependable compounders by reviewing companies with a list of solid balance sheet and fundamentals (22 results) that can better absorb shocks and keep funding their plans when conditions turn difficult.
- Spot potential mispricings early by scanning the 14 high quality undervalued stocks before the crowd closes the gap between current quotes and underlying fundamentals.
- Lock in steadier income streams by checking out a curated group of 29 dividend fortresses that already clear a 5% yield hurdle with added focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com